


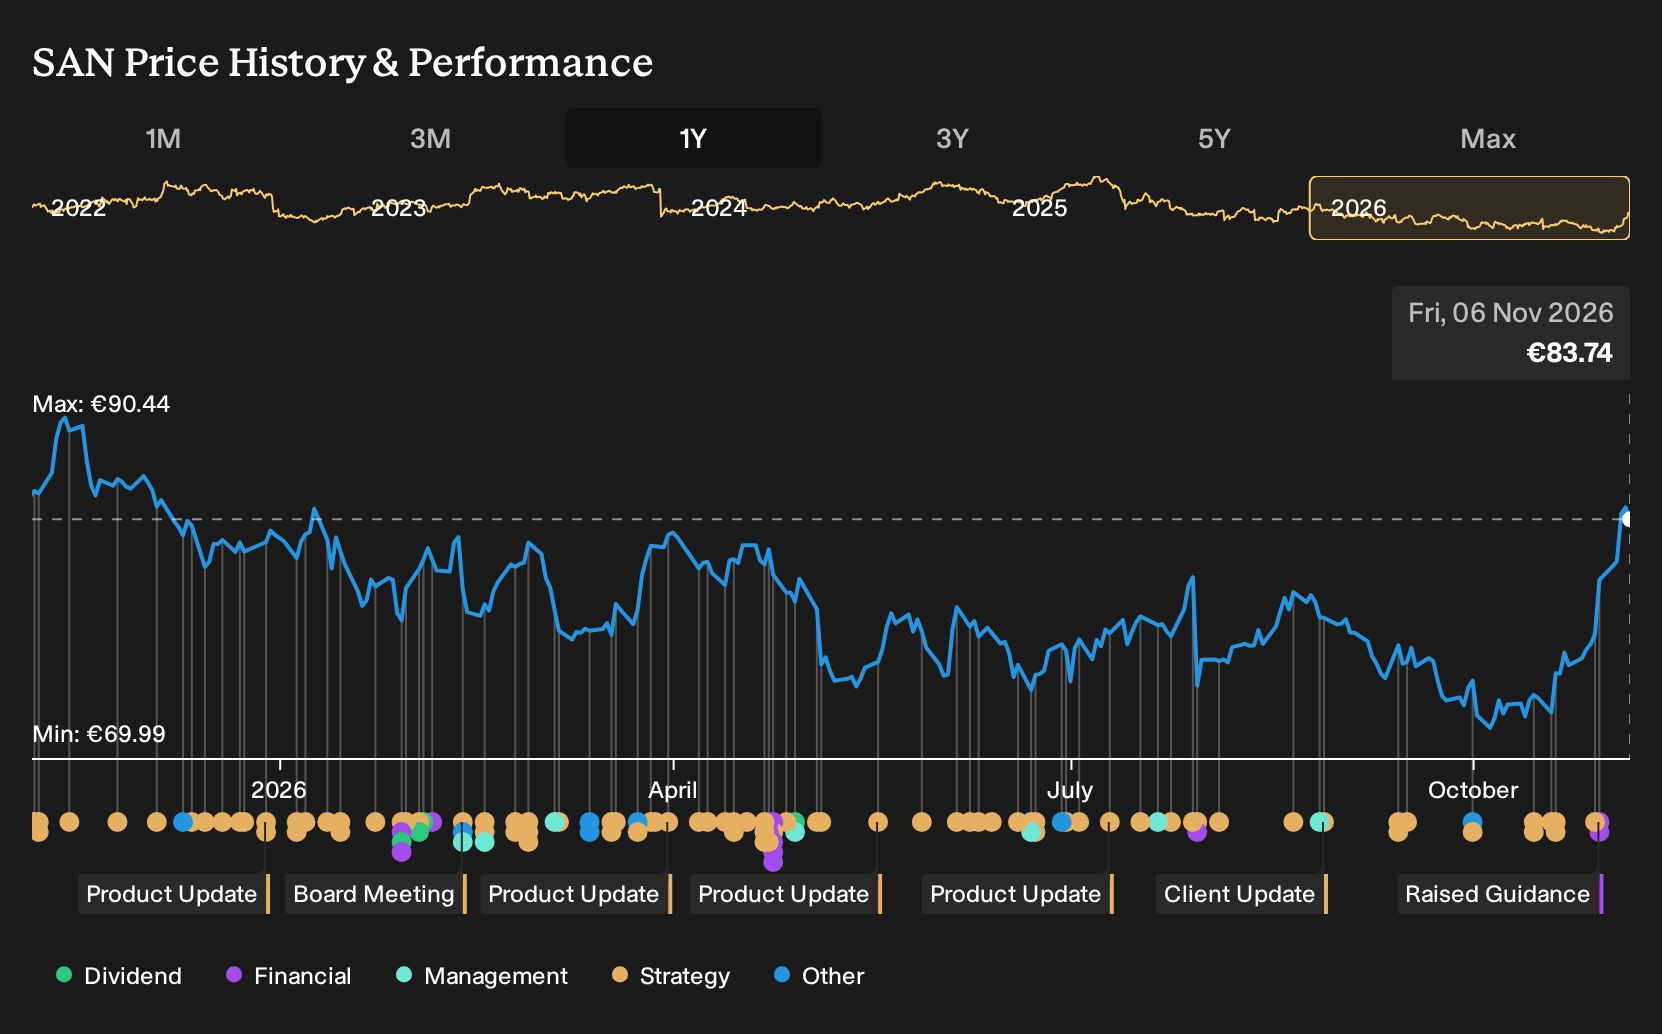
- Sanofi reported past third quarter 2026 sales of €14,444 million and net income of €3,021 million, with basic EPS from continuing operations of €2.52, and lifted full year 2026 guidance to low teens sales growth and mid teens EPS growth at constant exchange rates.
- The combination of higher reported quarterly earnings and a more confident 2026 outlook indicates that Sanofi views its current product mix and cost base as supportive of stronger operating performance than previously guided.
- It remains to be seen how Sanofi's raised 2026 earnings guidance could reshape the existing investment narrative around its pipeline and margins.
Track how Sanofi's earnings reset compares with other large healthcare bellwethers by scanning our curated list of 126 healthcare AI stocks that could be gearing up for their next guidance upgrade.
Sanofi Investment Narrative Recap
To own Sanofi, you need confidence that disciplined R&D decisions, a growing specialty and rare disease portfolio, and a recalibrated vaccines business can convert into steadier earnings despite a mixed profit history. The raised 2026 guidance points to management seeing enough momentum in the current portfolio to support stronger near term delivery.
The most important near term swing factor remains execution on late stage assets and business development that can refill the pipeline after recent terminations. The main risk is that pricing pressure in flu vaccines and lower net margins persist, especially with regulatory scrutiny around Efluelda adding cost and limiting pricing flexibility.
The guidance upgrade on low teens sales growth and mid teens EPS growth at constant exchange rates sits alongside Sanofi's recent move into a Phase 3 influenza COVID 19 combination vaccine using Novavax's Nuvaxovid with Efluelda or Fluzone High Dose. This trial directly relates to the vaccines repositioning that investors have been watching.
If the combination program progresses as planned and meets clinical and regulatory requirements, it could become one of the more important follow on levers for the vaccines portfolio. This portfolio already faces softer U.S. coverage and pricing pressure. Any delay, safety concern, or weaker than hoped uptake would reinforce existing worries about vaccines returns and margin quality.
Sanofi's narrative projects €54.6b revenue and €10.9b earnings by 2029. This aligns with analyst expectations for 3.7% yearly revenue growth and implies an earnings increase of about €7.0b from €3.9b today.
Uncover why Sanofi's fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Sanofi’s push to use external partnerships and AI driven discovery as a catalyst. Before this earnings beat and guidance hike, they were already modeling about €59.0b of 2029 revenue and €14.0b of earnings. You can compare that more upbeat script with your own view and explore how it might shift after this quarter.
Explore 5 other Sanofi fair value estimates, including one that suggests potential upside of up to 191% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sanofi research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Sanofi. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sanofi's overall financial health at a glance.
Looking for more investment ideas beyond Sanofi?
If this Sanofi earnings reset has you rethinking where the next opportunity might come from, use the Simply Wall St Screener to line up other candidates that match your risk tolerance, income needs, or preference for balance sheet strength.
- If you want potential income plus resilience, start with a shortlist of established payers by reviewing our 228 dividend fortresses that may suit a more income focused portfolio.
- If capital preservation matters most to you, concentrate on sturdier businesses by checking out a 209 resilient stocks with low risk scores that could help reduce portfolio swings.
- If you are hunting for quality businesses that the market may be overlooking, scan through a 581 high quality undiscovered gems and see which stories deserve a spot on your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com