


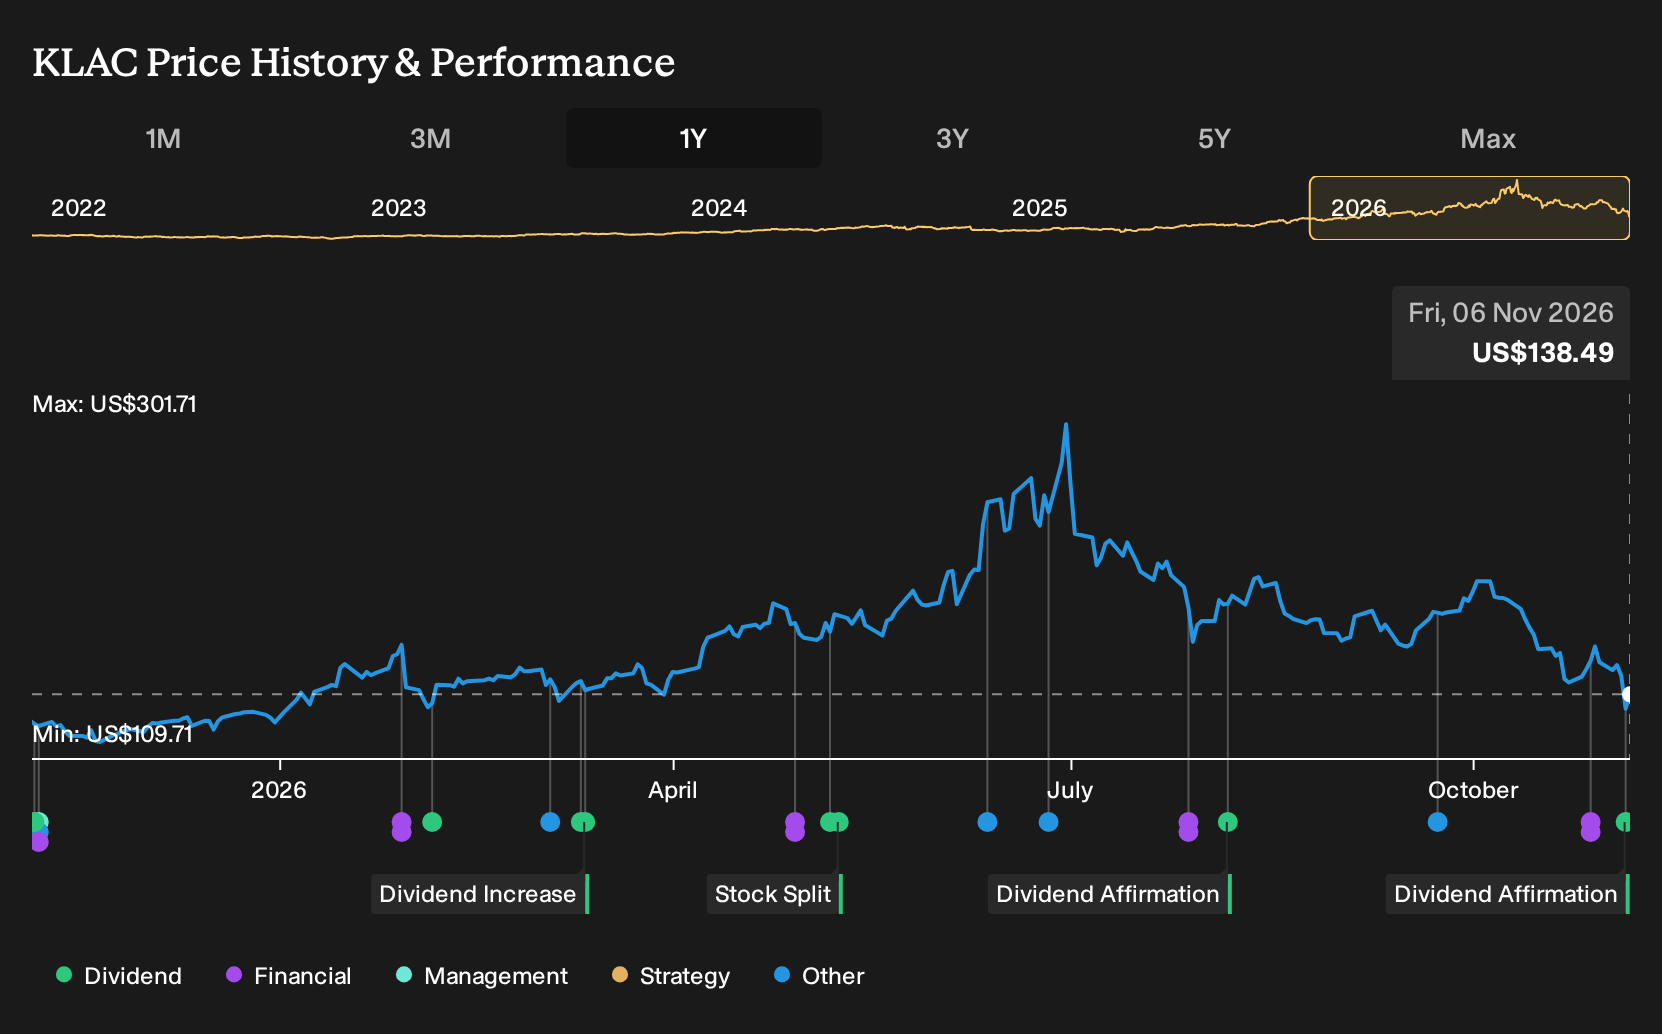
- KLA Corporation reported fiscal first quarter 2027 revenue of US$4,136.02 million and net income of US$1,548.59 million, alongside continued quarterly dividends, including a US$0.23 per share payout declared for shareholders of record on November 16, 2026.
- The latest results highlight KLA’s role in inspection and process diagnostics for AI oriented chips and advanced packaging. Management pointed to a sizeable backlog and guidance that reflects both input cost pressure and ongoing demand for high end process control tools.
- This article will examine how KLA's first quarter earnings and guidance influence the broader investment narrative around its backlog conversion.
Scan how KLA's AI oriented tools fit into the broader build out of chip infrastructure by checking out 53 AI infrastructure stocks along with this earnings and dividend update.
KLA Investment Narrative Recap
To own KLA, you need to believe that AI driven wafer investments and advanced packaging continue to require more process control and that the current US$12.5b backlog converts into high margin systems and services over time. The latest quarter, with US$4,136.02m in revenue and US$1,548.59m in net income, supports that operating backdrop.
The key near term swing factor remains how effectively KLA executes on that backlog while managing export rules and foundry capex pauses. The biggest live risk still sits in gross margin pressure from tariffs and higher memory costs. This earnings report and guidance do not materially change that risk reward balance.
The fresh piece of news that ties closest to this story is the new earnings outlook for the December 2026 quarter. Management guided revenue to US$4.7b plus or minus US$200m, GAAP gross margin to 61.8% plus or minus 1.0%, and GAAP diluted EPS to US$1.41 plus or minus US$0.11.
This guidance provides a reference point for how KLA expects to work through its order book while handling input cost and export related friction. It also frames the short term catalyst, as investors will likely focus on whether reported gross margin tracks that 61.8% target range and how much of the long dated backlog converts into actual quarterly shipments.
KLA's narrative projects US$25.9b revenue and US$10.8b earnings by 2029. This assumes 21.3% yearly revenue growth and an earnings increase of about US$5.5b from US$5.3b today.
Uncover how KLA's fair value indicates a 63% potential upside to its current price before the market moves to close that gap.
Exploring Other Perspectives
For KLA, the most optimistic analysts lean hard into backlog as a catalyst. Before this dividend and earnings news, some were modelling revenue climbing to about US$29.3b and earnings to roughly US$13.0b by 2029, which is far above consensus. Use this spread in expectations as a cue to compare several viewpoints yourself.
Explore 5 other KLA fair value estimates, including one that suggests as much as 113% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your KLA research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for KLA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KLA's overall financial health at a glance.
Looking for more investment ideas beyond KLA?
Once you have a handle on KLA, it can help to cross check your thesis against other companies with different risk and return profiles using the Simply Wall St Screener.
- For investors who want companies that look cheap relative to fundamentals, scan a curated set of 38 high quality undervalued stocks that might warrant a closer look.
- If capital preservation matters most to you, narrow the field to businesses that score well on resilience through our 31 resilient stocks with low risk scores and compare how their profiles differ from KLA.
- When you want to go beyond the usual large caps, broaden your watchlist by checking a 19 high quality undiscovered gems that may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com