


Medpace Holdings (MEDP) is back in focus after record third quarter awards and an expanded clinical pipeline shifted attention to the strength of its backlog rather than short term revenue moderation.
Recent trading has reflected that shift in focus. The share price is up 6.71% over the past month and 8.41% over 90 days, while Medpace Holdings has delivered a 10.86% 1 year total shareholder return and a very large 3 year total shareholder return, suggesting momentum has been building rather than fading.
Scan how Medpace Holdings fits alongside other contract research and healthcare specialists by reviewing the hand picked 35 healthcare AI stocks in the same broader theme of clinical and data driven medicine.
Medpace Holdings now trades a touch above the average analyst target, yet still shows a modeled intrinsic discount. Is the recent surge justified, or is the fair value line sitting somewhere else entirely?
Most Popular Narrative: 22% Overvalued
According to the most widely followed valuation thesis, Medpace Holdings screens as materially overpriced, with a fair value of $536 against a last close of $653.11. The gap between price and narrative estimate is wide enough that investors tend to ask what is driving the premium.
Medpace appears to be a high-quality CRO because it combines a differentiated small-biotech focus, strong therapeutic expertise, a global full-service platform, operating margins above 20%, low capital requirements, substantial cash and no funded debt. A balanced conclusion is that it has built a strong position in a difficult-to-replicate part of the CRO market. However, its revenue is not locked in, its customers can be financially fragile, and founder control brings related-party governance considerations.
See why 8 investors see Medpace Holdings as 22% overvalued.
Result: Fair Value of $536 (OVERVALUED)
Still, two weak spots could crack this Medpace Holdings story quickly: tighter biotech funding and any rise in trial cancellations or delays.
Find out about the key risks to this Medpace Holdings narrative.
Another View: Cash Flow Says Medpace Holdings Is Slightly Cheap
That 22% overvaluation call is not the only story on Medpace Holdings. Our DCF model, which prices the stock off future cash flows, points to a value of about $696 per share versus the current $653.11. On that math, the stock screens roughly 6% undervalued. Which signal matters more to you, narrative multiples or cash flow math?
To see how that cash flow framework works in practice, and where the key assumptions sit on growth, margins and discount rates, take a closer look at the Look into how the SWS DCF model arrives at its fair value.
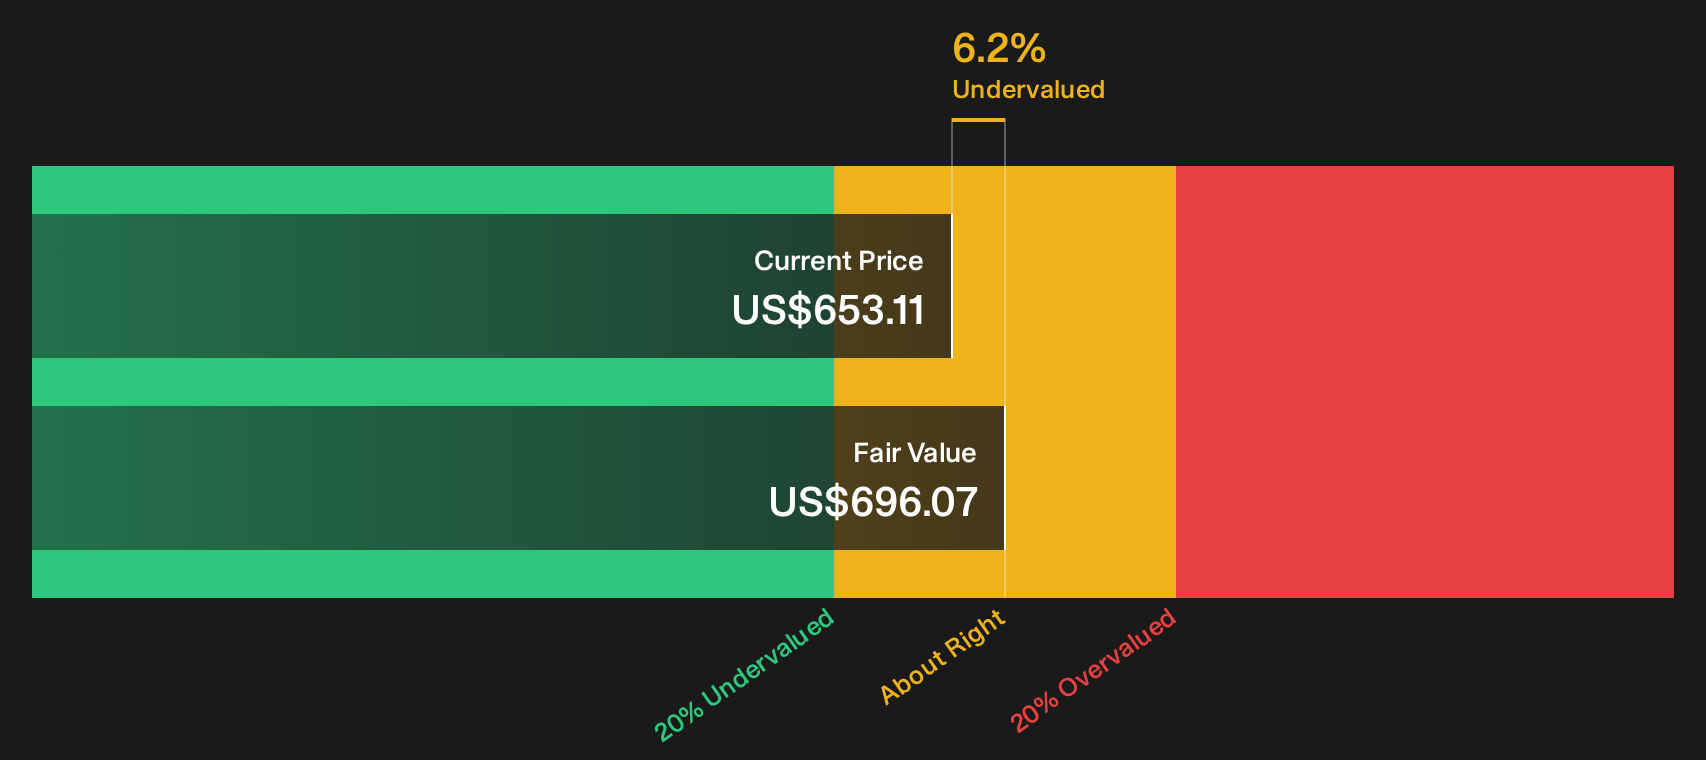
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Medpace Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 38 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views on Medpace Holdings so far. Consider the current split in sentiment and weigh the potential benefits against the concerns by reviewing the 3 key rewards and 1 important warning sign
Looking for more Medpace Holdings sized ideas?
Do not stop at Medpace Holdings. Broaden your watchlist with fresh ideas from the Simply Wall Street Screener that could fit different roles in your portfolio.
- Target potential mispricing by reviewing the 38 high quality undervalued stocks that combine solid fundamentals with prices that sit below modeled fair value.
- Strengthen your defensive core by scanning the list of solid balance sheet and fundamentals (25 results) and focus on companies with robust financial footing.
- Hunt for early stage potential by checking the 19 high quality undiscovered gems that the broader market may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com