


- Kinetic, a Kinetic Holdings subsidiary, recently partnered with SKYOVI to apply an AI design platform across 2.2 million homes, while Uniti Wholesale expanded 100G and 400G wavelength connectivity at nine data centers across six states and introduced promotional offers on select routes.
- The AI driven drop-design automation and higher capacity wavelength services point to Uniti Group sharpening execution on fiber build speed, cost control, and large-scale bandwidth demand.
- We will examine how Uniti Group's investment narrative is affected by its AI assisted fiber design push across Kinetic's footprint.
Scan beyond Uniti Group to explore fiber and AI infrastructure momentum by reviewing a curated list of 53 AI infrastructure stocks that are already wired for rising data demand.
Uniti Group Investment Narrative Recap
To own Uniti Group, you need to believe the heavy fiber build and AI assisted design work can offset pressure from shrinking legacy services and high leverage. The big near term swing factor is whether fiber driven recurring revenue ramps fast enough to support interest costs and keep capex plans intact, without stretching the balance sheet further.
The SKYOVI and wavelength moves help execution more than they immediately change that funding equation. Faster drop design and higher capacity routes might support fiber uptake and wholesale demand, but the main risk still sits with refinancing terms, elevated Kinetic capex, and the pace at which older services decline against new fiber revenue.
The SKYOVI rollout inside Kinetic looks most relevant here. The platform is intended to cut buried drop cycle times by over 60%, automate route design across 2.2 million homes, and tighten material tracking. For a fiber program already deploying about US$1.4b in buildings and equipment over twelve months, any operational efficiency can matter for keeping projects on schedule.
For catalysts, investors are watching whether Uniti Group can translate that AI enabled speed into more homes passed within guidance, tighter cost control per build, and fewer surprises in field execution. The risk is that even with better design tools, fiber revenue and lease up may not outpace legacy declines and high funding needs quickly enough to ease pressure on cash flow and refinancing.
Uniti Group's narrative projects US$3.8b revenue and US$336.6m earnings by 2029. This rests on 2.4% yearly revenue growth and an earnings decline of about US$653.5m from US$990.1m today.
Uncover how Uniti Group's fair value indicates a 107% potential upside to its current price that could narrow quickly if sentiment shifts.
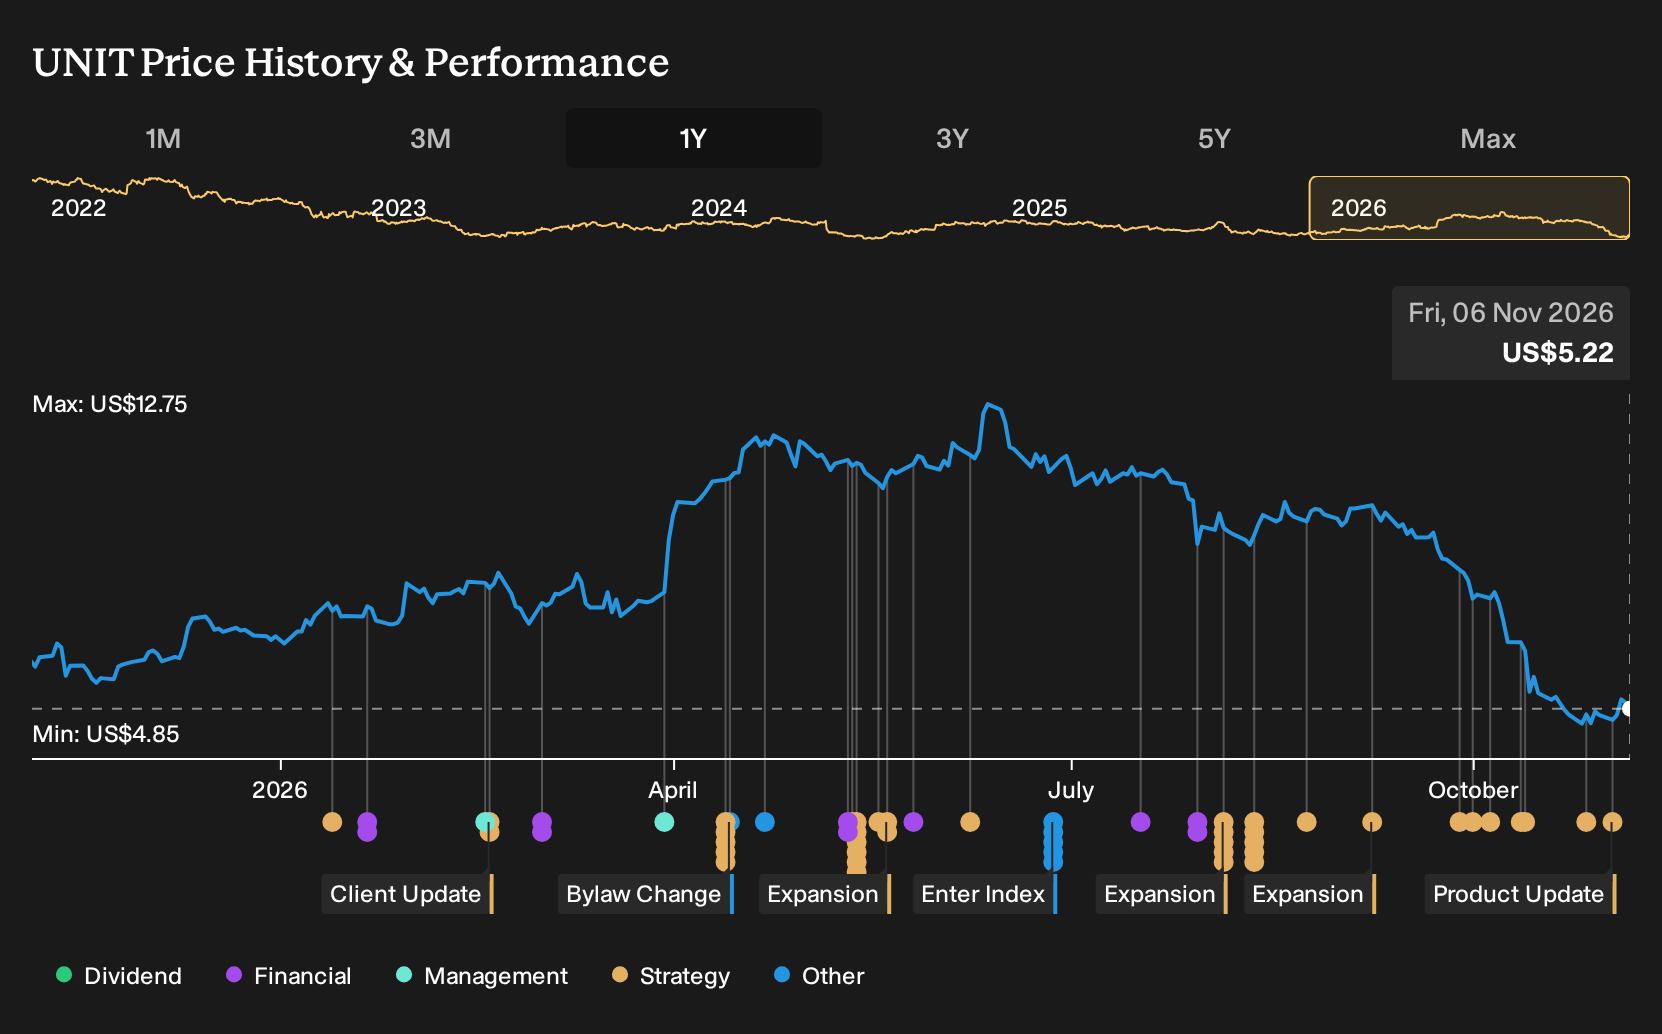
Exploring Other Perspectives
For Uniti Group, the lowest analyst narrative worries less about AI design tools and more about funding risk. Those analysts were only assuming about 1.5% yearly revenue growth to roughly US$3.7b and earnings of about US$327.3m by 2029. That is a much cooler story. The fresh SKYOVI news could eventually shift those views, so explore the full range of forecasts rather than leaning on a single camp.
Explore another Uniti Group fair value estimate, including one that suggests there could be as much as 28% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Uniti Group research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Uniti Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Uniti Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Uniti Group?
Once you have formed a view on Uniti Group, it can help to widen the lens and compare it with other businesses that fit different risk and return profiles. The Simply Wall St Screener makes that process faster so you can focus on judging the trade offs rather than trawling through endless tickers.
- If you want potential mispricing with quality in mind, start with a curated set of 38 high quality undervalued stocks that pair solid fundamentals with a price that may not fully reflect them yet.
- If capital preservation matters as much as upside, pivot to a 31 resilient stocks with low risk scores that focuses on companies with more resilient risk scores and steadier profiles.
- If you prefer sturdier balance sheets behind the story, use the list of solid balance sheet and fundamentals (25 results) to zero in on businesses with stronger financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com