


Flywire (FLYW) has investors’ attention after third quarter earnings on 3 November 2026, with higher sales, improved profitability metrics, and upgraded revenue guidance now paired with fresh traction in global B2B payments.
Over the past year, Flywire has shifted from a quietly compounding story to one that investors are actively re-pricing, with a 55.2% year to date share price return and a 59.1% total shareholder return reflecting enthusiasm around upgraded guidance and new B2B wins like the Liquidity Services partnership, even as the 5 year total shareholder return of a 51.8% decline reminds you that momentum here is still relatively recent rather than a long uninterrupted run.
Scan opportunities riding similar payments and fintech momentum by reviewing the hand picked 19 high quality undiscovered gems that share Flywire’s blend of software, data, and transaction revenue models.
After a 59.1% total return over the past year and fresh guidance upgrades, Flywire’s story looks very different to 12 months ago. The key question for investors is whether the current price still leaves enough potential upside to justify the risk.
Most Popular Narrative: 1.8% Undervalued
Against a last close of $21.57, the most followed narrative pegs Flywire’s fair value at $21.96. This keeps the spotlight squarely on whether analysts have the right long term assumptions baked in.
Project ADAPT and wider digital transformation are expected to peak in investment in 2027. After that, management plans to keep operating costs roughly flat while still funding priorities. Recent adjusted EBITDA margin expansion into the low 20% range indicates that further operating leverage could support higher net margins and earnings.
See why 9 investors see Flywire as 2% undervalued.
Result: Fair Value of $21.96 (UNDERVALUED)
Still, pressure on cross border education volumes from tighter visa rules, along with a bigger tilt toward lower margin processing in healthcare and B2B, could quickly challenge that undervalued Flywire narrative.
Find out about the key risks to this Flywire narrative.
Another View: Flywire Looks Expensive On Earnings
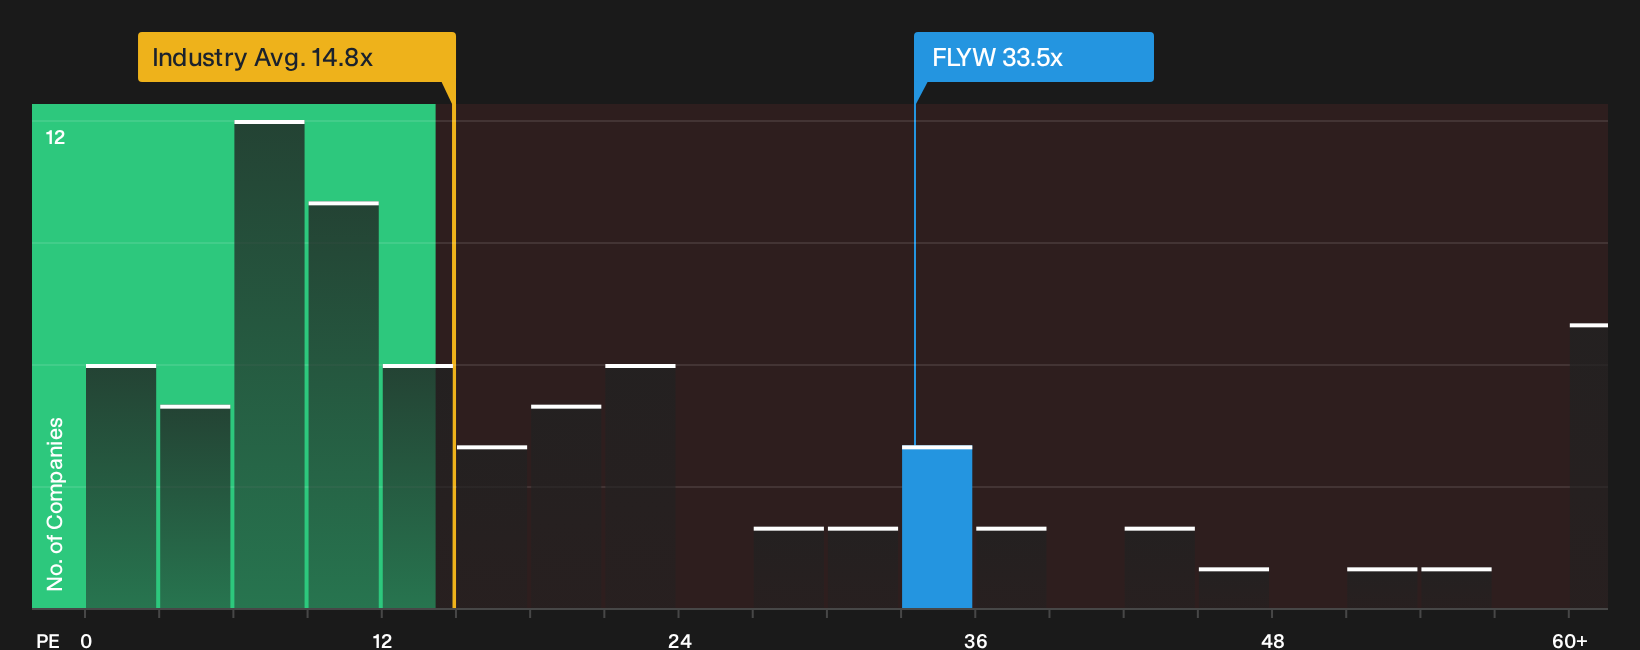
While the analyst narrative points to Flywire as 1.8% undervalued on a fair value of $21.96, the P/E tells a tougher story. At 33.5x earnings, the stock trades above both peers at 33x and a fair ratio of 14.3x, which signals meaningful valuation risk if expectations cool.
That kind of gap between today’s P/E and the fair ratio is the sort of thing that can compress quickly if sentiment or forecasts reset. It is worth asking how much optimism you are really paying for here, and how comfortable you are with that premium.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The tone of this Flywire story appears mixed so far. Given the combination of flagged risks and potential upside, consider acting promptly and stress testing the numbers yourself by reviewing the 3 key rewards and 1 important warning sign.
Looking for more Flywire style investment ideas?
If Flywire has sharpened your focus, do not stop here. Use data driven screeners to uncover fresh opportunities before they move out of reach.
- Target resilient balance sheets by reviewing the list of solid balance sheet and fundamentals (25 results) that pair financial strength with room for growth.
- Zero in on mispriced opportunities through the 38 high quality undervalued stocks that highlight strong fundamentals at comparatively modest valuations.
- Secure your income stream with the 7 dividend fortresses that filter for higher yielding businesses with robust payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com