


Skyward Specialty Insurance Group (SKWD) just put fresh numbers on the table, reporting third quarter revenue of US$455.34 million and net income of US$49.8 million. This gives investors new data to assess the stock.
Skyward Specialty Insurance Group's stock has been on a strong run, with a year to date share price return of 24.13% and a 1 year total shareholder return of 27.11%. This is despite the share price falling 5.5% on the day of the results, and the 3 year total shareholder return of 97.74% points to momentum that has built over time rather than faded.
Capture this earnings momentum in context by comparing Skyward Specialty Insurance Group with selected insurers in our 31 resilient stocks with low risk scores.After a strong run and a drop on the results day, Skyward Specialty Insurance Group now forces a choice: lean into the recent momentum, or wait and hope the valuation offers a cleaner entry later on?
Most Popular Narrative: 14% Undervalued
Skyward Specialty Insurance Group closed at $60.35, while the most followed narrative pegs fair value closer to $70.55. This frames the latest pullback as a move inside a much bigger valuation story.
The build out of diversified specialty lines such as Accident & Health, agriculture, credit and surety and specialty programs is creating multiple premium streams. Management describes these streams as largely insulated from traditional property and casualty cycles, which can support steadier revenue and earnings quality for Skyward Specialty Insurance Group.
Ongoing investment in machine learning tools, the Sky View underwriting workstation, bionic underwriting and Agentic AI products like SkyScore, together with automation of claims payments through the ClaimsSnap partnership, is already tied to faster submissions and quotes and a lower expense ratio. This can support net margin expansion if these tools scale across more of the portfolio.
See why 15 investors see Skyward Specialty Insurance Group as 14% undervalued.
Result: Fair Value of $70.55 (UNDERVALUED)
Still, this narrative can be tested quickly if catastrophe losses at Apollo remain elevated or if higher loss ratio Accident & Health and agriculture lines are mispriced.
Find out about the key risks to this Skyward Specialty Insurance Group narrative.
Another View: What P/E Says About Skyward Specialty Insurance Group
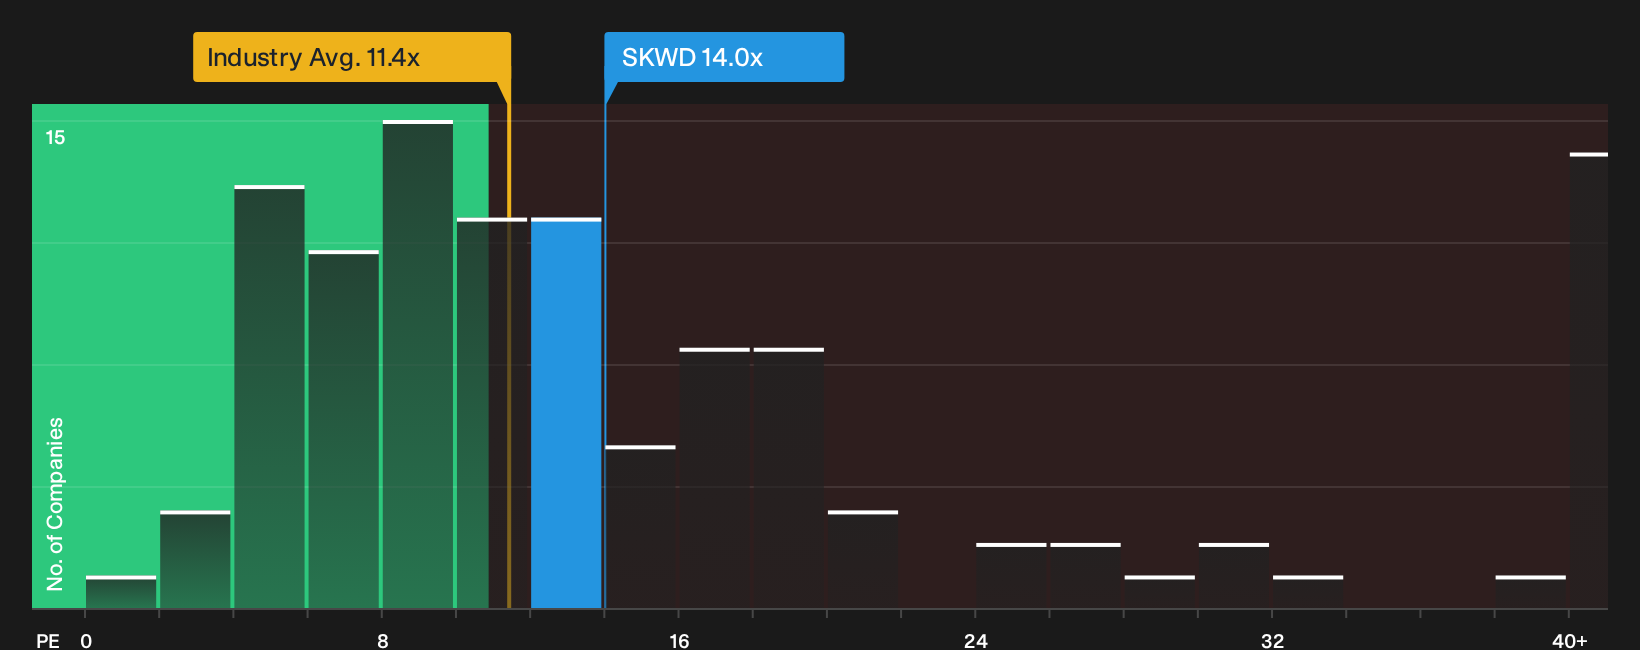
The DCF work points to Skyward Specialty Insurance Group trading well below an estimate of future cash flow value. The P/E picture is less generous. At about 14x earnings, the stock trades above the US Insurance industry on 11.4x and well ahead of peer averages near 6.3x.
The fair ratio suggests a P/E closer to 13.7x. That gap is small in absolute terms, yet it still means you are paying a premium today and relying on the story to keep working. If sentiment cools before the fundamentals catch up, how comfortable are you holding that valuation risk?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling the mixed mood around Skyward Specialty Insurance Group after these results and valuation debates. Act promptly, review the data yourself, and consider the 3 key rewards.
Looking for more investment ideas beyond Skyward Specialty Insurance Group?
If Skyward Specialty Insurance Group has your attention, do not stop here. Broader opportunities often sit just outside the stocks already on your radar.
- Target potential mispricing by scanning a focused set of quality stocks that appear out of favor using the 38 high quality undervalued stocks.
- Strengthen your watchlist by filtering for businesses with sturdier finances through the list of solid balance sheet and fundamentals (25 results).
- Get ahead of the crowd by reviewing the 19 high quality undiscovered gems that pair strong fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com