


DoorDash has seen sharp swings in recent years, and the stock now trades near a level where investors are asking whether its earnings are strong enough to support today’s valuation. A series of high profile moves in grocery delivery and subscriptions adds another layer to that question, because each decision ultimately has to show up in the income statement to justify the current share price.
- Over the past 3 years, DoorDash has delivered a return of about 105.4%, which puts real pressure on its earnings to keep pace with the higher expectations baked into that move.
- The planned US$17b acquisition of Instacart, along with new offerings like Lyft Go and lower fee Meal Boxes, can reshape how quickly DoorDash converts its larger delivery footprint and customer base into more durable earnings.
- There is a second opinion on DoorDash worth weighing. See what analysts think DoorDash's shares could be worth.
The issue now is whether DoorDash’s current share price around US$179.67 is adequately supported by the earnings power that the business is producing today.
If you are weighing DoorDash against similar earnings driven stories, it can help to compare it with 38 high quality undervalued stocks that also focus on quality and valuation discipline.
Is DoorDash Getting Expensive on Earnings?
For a profitable platform business like DoorDash, the P/E ratio is a useful shorthand for how much investors are paying for each dollar of earnings.
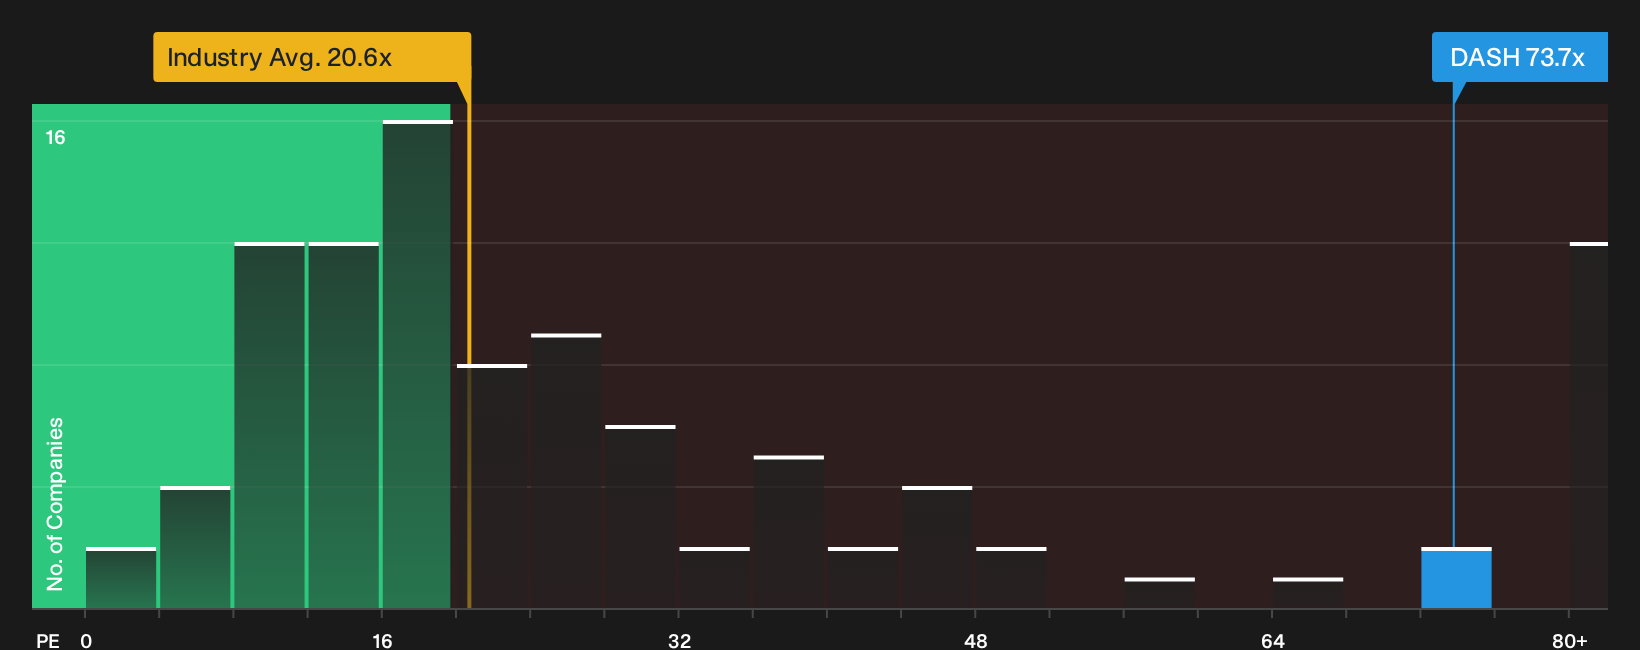
DoorDash trades on a P/E of about 73.7x, which is far above the Hospitality industry average of roughly 20.6x and also materially above the peer group at about 27.1x. The market is therefore assigning a sizable premium to the stock’s earnings compared with sector and peer benchmarks.
The Fair Ratio model, which tries to estimate a P/E that fits DoorDash’s own growth profile, margins, scale and risks, points to a lower multiple than the current 73.7x, so the shares screen as overvalued on this framework. Despite optimism around the planned Instacart acquisition broadening DoorDash’s reach in grocery delivery, the current P/E still assumes a richer earnings profile than the model suggests. Investors weighing DoorDash against other opportunities may want to study how much earnings durability and integration success they are willing to price into that gap. Explore the numbers behind DoorDash's P/E valuation.
The DoorDash Narrative: What Would Justify Today's Price?
Narratives for DoorDash pick up where the P/E debate leaves off by spelling out the specific growth, margin and earnings paths that would need to play out for the current share price to look meaningfully cheap or expensive. Where a single ratio or valuation model offers one output, these storylines unpack the future that figure rests on so you can watch how reality lines up over time on Simply Wall St's Community page.
One of the top community narratives on DoorDash: roughly fairly valued
"The current narrative that DoorDash is fairly valued implies the share price already reflects meaningful contributions from new verticals and international operations..."
Discover why this Narrative puts DoorDash at roughly fairly valued.
One more DoorDash signal that could change how you see the story
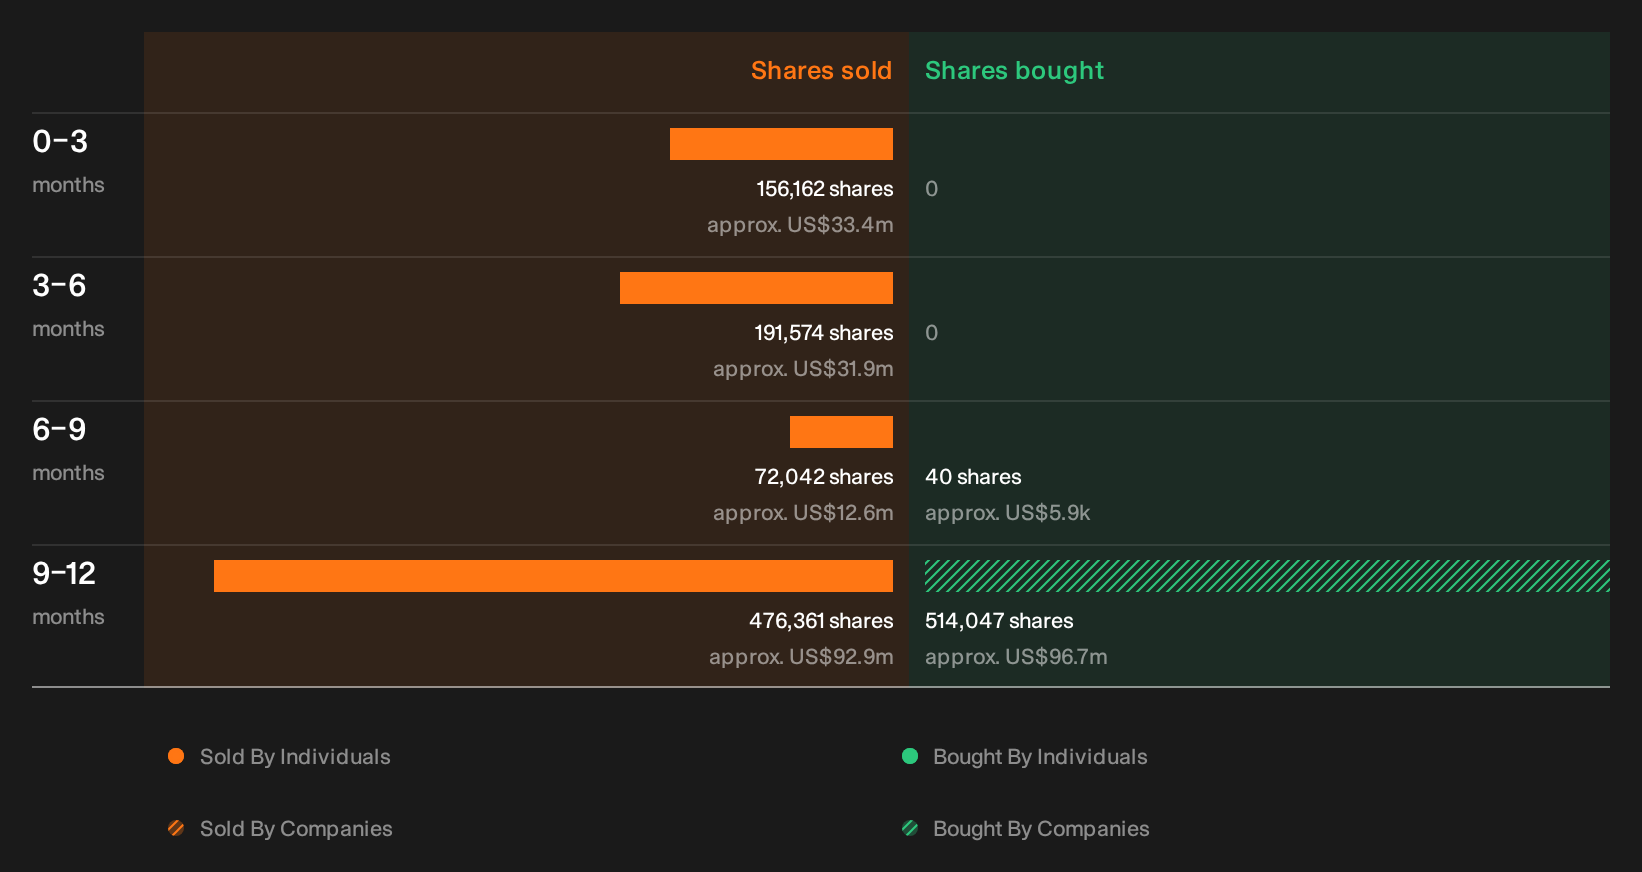
Before wrapping up your research on DoorDash, it is worth checking what recent insider share sales might suggest about how key people around the business are acting right now. See the recent insider selling flagged for DoorDash.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com