


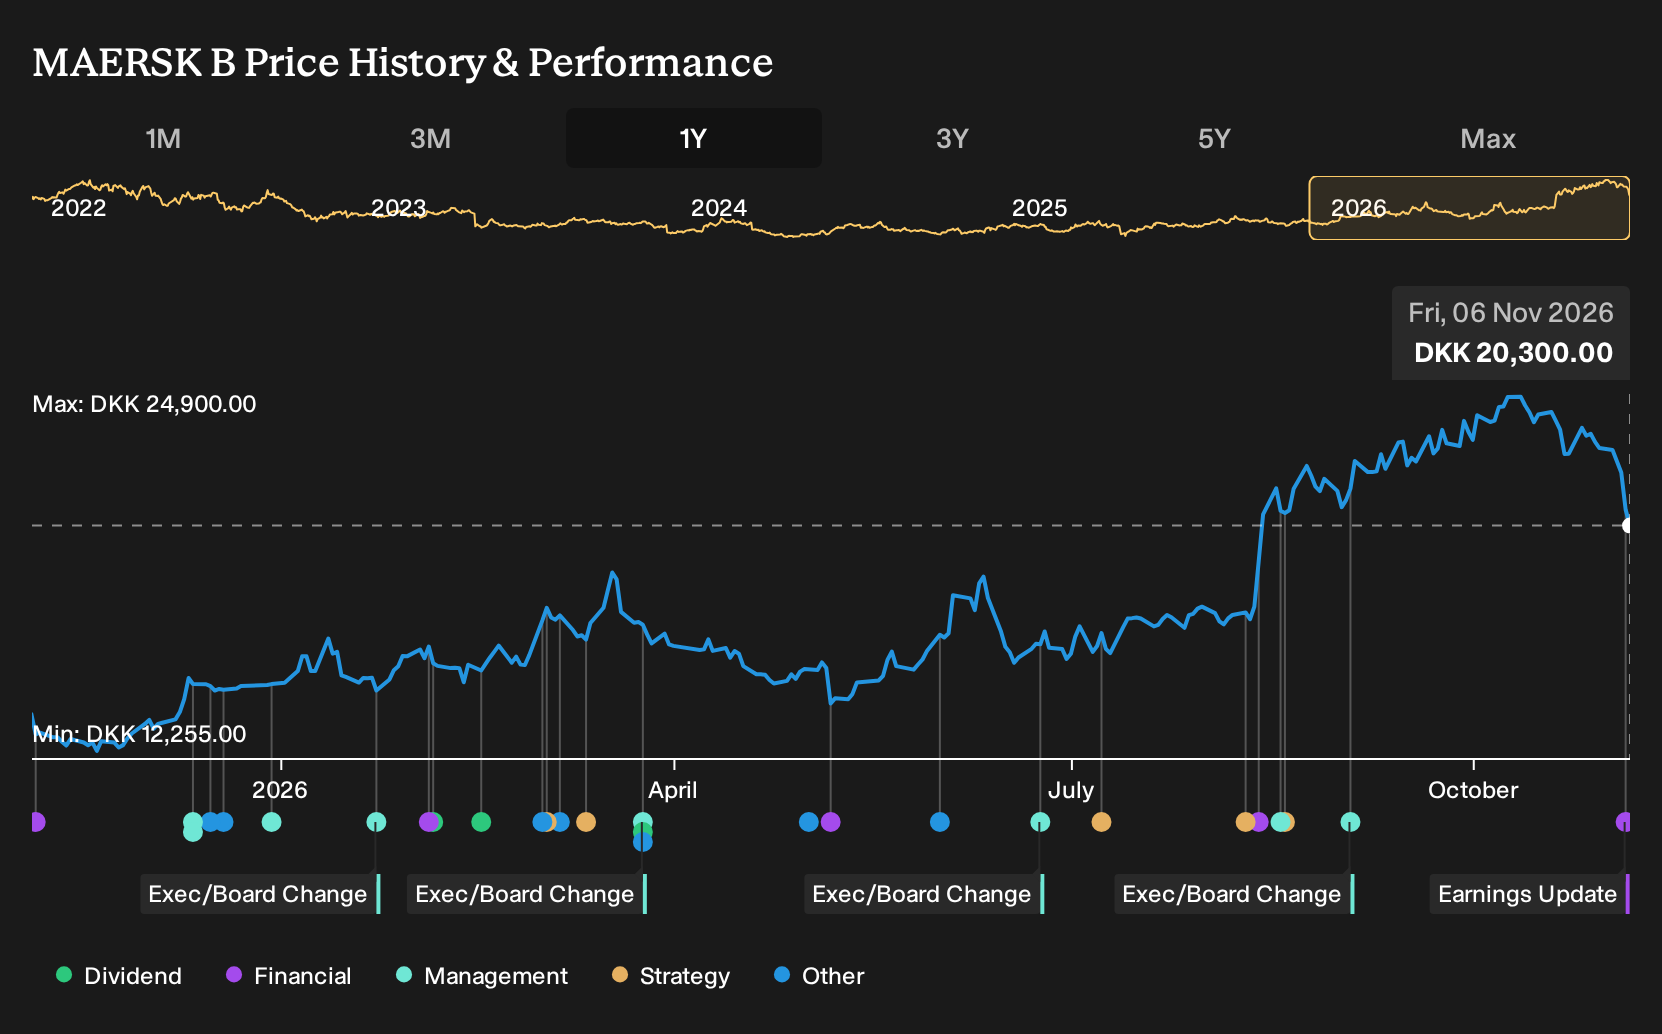
If you had been weighing A.P. Møller - Mærsk on 6 November 2025, the headlines were full of guidance tweaks, Red Sea route changes and fresh worries about overcapacity. For A.P. Møller - Mærsk shareholders, the return over the past year was 61.9%, including dividends. If you were deciding whether to buy at that point, how would you have balanced booming e-commerce logistics plans against concerns that freight strength was built on disruptions that could fade?
A.P. Møller - Mærsk has already moved. See which of 225 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Had To Choose Between On A.P. Møller - Mærsk
The shares cost DKK12,735 at the start of the period, and anyone looking at A.P. Møller & Mærsk then was really choosing between two very different stories about how global trade and e-commerce would shape its future.
The bullish view pointed to a Fair Value of DKK14,435, a price level implied by assumptions that digital efficiency, premium end to end logistics contracts and green shipping investments would support earnings resilience even if revenue decreased by 0.8% a year and profit margins fell toward 0.2%.
The more cautious camp worked off a Fair Value of DKK11,802, based on expectations that revenue would decline 3.6% a year and that reliance on Chinese export strength, rising capital expenditure and industry overcapacity could limit Maersk to a 2.3% profit margin and a 24.7x P/E in 3 years.
What The Results Changed For A.P. Møller - Mærsk
Maersk’s Q3 2026 report gave the bullish story fresh support. Revenue was US$18,095m against US$14,206m a year earlier, with net income at US$2,986m versus US$1,047m. Net margin moved from 7.4% to 16.5%, which challenged the cautious view that profitability would compress quickly.
The lesson is simple. When a thesis hinges on margin pressure or resilience, watch the reported net margin first, and then test any freight rate or capacity claims against that line before debating the P/E.
What A.P. Møller - Mærsk’s Price Now Assumes
A.P. Møller - Mærsk trades at DKK20,300, after a 61.9% gain over the past year from DKK12,735. The selected Narrative’s Fair Value sits below the current price, framing that gap as a question about how long tight freight conditions and recent earnings strength can last.
This Narrative focuses on whether cost gains from networks like Gemini and expansion in Logistics & Services and Terminals can really offset future capacity growth and heavy multi year investment. Anyone paying today’s price is effectively assuming those efficiency plans and demand trends hold up. How does that square with the capacity and execution risks it flags?
"Although A.P. Møller Mærsk is currently benefitting from strong headhaul demand out of Asia and high utilization in Ocean, the surge of new vessel deliveries through 2027 and the CEO’s acknowledgement of a capacity overhang means fleet growth can still outstrip effective demand once landside bottlenecks ease, which would squeeze freight rates and compress Ocean EBITDA and net margins."
The price and this Narrative do not agree. → Uncover what this Narrative says A.P. Møller - Mærsk is actually worth
Which Company Could Surprise You Next?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 41% below our estimate - targets everyday athletes as it shifts from underwear into higher margin sports fashion.
- Company 2 - 19% below our estimate - leans on custom security hardware and a unified system to deepen long term client lock in.
- Company 3 - 15% below our estimate - recruits senior lawyers seeking flexible self employed work onto an asset light legal services platform.
That is three of the list. See all 192 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com