


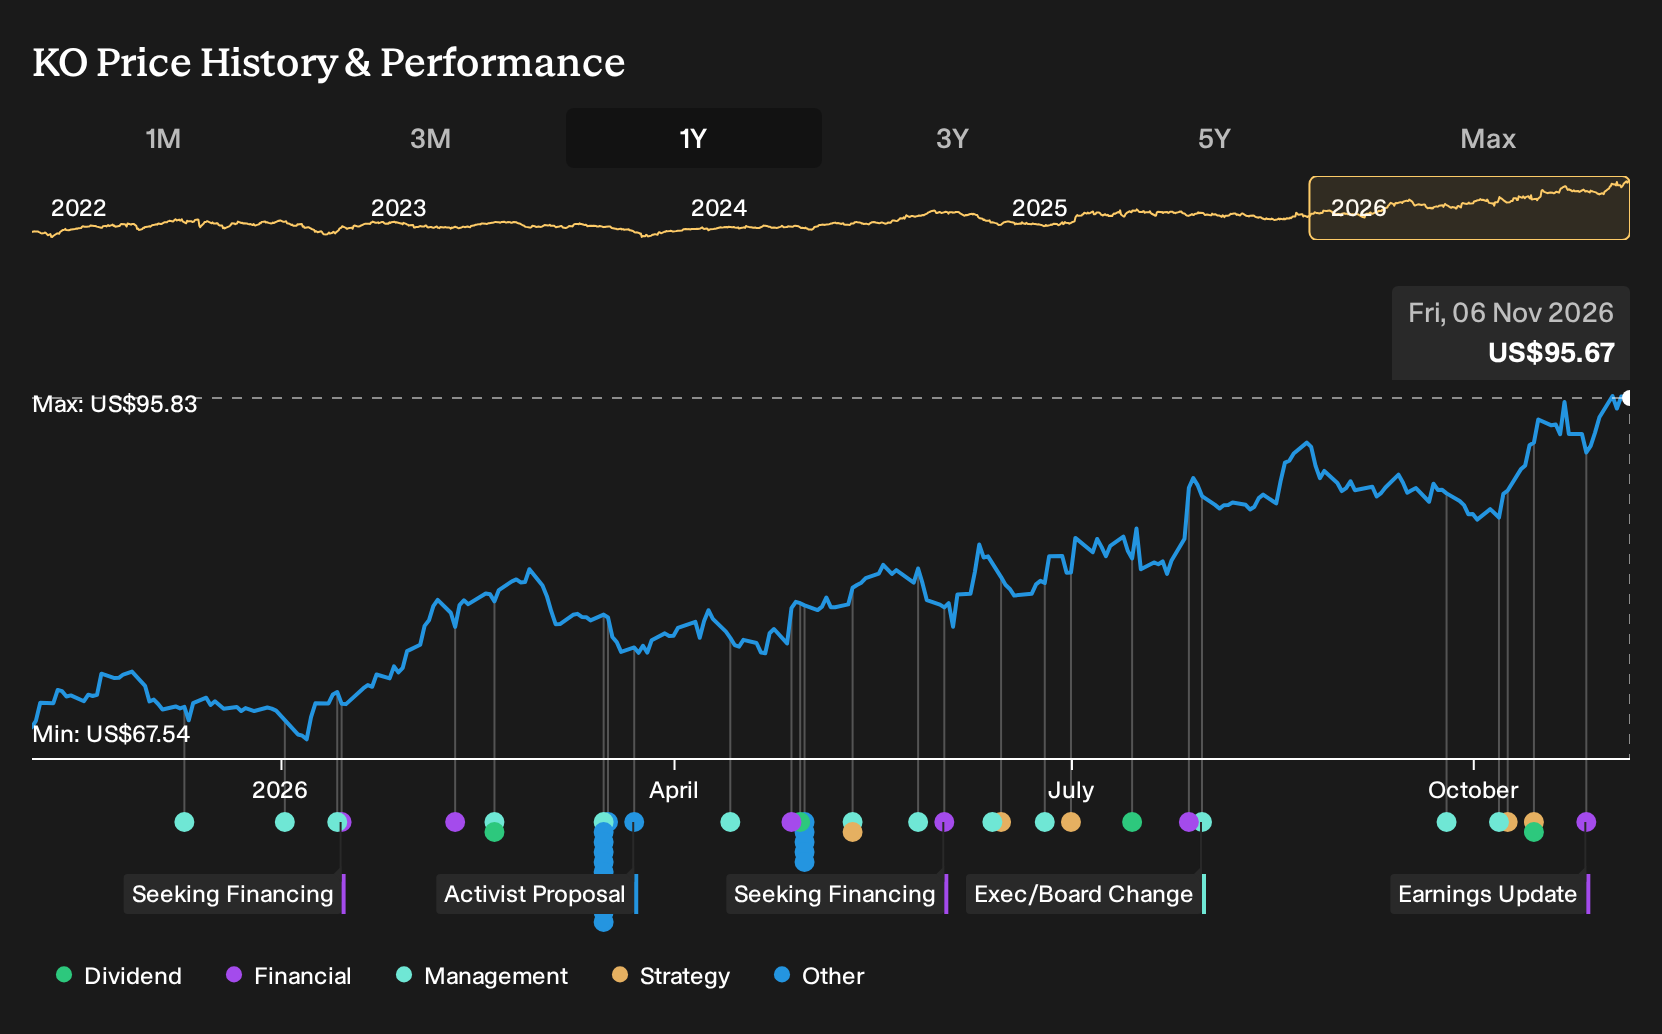
- Coca-Cola reported third quarter 2026 sales of US$13,380 million and net income of US$4,009 million, with basic EPS from continuing operations of US$0.93, and raised full year earnings and cash flow guidance after securing a major KFC U.S. beverage agreement.
- The combination of higher reported earnings, stronger free cash flow expectations and an expanded U.S. food service footprint through KFC strengthens the connection between Coca-Cola’s brand position and its ability to monetize global distribution at scale.
- This article will examine how Coca-Cola's investment narrative is influenced by stronger earnings and updated guidance following the third quarter performance update.
Coca-Cola Investment Narrative Recap
Coca-Cola appeals to shareholders who believe its global brands, distribution reach and pricing tools can keep earnings and free cash flow resilient through different consumer cycles. The latest quarter showed higher sales and net income, and management lifted full year earnings and cash flow guidance, which supports that operating thesis in the near term.
The key short term driver is execution on volume, price mix and outlet expansion, including food service, while keeping affordability in focus. The biggest current risk remains pressure on sugary drinks from health concerns and regulation. The earnings update does not remove that risk, although it shows the broader portfolio still carrying results.
The KFC U.S. beverage agreement is the most relevant recent announcement for this earnings story. It directly links Coca-Cola’s raised guidance to a larger food service footprint, adding more high traffic outlets where its drinks become the default choice for consumers and where fountain economics often support attractive profitability.
Operationally, that deal ties into the main catalysts already in play, such as revenue growth management, digital ordering across outlets and tighter focus on scalable brands. Execution risk sits around integrating this KFC volume while managing health related headwinds and potential sugar regulation, so investors will likely watch future updates on mix, margins and capital needs closely.
Coca-Cola's current analyst narrative points to forecast revenues of US$53.6b and earnings of US$16.6b by 2029. This is based on an assumed 1.7% yearly increase in revenue and a move in profit from US$14.6b today to that future level, which represents an earnings rise of about US$2.0b over the period.
Discover how Coca-Cola's fair value aligns with its current price.
Exploring Other Perspectives
Ten fair value estimates from the Simply Wall St Community cluster between US$66.20 and US$97.75, so retail views on Coca-Cola’s worth swing widely. Some members focus on catalysts like digital and AI tools or fairlife expansion; others flag sugar regulation and GLP 1 risks. Explore these contrasting viewpoints directly.
Explore 9 other Coca-Cola fair value estimates, including one that suggests as much as 31% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Coca-Cola research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Coca-Cola. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coca-Cola's overall financial health at a glance.
Looking for more investment ideas beyond Coca-Cola?
Once you have a view on Coca-Cola, it can help to compare that thesis with other opportunities that match your risk tolerance and income goals. The Simply Wall St Screener lets you filter the market down to a focused shortlist in a few clicks.
- For investors hunting for strong balance sheets and resilient fundamentals, run a search using our curated list of solid balance sheet and fundamentals (25 results) to see which companies meet those criteria.
- If income is your priority, widen your watchlist with a 7 dividend fortresses that may suit a yield focused portfolio.
- To look beyond well known giants and spot potential future leaders, sort through a 19 high quality undiscovered gems that combine quality metrics with quieter market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com