


Healthcare Realty Trust (HR) has just packed several signals into one day. Third quarter earnings showed a smaller net loss on lower revenue, while management affirmed the dividend and introduced a new US$500 million buyback authorization.
The recent 1 month share price return of 11.95% and 7 day gain of 3.84% suggest momentum has picked up into Healthcare Realty Trust’s earnings, even though the 3 month share price return declined 2.24%. This leaves the 1 year total shareholder return at 11.59% and the 3 year total shareholder return very large at around 6x.
Scan beyond Healthcare Realty Trust and compare it with a hand picked 38 high quality undervalued stocks that also pair steady balance sheets, income profiles, and potential value gaps around recent earnings and capital returns.
Healthcare Realty Trust now combines a narrower loss, an active buyback and an affirmed dividend with a share price that has already moved. The key question is whether that recent optimism still leaves room in the valuation.
Most Popular Narrative: 9% Undervalued
Against the last close of $19.20, the most followed narrative for Healthcare Realty Trust pegs fair value near $21.08, so the gap between price and that estimate has narrowed but not disappeared.
The HR 2.0 operating model, which is associated with average same store NOI growth of 5.7% over the last four quarters, rising occupancy to nearly 93% and stronger cash leasing spreads around 4.2%, points to a continuing shift toward higher internal growth that can support earnings and cash flow.
See why 6 investors see Healthcare Realty Trust as 9% undervalued.
Result: Fair Value of $21.08 (UNDERVALUED)
Still, the narrative around Healthcare Realty Trust can shift quickly if same store NOI or profit margins stall, or if future refinancing lifts interest costs and squeezes FFO.
Find out about the key risks to this Healthcare Realty Trust narrative.
Another View on Healthcare Realty Trust’s Valuation
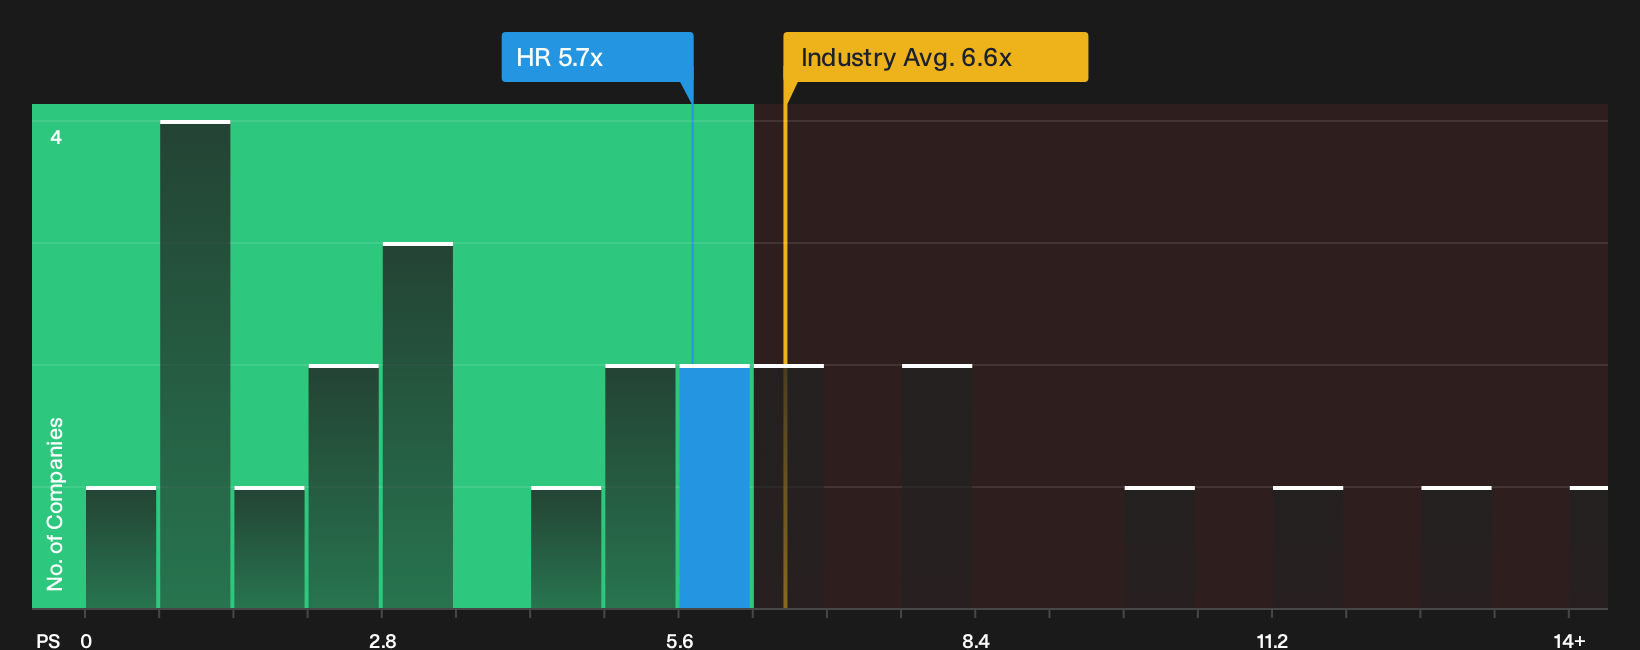
The fair value at $21.08 sits beside a different signal. The SWS fair ratio for Healthcare Realty Trust suggests its current P/S of 5.7x is expensive versus a fair ratio of 5x, even though that same P/S looks cheaper than both global health care REITs at 6.6x and peers at 6.4x.
That mix of discount versus sector and premium versus the fair ratio points to real valuation risk if expectations cool. The key question is which reference point you rely on most when you size your position.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Healthcare Realty Trust leave room for debate, so weigh the recent moves, check the data, and build your own stance using 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Healthcare Realty Trust?
If Healthcare Realty Trust has your attention, do not stop here. Use fresh stock ideas from the Simply Wall St Screener to round out your watchlist with balance and intent.
- Target potential mispricing across quality businesses by scanning the 38 high quality undervalued stocks that combine fundamentals with possible valuation gaps.
- Build a steadier income stream by reviewing 7 dividend fortresses that pair higher yields with more resilient payout profiles.
- Protect your downside first by filtering for 31 resilient stocks with low risk scores that score better on financial strength and volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com