


- M&T Bank recently updated its M&T Visa Credit Card with Rewards by increasing points on eligible grocery and gas spending, while keeping flexible redemptions and no annual fee.
- The richer grocery and gas rewards structure highlights how M&T Bank is using card economics and loyalty design to deepen everyday customer engagement.
- The focus now shifts to how M&T Bank’s enhanced grocery rewards framework could influence its broader investment narrative around fee income and loyalty.
Scan how M&T Bank’s card refresh stacks up against other financials quietly building customer loyalty engines with a 19 high quality undiscovered gems.
M&T Bank Investment Narrative Recap
M&T Bank appeals to investors who buy into a fairly simple idea. A conservatively run regional lender, with solid fee income from Wilmington Trust and other services, tries to balance steady earnings with a disciplined capital approach. The key near term swing factor is still deposit behavior and funding costs, not the credit card portfolio.
The refreshed M&T Visa Credit Card with Rewards looks incremental rather than transformative for near term results. It supports the broader push into more recurring fee income and deeper relationships, yet the biggest immediate risk remains expense pressure, especially labor, and any shift in regulatory capital that tightens scope for future buybacks.
The card upgrade is the clearest recent move that lines up with the existing catalyst list. A richer grocery and gas earn rate, combined with flexible redemptions and no annual fee, fits the relationship driven regional model and aims to keep everyday spend inside the M&T Bank ecosystem, including through its digital wallet compatible channels.
This sits alongside technology and process spending of about US$1.2b per year and a high volume of customer facing releases, pointing to a broader push to scale operations and reinforce fee streams. Execution risk stays high if rewards costs, tech investment and compensation grow faster than card and wealth revenues, which would pressure net margins.
M&T Bank's narrative projects US$11.0b revenue and US$3.2b earnings by 2029. This rests on 5.1% yearly revenue growth and an earnings increase of about US$0.3b from US$2.9b today.
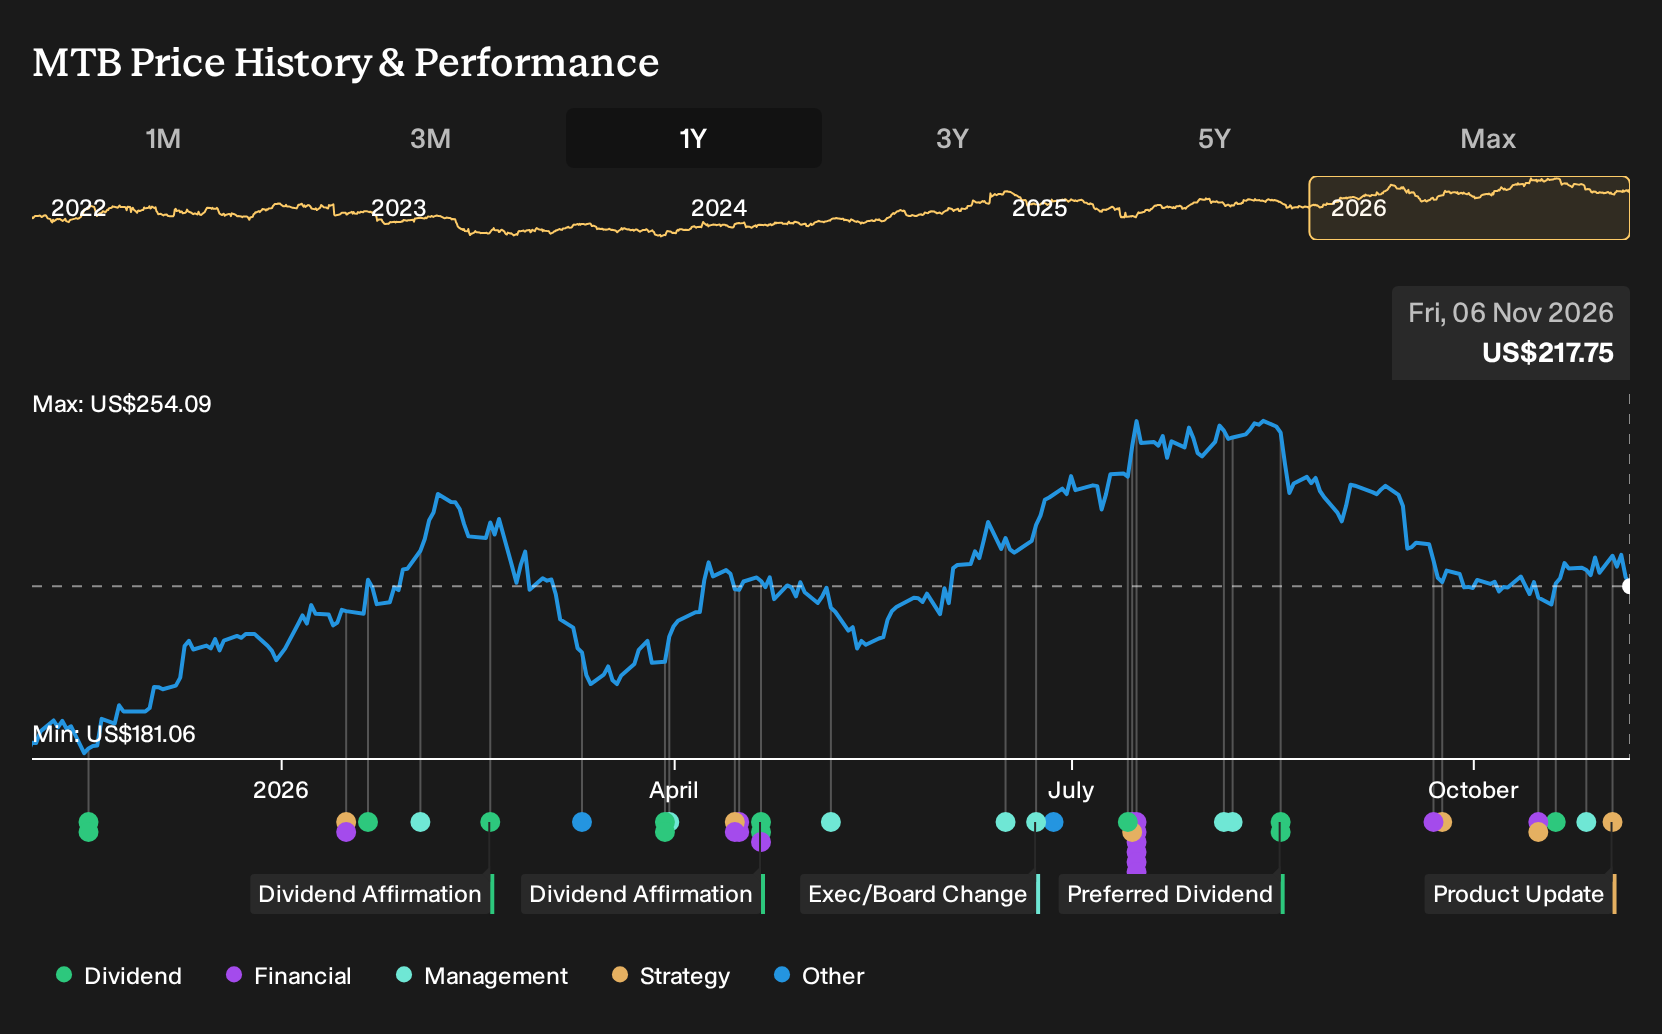
Uncover why M&T Bank's fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$246 to about US$415 per share, so private investors are clearly not singing from the same hymn sheet. Before the new rewards card and CIO appointment at M&T Bank, these views already reflected very different read throughs on fee growth, costs and capital risks. Explore those contrasts to stress test your own thesis.
Explore another M&T Bank fair value estimate, including one that suggests it could be worth just $245.93.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your M&T Bank research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for M&T Bank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate M&T Bank's overall financial health at a glance.
Looking For More Investment Ideas Beyond M&T Bank?
Once you have a view on M&T Bank, it can help to widen the lens and compare it with other opportunities that fit different risk and return preferences. The Simply Wall St Screener lets you quickly filter for businesses that match the kind of balance sheet strength, income profile or valuation style you are aiming for.
- If you want companies that already pass a basic resilience check, start with a 31 resilient stocks with low risk scores to see which businesses the data flags as steadier options.
- Income focused readers who care about cash returns today might prefer a 7 dividend fortresses and filter for stocks with yields that meet their targets.
- Those looking for underfollowed opportunities with solid fundamentals can scan a 19 high quality undiscovered gems and compare them against what you see in M&T Bank.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com