


Thales (ENXTPA:HO) has drawn fresh attention after working with HII on an end to end autonomous mine countermeasure system, integrating its modular Expeditionary Pathmaster architecture with HII’s REMUS 620 underwater vehicle.
For context, Thales shares trade at €221.70 after a 1 day share price return that declined 1.29%, and short term momentum has softened with a 7 day share price return down 5.94%. The 3 year total shareholder return of 69.27% and 5 year total shareholder return of 202.44% still point to strong longer term value creation, even as recent defence and AI related headlines, including the mine countermeasure success and the upcoming ISG AI Impact Summit appearance in Paris on 9 November 2026, have not prevented a 90 day share price return that declined 17.09% and a year to date share price return that declined 5.66%.
Scan 91 robotics and automation stocks to find other defense and autonomy focused companies that could echo Thales’ mine countermeasure and AI mission management momentum.Bulls point to Thales’ long run shareholder returns and defence pipeline, while bears highlight the recent share price slide and softer momentum. Which side does the current valuation evidence support next?
Most Popular Narrative: 24% Undervalued
Thales is framed as undervalued in the most widely followed thesis, with a fair value of €291.33 set against the recent €221.70 close. The narrative therefore leans on order momentum, margins and cash generation rather than short term share price weakness.
Thales’ capacity expansions in radars, missiles and ammunition, with multiple product lines targeted to reach about 4x to 5x prior output by 2026, position the company to convert strong defence demand and a 15% organic increase in group order intake into higher sales, better fixed cost absorption and potentially stronger net margins.
See why 108 investors see Thales as 24% undervalued.
Result: Fair Value of €291.33 (UNDERVALUED)
Still, the Thales story can crack if Cyber & Digital stumbles again or if pressure in Digital Identity & Security margins persists for longer.
Find out about the key risks to this Thales narrative.
Another View: Thales Through The P/E Lens
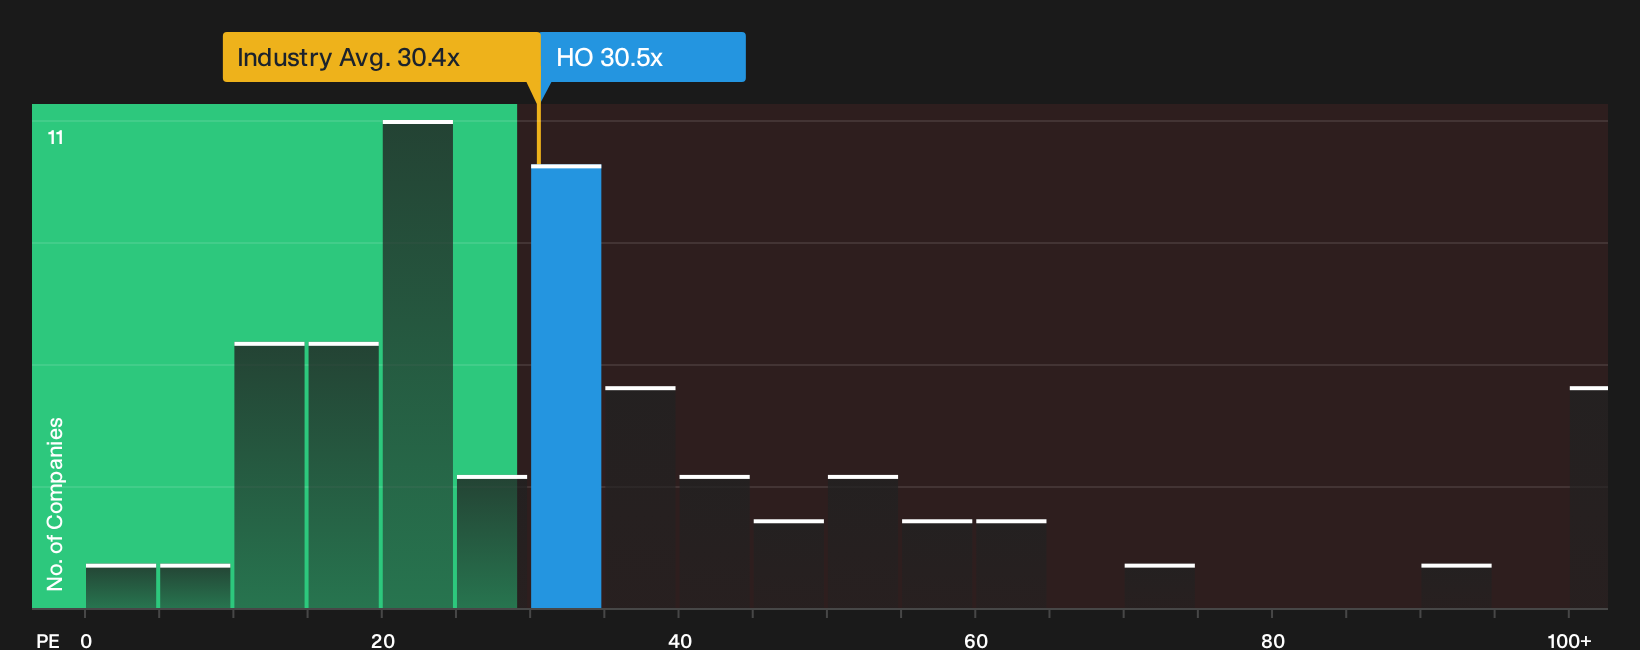
On price relative to earnings, Thales looks less generous. The stock trades on a 30.5x P/E, compared with a fair ratio of 26.8x, the European Aerospace & Defense average at 30.4x and a 27.8x peer mean. That richer multiple raises a practical question for investors: Is the DCF upside worth paying above these reference points?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Signals on Thales appear mixed so far. If you want to move quickly and build your own conviction, consider weighing both sides of the story through 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Thales?
Do not stop with Thales. Fresh opportunities sit just a few clicks away, and skipping them could mean missing the next holding that truly fits your plan.
- Target resilient returns by focusing on stability and consistency through 208 resilient stocks with low risk scores.
- Hunt for quality at a sensible entry price by scanning the market for 226 high quality undervalued stocks.
- Build a watchlist of durable businesses with healthy finances using the list of solid balance sheet and fundamentals (193 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com