


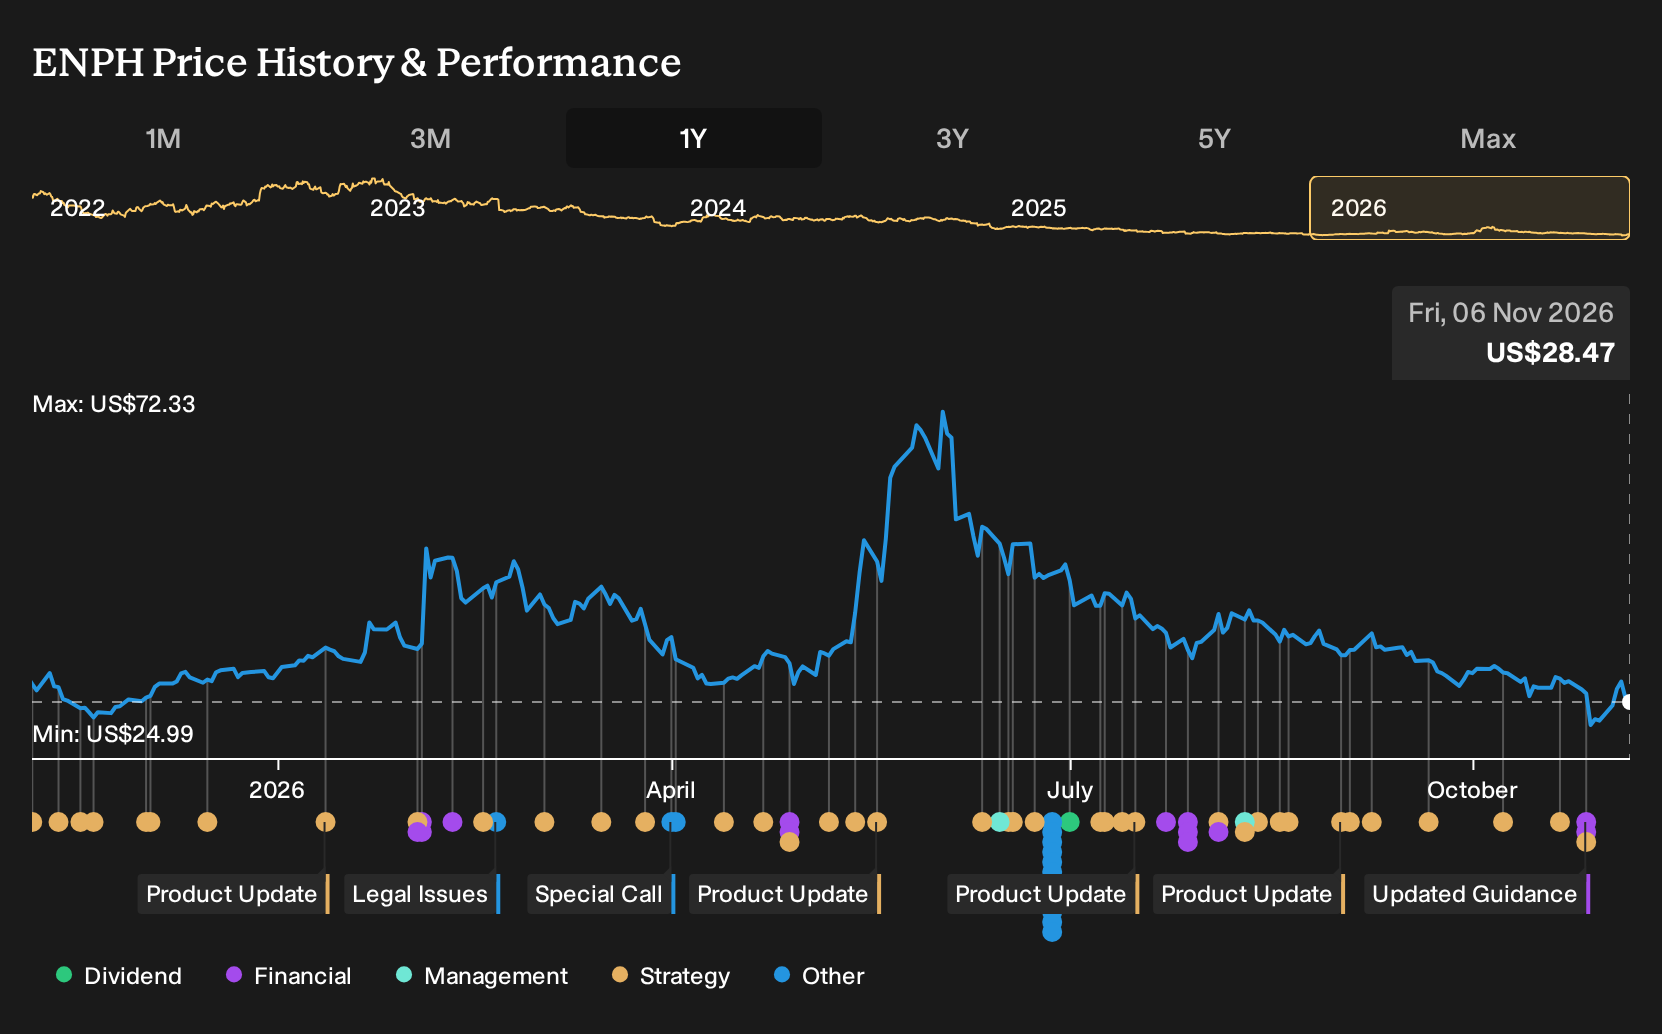
- Enphase Energy reported third quarter 2026 basic earnings per share from continuing operations of US$0.18, down from US$0.51 a year earlier. The company issued fourth quarter revenue guidance of US$225 million to US$255 million and outlined safe harbor revenue of about US$51.2 million.
- The IQ Solid-State Transformer milestone, converting 13.8 kV AC directly to 800 VDC for AI data center loads, indicates that Enphase Energy is testing a pathway into medium voltage, megawatt scale infrastructure that sits well beyond its traditional residential solar and storage base.
- We will look at how Enphase Energy's investment narrative is shaped by weaker EPS alongside the IQ Solid-State Transformer data center milestone.
Compare Enphase Energy's data center pivot with hand picked AI infrastructure peers by scanning the 53 AI infrastructure stocks now shaping how power reaches compute heavy workloads.
Enphase Energy Investment Narrative Recap
To own Enphase Energy today, you need to believe that weaker earnings per share in 2026 are a reset phase, not a permanent reset of the business. The short-term hinge is whether management can stabilize margins while residential solar demand in the U.S. and Europe remains under pressure and legal questions in Europe hang over sentiment.
The biggest risk is that pricing cuts, tariffs, and smaller residential markets keep compressing profitability even if volumes hold steady. The latest quarter, with basic EPS from continuing operations at US$0.18 versus US$0.51 a year earlier, feeds directly into that concern and keeps execution on costs and mix in the spotlight.
Among the latest announcements, the IQ Solid-State Transformer progress is the clearest operational swing factor linked to this earnings update. Enphase Energy is showing lab-scale conversion of 13.8 kV AC to 800 VDC for AI workloads, which points to potential exposure to medium-voltage infrastructure that is very different from rooftop solar hardware.
This program does not fix near-term pressure on residential demand or gross margins, but it does frame a possible second act if pilots and megawatt-scale racks proceed as planned. For investors, the question is whether the current earnings softness can be managed long enough for IQ SST and other new platforms to matter for revenue mix and risk profile.
What The Enphase Energy Forecasts Assume
Enphase Energy's current analyst narrative points to forecast revenue of US$1.3b and projected earnings of US$193.9 million by 2029. That outlook is built on revenue growing by 1.9% a year and an earnings increase of about US$103 million from US$90.8 million today.
Uncover why Enphase Energy's fair value indicates a 43% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on the risk that Enphase Energy’s IQ Solid-State Transformer and broader AI power initiatives arrive too slowly to offset weak residential demand. The most pessimistic analysts were modeling revenue of about US$1.1b and earnings of roughly US$121.6 million by 2029, well below consensus, so their outlook is far more cautious. Those estimates were set before this earnings and IQ SST update, so you should expect opinions to shift and examine how that bearish path compares with your own expectations.
Explore 5 other Enphase Energy fair value estimates, including one that suggests as much as 34% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own research.
- A great starting point for your Enphase Energy research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Enphase Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enphase Energy's overall financial health at a glance.
Looking For More Ideas Beyond Enphase Energy?
If the Enphase Energy story has you thinking about portfolio balance and fresh opportunities, it can help to line it up against other companies with different risk and income profiles. The Simply Wall St Screener lets you quickly scan for stocks that fit the kind of return potential and resilience you want, rather than just following the latest headline.
- For investors who want potential upside with some quality checks in place, review a curated set of 19 high quality undiscovered gems that combine strong fundamentals with less crowd attention.
- If capital preservation and smoother return profiles matter most to you, filter for 31 resilient stocks with low risk scores that score well on balance sheet strength and volatility.
- Income focused readers can zero in on steady cash payouts by screening for 7 dividend fortresses that aim to pair yield with durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com