


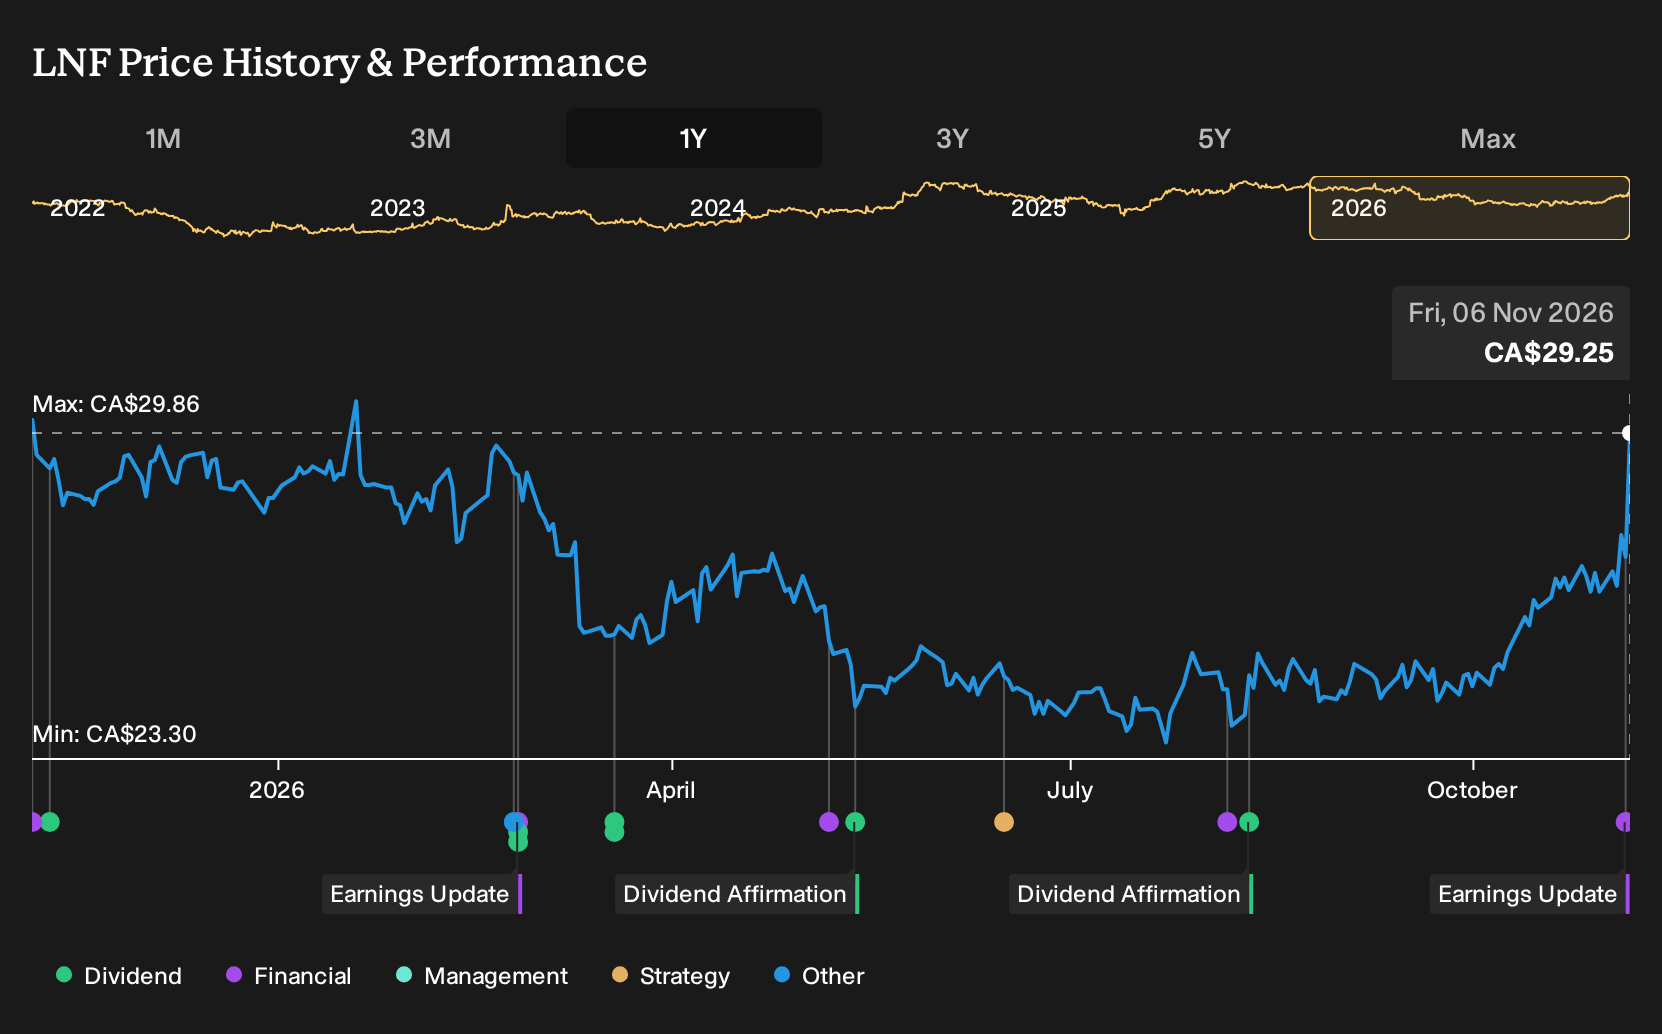
- Leon's Furniture reported third quarter 2026 results with sales of C$672.79 million, slightly lower than a year earlier, while net income edged up to C$50.91 million and earnings per share from continuing operations held broadly steady.
- Behind the headline numbers, furniture sales faced softer demand and inventory delays, while appliances and mattresses grew. A one-time gain from selling a former property supported earnings as management prepared new franchise openings and a heavier Black Friday push.
- We will look at how Leon's Furniture's investment narrative holds up given softer furniture demand but resilient earnings helped by asset gains.
Scan beyond Leon's Furniture and focus on other retailers and consumer stocks that pair steady balance sheets with earnings resilience using our curated list of solid balance sheet and fundamentals (5 results)
Leon's Furniture Investment Narrative Recap
For Leon's Furniture, the core belief is that a Canadian focused furniture, appliance and mattress retailer can keep earnings resilient even when big ticket demand feels tight. The recent quarter fits that view. Sales softened slightly, but net income held close to last year, helped by appliances, mattresses and a property sale gain.
The main short term swing factor is how well Leon's Furniture converts its aggressive Black Friday and holiday assortment into traffic, despite ongoing shipping delays. The biggest risk is that furniture demand and supply chain issues combine to mute same store sales. On current information, the earnings impact looks contained rather than structural.
The most relevant update here is the C$12.5 million gain on the former Edmonton property sale that fed into adjusted net income. That kind of non operating boost supports the third quarter headline profit, but it does not change the underlying demand picture that investors are trying to assess.
For catalysts, attention sits more on the planned two franchise openings in the fourth quarter and the heavier Black Friday push. New locations and holiday execution test whether Leon's Furniture can offset softer furniture trends with better assortment, marketing and category mix. If inventory delays persist into the peak season, that same plan becomes the clearest operational risk.
Leon's Furniture's current earnings are CA$157.9 million, and analysts expect earnings of CA$153.4 million by 2029, which implies an earnings decline of about CA$4.5 million. On those assumptions, revenue is projected to rise by 2.2% per year and reach CA$2.7 billion by 2029, so the investment story combines modest top line growth with slightly lower profit per dollar of sales.
Uncover why Leon's Furniture's fair value indicates a 14% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view leans heavily on Leon's Furniture using its real estate and liquidity as the real catalyst. Bullish analysts were modelling revenue of about C$2.7b and earnings near C$160.3 million by 2029 before this quarter, which is more optimistic than consensus. The latest earnings update may prompt both camps to revisit those paths.
Explore 4 other Leon's Furniture fair value estimates, including one that suggests as much as 67% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis.
- A great starting point for your Leon's Furniture research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Leon's Furniture. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Leon's Furniture's overall financial health at a glance.
Looking for more investment ideas beyond Leon's Furniture?
Once you have formed a view on Leon's Furniture, it can help to compare that thesis with other businesses that share traits you care about, whether that is value, income or resilience in tougher conditions.
- For investors who want potential bargains backed by fundamentals, start with a carefully filtered set of 7 high quality undervalued stocks that pair quality with pricing that still looks reasonable.
- If steady income is a priority, zero in on companies that combine robust cash generation with higher yields by reviewing our curated 3 dividend fortresses.
- When capital preservation matters most, focus on businesses with relatively low risk profiles and sturdy finances through our 9 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com