


- Paychex drew fresh attention after a hotter than expected U.S. jobs report highlighted how a firm labor market can affect payroll processing, HR-tech adoption, and outsourcing demand across small and mid sized employers.
- The renewed focus on employment data puts Paychex's mix of higher value PEO and advisory services, along with its AI driven tools, under closer scrutiny as businesses manage complex hiring and compliance needs.
- We will now explore how Paychex's investment narrative could be shaped by this stronger labor backdrop and renewed payroll focus.
Scan how payroll and HR-tech momentum could spread beyond Paychex by reviewing hand picked list of solid balance sheet and fundamentals (25 results) aligned with a firm labor market and demand for resilient service providers.
Paychex Investment Narrative Recap
To own Paychex, you need to be comfortable with a business that leans on a solid base of payroll and HR outsourcing, then layers on higher value PEO, insurance, and AI enabled services. The hotter jobs report points attention to employment sensitive fee volumes, but the bigger near term swing factor still looks like execution on Paycor integration and the WISE AI rollout.
The main operational risk right now is that slower growth in Management Solutions, integration complexity with Paycor, and a projected drop in interest on funds held for clients in FY27 could squeeze overall revenue growth and margins. The latest labor data adds context, yet it does not fundamentally change those core issues.
With no fresh company announcements tied directly to this jobs report, the most relevant recent talking point remains Paychex's WISE AI engine and automation efforts. Management has cited roughly 20% lower manual payroll processing and prevention of about 90% of top payroll errors in a large pilot, which matters when volumes stay firm.
For you as an investor, the question is whether Paychex can extend those AI driven efficiency gains while continuing to move more clients into higher revenue PEO offerings and deeper Paycor cross sell. That mix shift, plus new services like Perks and SixFifty, sits on one side of the scale, with interest income pressure and execution risk on the other.
Paychex's narrative projects US$7.7b revenue and US$2.4b earnings by 2029. That profile lines up with analysts who assume 5.2% yearly revenue growth and an earnings increase of about US$600m from US$1.8b today.
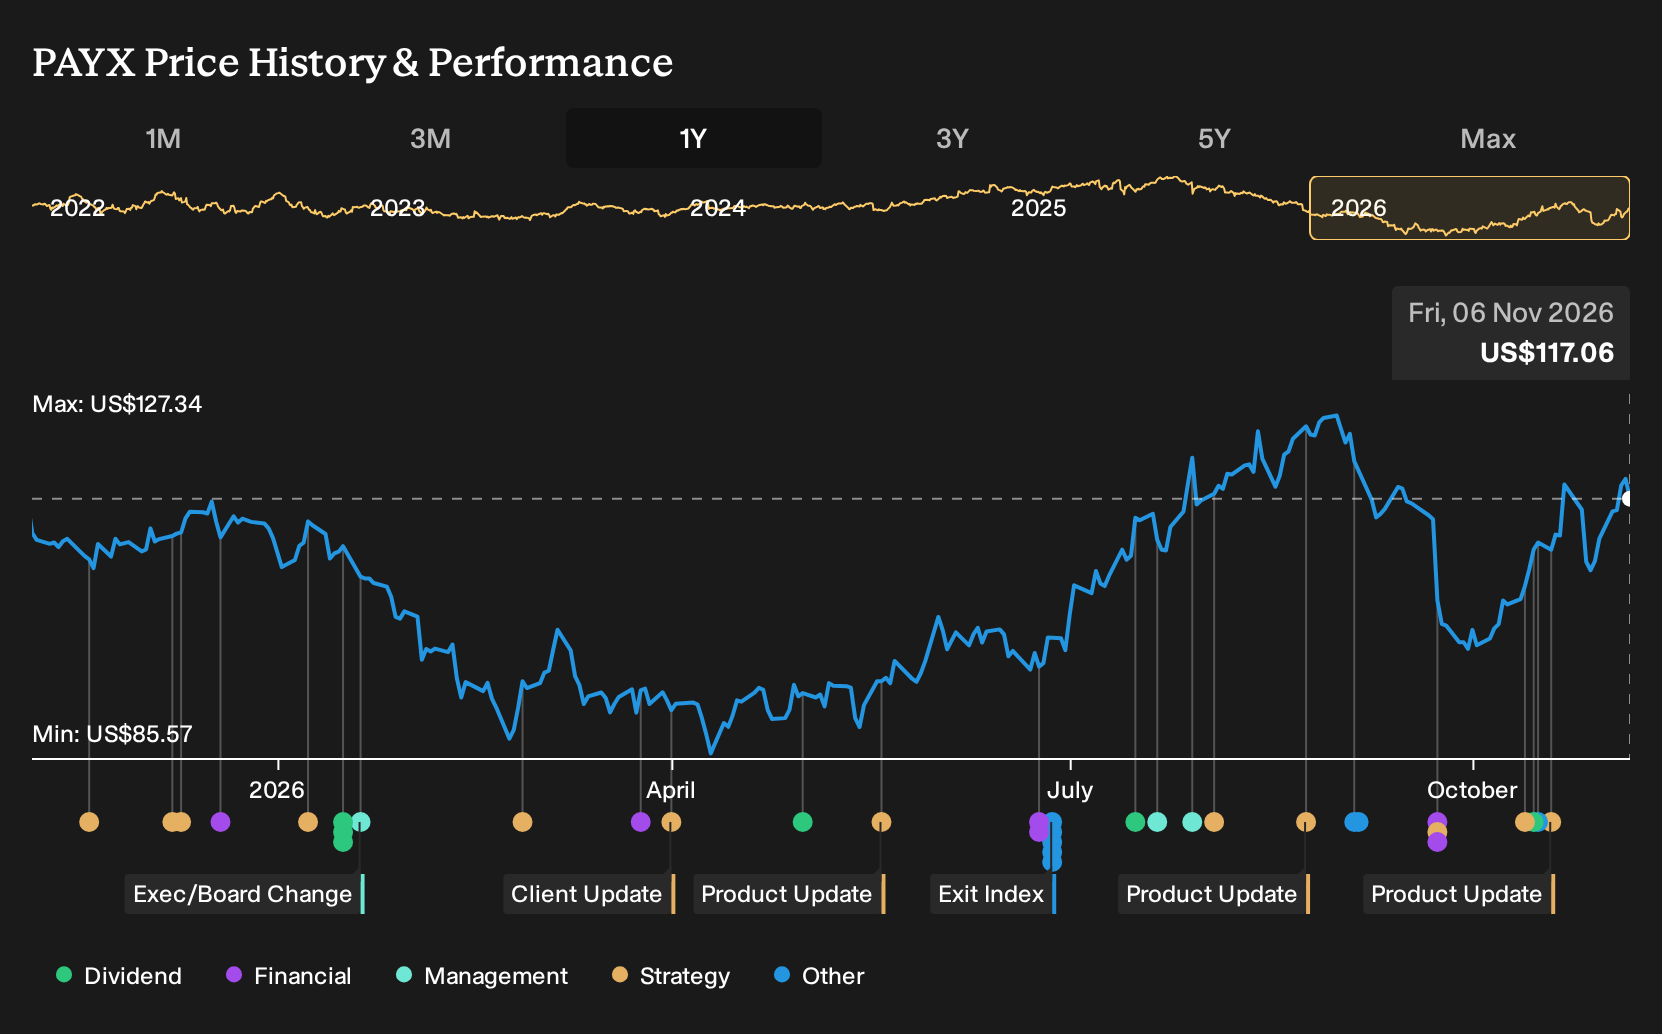
Uncover why Paychex's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate angle on Paychex focuses on volume risk. The most cautious analysts worry that relatively flat employment and slower hiring could keep pays per control subdued, even after a hotter jobs report. They were only modeling about US$7.6b revenue and US$2.3b earnings by 2029, which reflects a meaningfully more pessimistic narrative that may shift as new labor data filters through.
Explore 3 other Paychex fair value estimates, including one that suggests it could be worth just $113.93.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Paychex research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Paychex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Paychex's overall financial health at a glance.
Looking for more Paychex sized investment ideas?
Once you have formed a view on Paychex, it can help to cross check that thinking against other companies with different risk and income profiles using the Simply Wall St Screener.
- If you want resilience to be the priority, scan a 31 resilient stocks with low risk scores that screen strongly on balance sheet strength and lower risk scores.
- If income is the focus, compare Paychex with a hand picked pool of 7 dividend fortresses that aim to pair yield with stability.
- If you are hunting for opportunities that the crowd may be ignoring, sift through 19 high quality undiscovered gems that combine solid fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com