


Lakeland Financial’s Q3 trigger event
Lakeland Financial (LKFN) drew fresh attention after third quarter 2026 results combined higher net interest income and net income with a sharp rise in net charge offs tied to one nonperforming commercial credit.
Lakeland Financial’s share price has risen 7.58% over the past month and 8.31% year to date, while a 9.35% total shareholder return over the last year and 31.63% total shareholder return across three years point to moderate but persistent momentum despite the latest credit event.
Compare Lakeland Financial’s mix of earnings strength and credit risk with hand picked regional banks by scanning the 31 resilient stocks with low risk scores that focus on resilient balance sheets and controlled loan losses.
Bulls see Lakeland Financial’s recent earnings strength as the real story. Bears point to the credit hit and worry it is a warning. Which argument does current pricing support as you weigh what you are paying for those profits?
Preferred P/E of 13.3x for Lakeland Financial: Is it justified?
Lakeland Financial trades at a P/E of 13.3x against a last close of $61.15. This points to a richer earnings tag than many US banks and sets a higher bar for what those profits need to deliver.
The P/E ratio compares what you pay for each dollar of earnings, so for a regional lender like Lakeland Financial it gives a quick read on how the market is pricing its profit stream relative to other financial institutions.
A 13.3x P/E leaves investors paying more than both the US Banks industry average of 11.3x and an estimated fair P/E of 10.7x. This signals the market is attaching a premium to Lakeland Financial’s earnings that could compress if sentiment or performance shifts back toward sector norms.
That premium is also above the fair P/E level that regression analysis suggests the shares could trend toward over time. This reinforces how strongly current pricing leans away from that modeled fair ratio.
Explore the SWS fair ratio for Lakeland Financial.
Result: Price-to-earnings of 13.3x (OVERVALUED).
Still, a richer P/E can come under pressure if Lakeland Financial sees further credit issues or if loan growth and fee income soften against expectations.
Find out about the key risks to this Lakeland Financial narrative.
Another view on Lakeland Financial’s value
The earnings multiple makes Lakeland Financial look expensive, yet the SWS DCF model points the other way. At a share price of $61.15, the stock is assessed as trading around 39.8% below an estimated future cash flow value of $101.57. Which lens do you trust more for long term decisions?
Look into how the SWS DCF model arrives at its fair value.
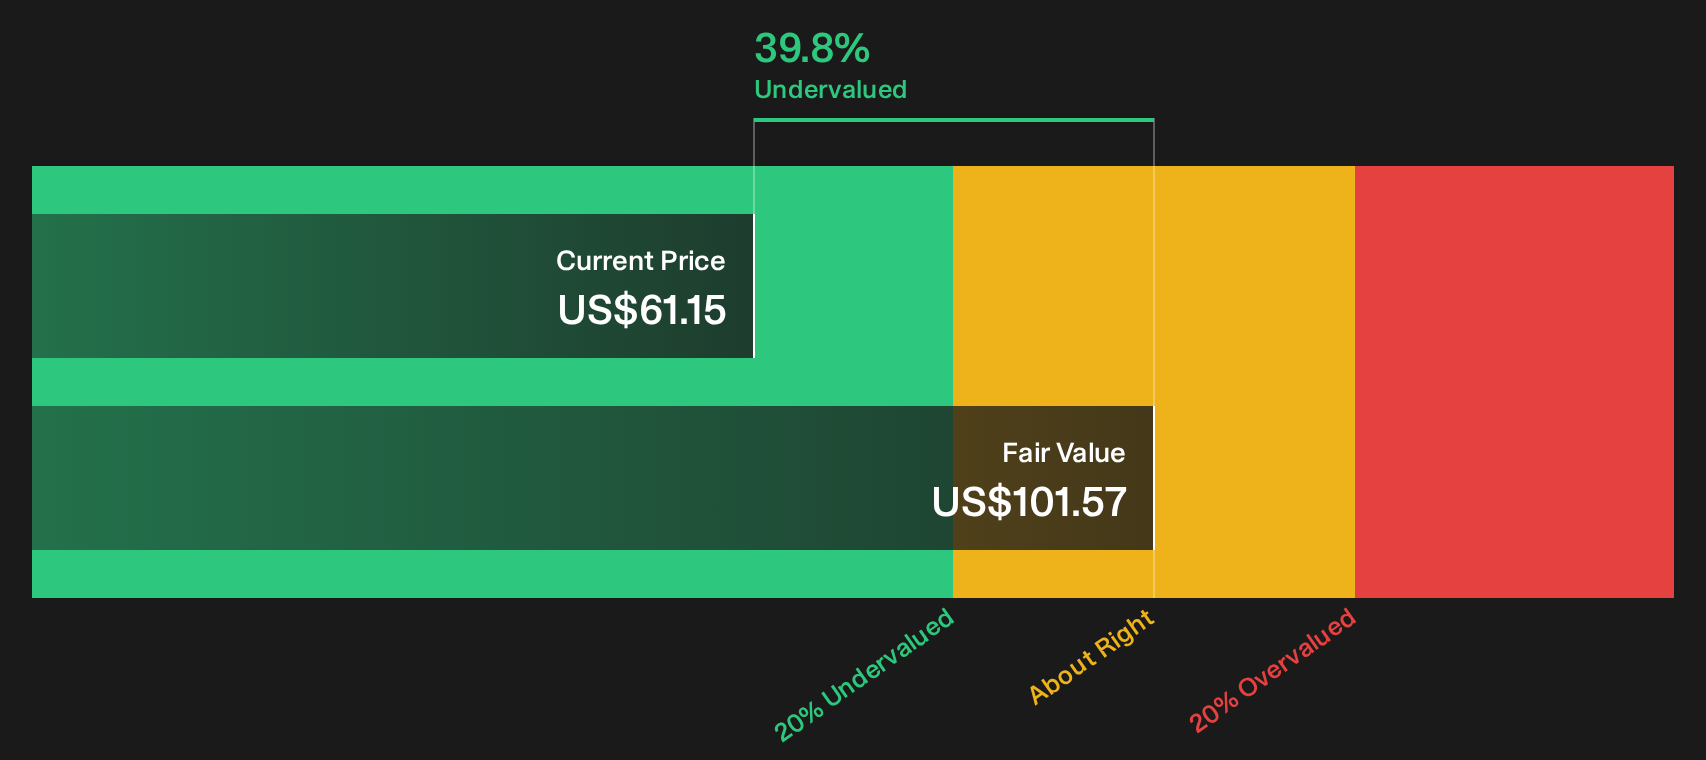
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Lakeland Financial for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 38 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Lakeland Financial’s valuation and credit risk create a split verdict, so consider acting promptly, review the numbers yourself, and weigh both sides using 3 key rewards and 1 important warning sign.
Looking for more Lakeland Financial sized opportunities?
Do not stop at Lakeland Financial. Use the Simply Wall St screener to surface fresh ideas with different risk, income, and value profiles that could fit your goals.
- Target steadier capital and fewer nasty surprises by focusing on resilient businesses through the 31 resilient stocks with low risk scores.
- Hunt for mispriced opportunities where quality and valuation line up using the 38 high quality undervalued stocks.
- Build a portfolio that pays you while you wait by scanning income focused ideas in the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com