


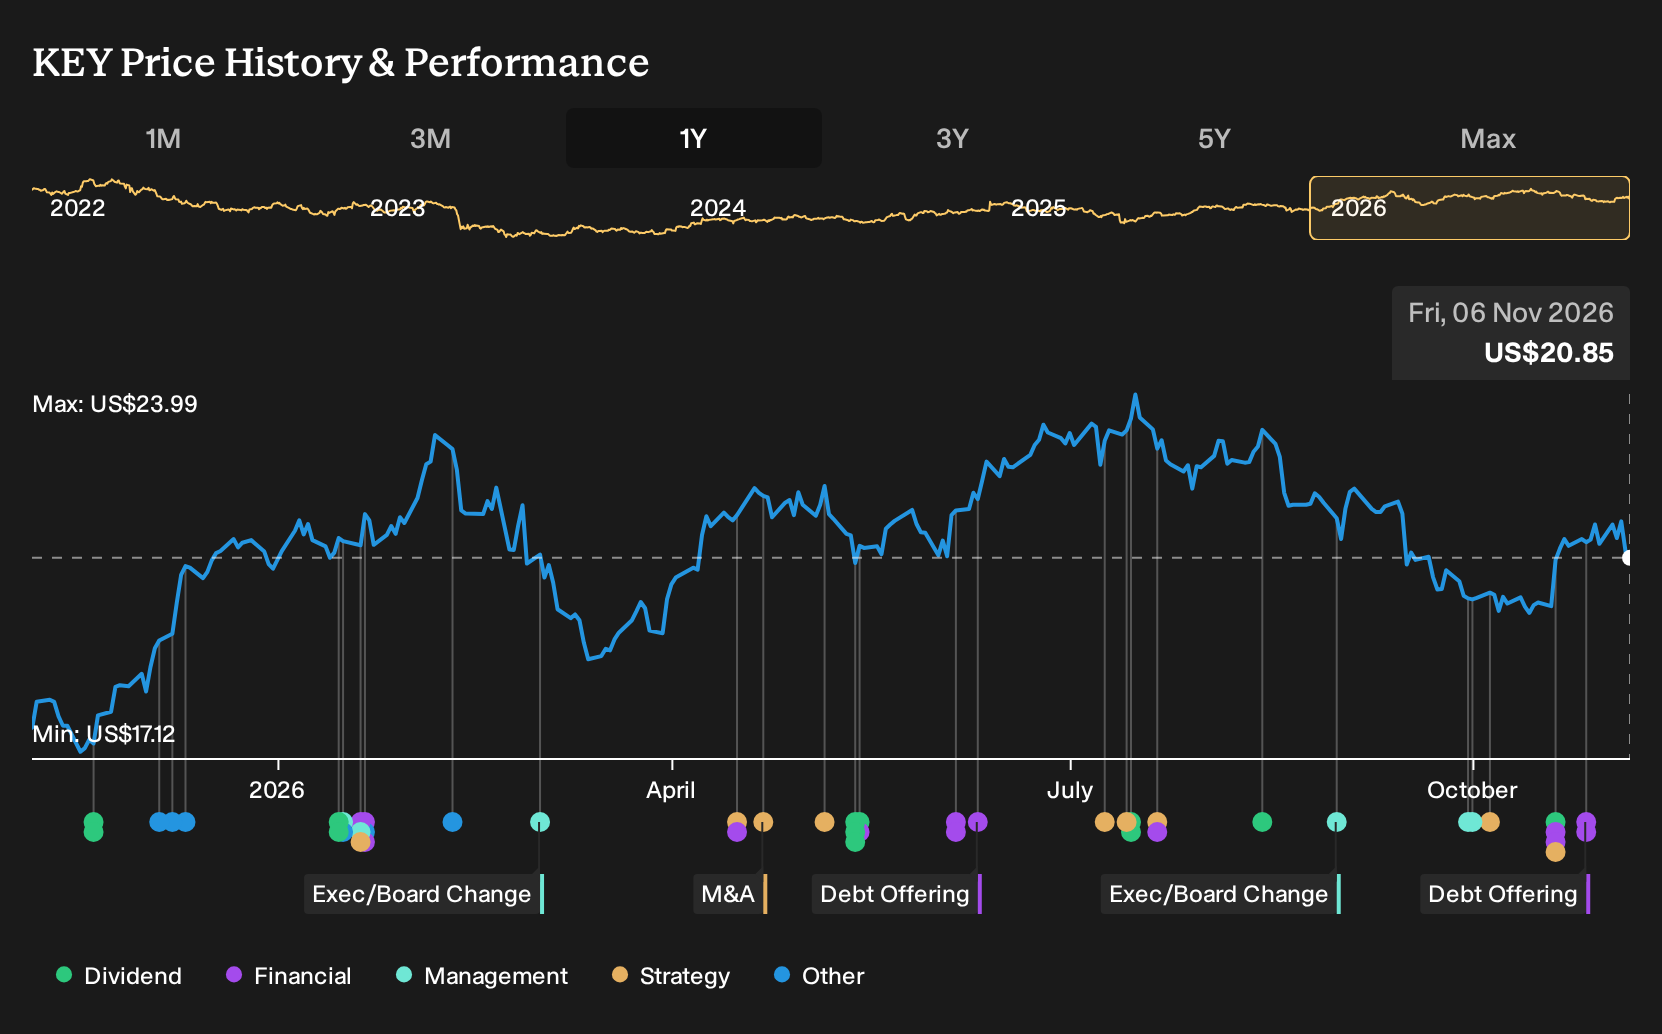
- KeyCorp recently completed a US$1b offering of senior unsecured fixed to floating rate notes due November 2, 2032. The notes were issued at 100%, include a 0.35% discount per security, and feature callable, variable rate terms.
- This shift toward callable, variable rate funding adds another lever for KeyCorp to manage interest expense, balance sheet flexibility, and future refinancing choices under changing rate conditions.
- We will now look at how KeyCorp's investment narrative could be influenced by this US$1b variable rate debt issuance.
See how KeyCorp's funding shift compares with a curated group of banks and financial stocks designed to handle rate changes by checking the 31 resilient stocks with low risk scores
KeyCorp Investment Narrative Recap
To own KeyCorp, you need to be comfortable with a story built on repricing low yielding assets, managing deposit costs, and growing fee based lines like payments, advisory, and wealth. The new US$1b fixed to floating notes matter mainly as another funding tool rather than a shift in the operating playbook. The nearer term swing factor still looks like how net interest margin and fee momentum evolve.
The biggest near term risk remains credit. Nonperforming assets at 74 bp of loans in Q2 2026, tied to real estate, consumer goods, and agriculture, show that stress pockets can still appear. If those issues broaden, higher credit costs could offset benefits from better funding mix and any improvement in core earnings power.
The completed US$1b fixed to floating rate notes due November 2, 2032, with a 0.35% discount and a callable, variable coupon, are the clearest near term operational lever linked to the funding story. This issuance reshapes a slice of KeyCorp’s liability stack toward instruments that can reset with rates rather than locking in a single fixed cost.
For you as a shareholder, the relevance is in how that interacts with the planned shift from net interest income headwinds to tailwinds and the goal of a higher net interest margin. The more effectively KeyCorp balances this new variable rate debt against asset repricing and deposit costs, the more room it has to support earnings while still managing credit and capital return plans.
KeyCorp Forecasts Behind the Funding Story
KeyCorp's projected path ties the funding shift to a broader earnings and revenue framework rather than leaving the new US$1b variable notes in isolation. Analysts currently assume revenue will grow by 8.9% a year over the next 3 years, with earnings today at about US$1.9b and consensus profit expected to reach US$2.5b by 2029. On those figures, the business would be running on US$9.5b of revenue and US$2.5b of earnings in 2029, with profit margins edging from 25.6% to 26.6% if the forecast plays out.
KeyCorp's narrative projects US$9.5b revenue and US$2.5b earnings by 2029. This rests on 8.9% yearly revenue growth and an earnings increase of roughly US$0.6b from US$1.9b today.
Uncover why KeyCorp's fair value indicates a 22% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on one big swing factor for KeyCorp. They see the fixed rate book repricing faster and cleaner than consensus, which helps their pre news forecasts of about US$9.8b revenue and US$2.8b earnings by 2029. You may view this new variable funding and the upcoming Boston conference as reasons those projections could shift, so it can be useful to compare both the cautious and bullish cases side by side.
Explore 2 other KeyCorp fair value estimates, including one that suggests potential upside of up to 61% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your KeyCorp research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for KeyCorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KeyCorp's overall financial health at a glance.
Looking for more investment ideas beyond KeyCorp?
If you want to stress test the KeyCorp thesis against other opportunities, the Simply Wall St Screener can help you line up candidates with very different strengths, then filter by the factors that matter most to you.
- If resilience is your priority, compare KeyCorp with a wider group of companies that score well on financial robustness by scanning a list of solid balance sheet and fundamentals (25 results)
- If value is your main filter, line up potential alternatives to KeyCorp using a 38 high quality undervalued stocks that marry quality fundamentals with pricing that may look appealing.
- If income is front and center for your portfolio, contrast KeyCorp with a 7 dividend fortresses that focus on higher-yielding payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com