


Mettler-Toledo International (MTD) has just put fresh numbers on the table, with Q3 2026 earnings and a higher full-year outlook that immediately reframed how the market is thinking about the stock.
The raised outlook has arrived alongside strong price momentum, with Mettler-Toledo International’s 30-day share price return of 11.11% and 90-day share price return of 20.64% helping lift the stock to US$1,722.15. The 3-year total shareholder return of 64.94% points to a longer run of gains that recent earnings and guidance have simply brought back into focus.
Spot similar earnings-driven momentum by scanning our hand picked list of 19 high quality undiscovered gems, which, like Mettler-Toledo International after Q3 2026, are reshaping expectations with fresh guidance and stronger results.Mettler-Toledo International now trades above both analyst targets and an intrinsic value estimate that screens lower, which leaves a simple tension: Is the premium just caution being ignored or hard to justify?
Price-to-Earnings of 36.7x: Is it justified?
Mettler-Toledo International now trades on a P/E of 36.7x, which puts a clear premium on the $1,722.15 share price compared with peers and a lower implied fair P/E of 24x.
The P/E ratio compares the current share price to earnings per share and gives a quick read on how much investors are willing to pay for each dollar of profit. For a business like Mettler-Toledo International, with high quality earnings and consistent profitability, this yardstick often reflects how much faith the market has in future cash generation rather than just the most recent quarter.
Here the market is paying more than the estimated fair P/E of 24x. This suggests investors are assigning a richer valuation than the level the fair ratio points toward. That richer tag also sits slightly above the Global Life Sciences industry average of 35.6x and a peer average of 36.5x. This reinforces that Mettler-Toledo International is priced at the expensive end of the sector range rather than being a discount story.
Explore the SWS fair ratio for Mettler-Toledo International.
Result: Preferred multiple of 36.7x P/E (OVERVALUED)
Still, the premium story can unravel quickly if demand in key end markets softens, or if Mettler-Toledo International’s recent earnings strength proves hard to repeat.
Find out about the key risks to this Mettler-Toledo International narrative.
Another View on Mettler-Toledo International’s Value
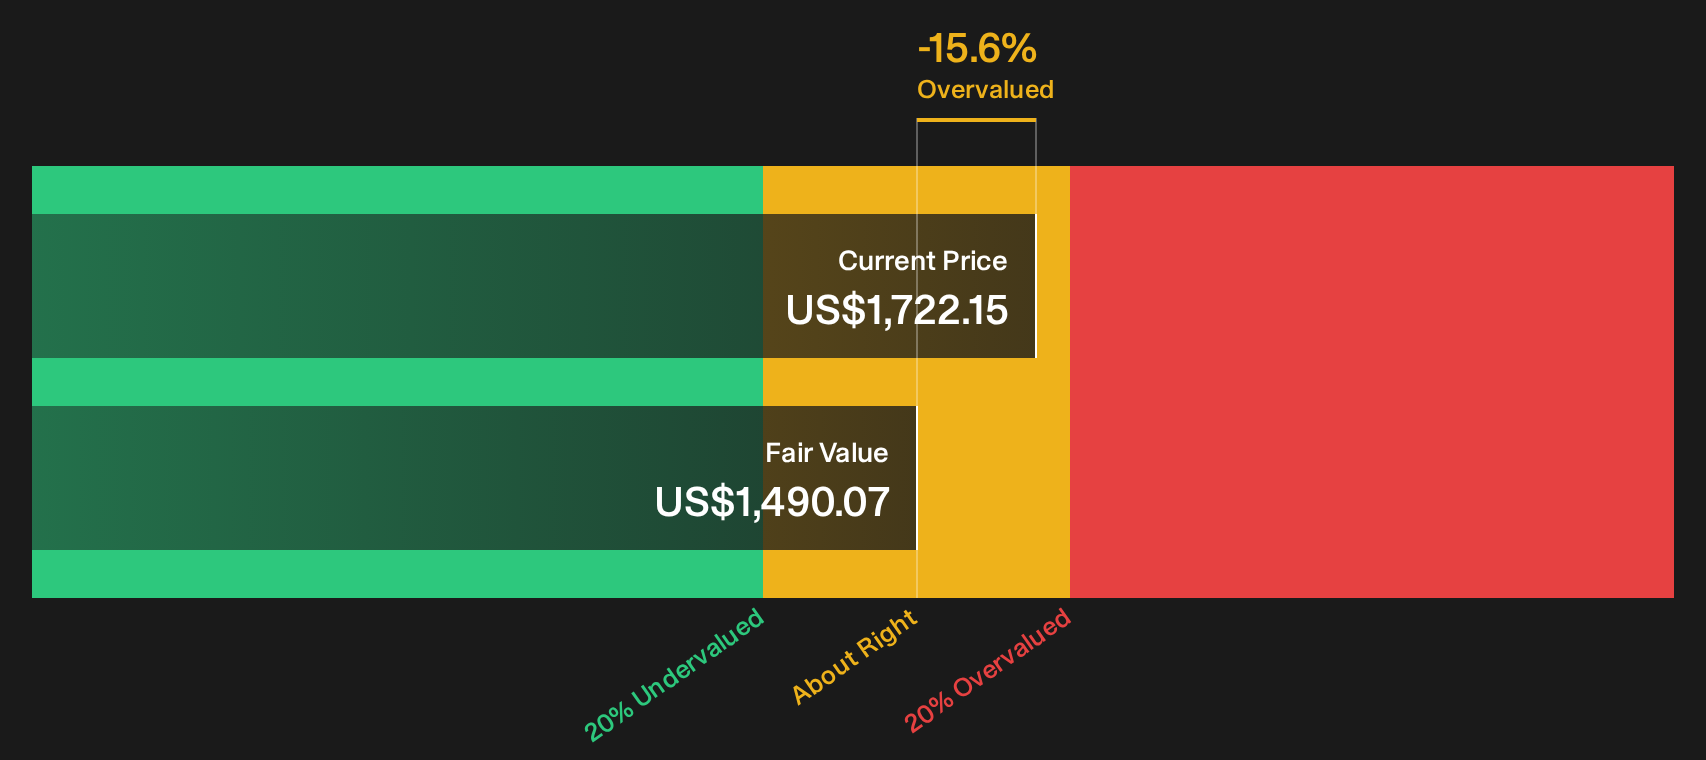
One model says Mettler-Toledo International is priced richly. A second lens tells a similar story. The SWS DCF model estimates future cash flows at $1,490.07 per share, which sits below the current $1,722.15 level and flags the stock as overvalued on this method too.
That gap points to limited room for error. If growth or margins come in below expectations, the share price may have more to adjust than the fair value line suggests. The real question is how much conviction you have in the current earnings path.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mettler-Toledo International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 38 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on valuation or just a sharp repricing after strong Q3 2026 numbers, either way the next step is to interrogate the data yourself and decide how comfortable you are with Mettler-Toledo International’s risk and reward balance given where the stock trades today. To pressure test both sides of the story, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Mettler-Toledo International?
If Mettler-Toledo International has sharpened your focus on valuation and quality, do not stop here. Other opportunities may fit your portfolio even better.
- Target potential mispricings by scanning companies that screen as high quality yet priced below fair value through the 38 high quality undervalued stocks.
- Explore income ideas in the 7 dividend fortresses that combine higher yields with businesses that have established operations.
- Seek to reduce portfolio risk by reviewing companies with stronger finances and cleaner fundamentals using the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com