


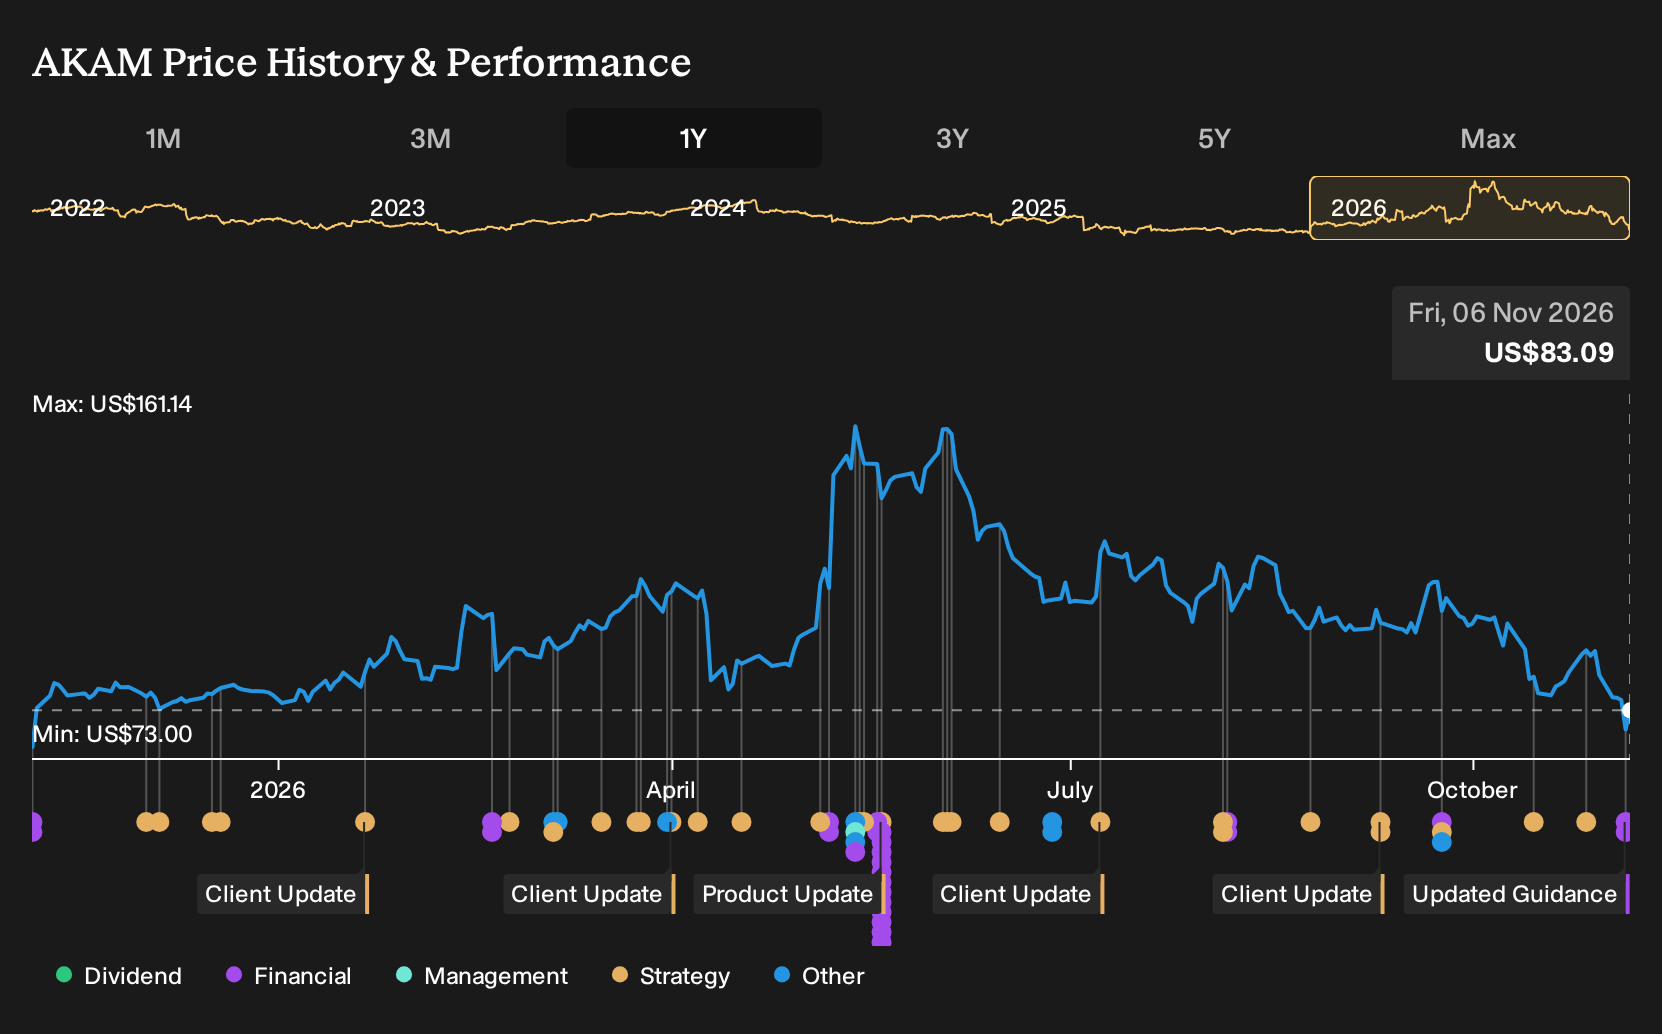
- Akamai Technologies reported third quarter 2026 sales of US$1.12b with lower net income year on year and issued multi year revenue guidance that includes projected total revenue above US$7b in 2028.
- The launch of Akamai Inference and Agent Sandbox, backed by expanded NVIDIA GPU clusters and a planned US$5.5b AI infrastructure build out, signals a heavier tilt toward AI focused cloud services and long duration workloads.
- We will now explore how Akamai Technologies' long range revenue guidance tied to AI infrastructure could reshape its broader investment narrative.
Scan how other AI infrastructure players with similar long-term build outs are priced by checking the hand picked 53 AI infrastructure stocks alongside Akamai Technologies' latest pivot.
Akamai Technologies Investment Narrative Recap
To own Akamai Technologies, you need to believe that security and cloud infrastructure can more than offset pressure in the legacy delivery business. The new guidance points to a company leaning into that view, with management laying out a revenue path through 2028 while near term profits feel the weight of heavy AI related spending.
The key near term swing factor remains execution on the AI infrastructure build and early CIS ramps. Third quarter 2026 showed higher sales but softer earnings, so the biggest risk is that elevated CapEx and concentrated AI contracts strain margins and cash generation before the revenue tied to this guidance fully shows up.
The recent launch of Akamai Inference and Agent Sandbox ties directly into the guidance story. These offerings give customers a way to run AI workloads, tune models and keep them close to data on Akamai’s infrastructure, which matters if the firm wants its projected cloud services revenue to scale into the ranges outlined for 2027 and beyond.
That same launch also sharpens the trade off. Building out NVIDIA based GPU clusters and broader AI infrastructure supports the long term cloud narrative, but it adds execution risk around utilization, profitability and customer concentration. For you as a shareholder, the question is how confidently you think Akamai can fill that capacity at the economics it is targeting.
Akamai Technologies Long Range Guidance Through the Analyst Lens
Akamai Technologies' narrative projects US$7.2b revenue and US$730.7m earnings by 2029. This assumes 18.8% yearly revenue growth and an earnings increase of about US$319.7m from US$411.0m today.
Analysts are effectively tying Akamai Technologies' long dated AI infrastructure plans to a specific financial destination in 2029. The consensus case links the multiyear CIS and security ramps to US$7.2b in total revenue and US$730.7m of earnings, which is a step up from the US$411.0m profit figure used as the base today.
That path builds in 18.8% annual revenue growth over the next three years and a margin lift from 9.5% to 10.1%. For you as an investor, the focus may be less on whether those exact numbers occur and more on whether the broad direction, higher AI related and security contribution with modestly better profitability, appears reasonable given the scale of the planned US$5.5b AI build.
There is also wide dispersion inside that 2029 earnings line. Forecasts range from US$437.9m to US$1.1b, which indicates that the market is still debating how much CIS utilization, pricing power and cost efficiency Akamai can realistically achieve as those Anthropic and robotics contracts ramp.
The valuation overlay makes the narrative more demanding. To align with the consensus targets, the stock would need to trade on a P/E of 41.9x those 2029 earnings, compared with 34.8x today and 21.3x for the broader US IT group. In that scenario, investors would be paying a premium multiple on top of optimistic long term AI and security assumptions.
Uncover why Akamai Technologies' fair value indicates an 87% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle to watch is capital intensity. The most pessimistic Akamai Technologies analysts already assumed only 11.8% yearly revenue growth and earnings of about US$440.6m by 2029, barely above the US$411.0m starting point. That cohort viewed high AI CapEx as a ceiling on upside. This new guidance and AI launch news could push those expectations in either direction, so treat it as a prompt to compare several forecast paths before forming your own view.
Explore 3 other Akamai Technologies fair value estimates, including one that suggests it could be worth just $93.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Akamai Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Akamai Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Akamai Technologies' overall financial health at a glance.
Looking for more investment ideas beyond Akamai Technologies?
Once you have a view on Akamai Technologies, it can help to widen the lens and compare it with other opportunities that line up with your risk tolerance, income needs, and balance sheet preferences. The Simply Wall St Screener is a practical way to do that side by side, using consistent data and filters.
- If you are hunting for mispriced quality, start by scanning a curated set of 38 high quality undervalued stocks that pair strong fundamentals with potentially appealing valuations.
- If resilience matters more than excitement, filter for 31 resilient stocks with low risk scores that score well on stability and financial strength.
- If robust finances are your priority, build a shortlist from the list of solid balance sheet and fundamentals (25 results) and compare those metrics directly with Akamai Technologies.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com