


Why Corning’s latest earnings are drawing fresh attention
Corning (GLW) just posted third quarter results that showed higher sales and net income compared with a year earlier, alongside new guidance pointing to further gains in core sales and earnings per share.
Corning’s latest report lands after a sharp pullback in the shares, with a 30 day share price return of down 32.3% and a 90 day move of down 32.7%, even though the year to date share price return is up 17.1% and the 3 year total shareholder return is a little over 3x. This hints that investors are reassessing near term risks while still reflecting a powerful longer term payoff from holding the stock, including dividends.
See how Corning’s post-earnings pullback compares with other large tech-oriented manufacturers by reviewing our hand picked list of solid balance sheet and fundamentals (25 results).
Corning now pairs a sharp recent drop with fresh guidance that points higher. Does it make more sense to step in after this slide, or wait for the valuation to reset further before committing new money?
Most Popular Narrative: 41.9% Undervalued
At a last close of $106.13 against a most popular narrative fair value of $182.76, Corning screens as heavily discounted, with that gap hinging on whether long term optical, solar and photonics plans actually turn into higher earnings power.
The numbers imply that Corning’s current valuation treats the stock as if execution risk, equity issuance and mixed end market conditions fully offset the multibillion long term growth opportunities in AI data centers, U.S. solar and photonics. This supports the view that the shares are undervalued.
See why 112 investors see Corning as 42% undervalued.
Result: Fair Value of $182.76 (UNDERVALUED)
Still, Corning’s reliance on non GAAP measures and its use of a US$2b at-the-market equity program could both unsettle investors if expectations prove too optimistic.
Find out about the key risks to this Corning narrative.
Another View: Corning’s valuation through a simple earnings lens
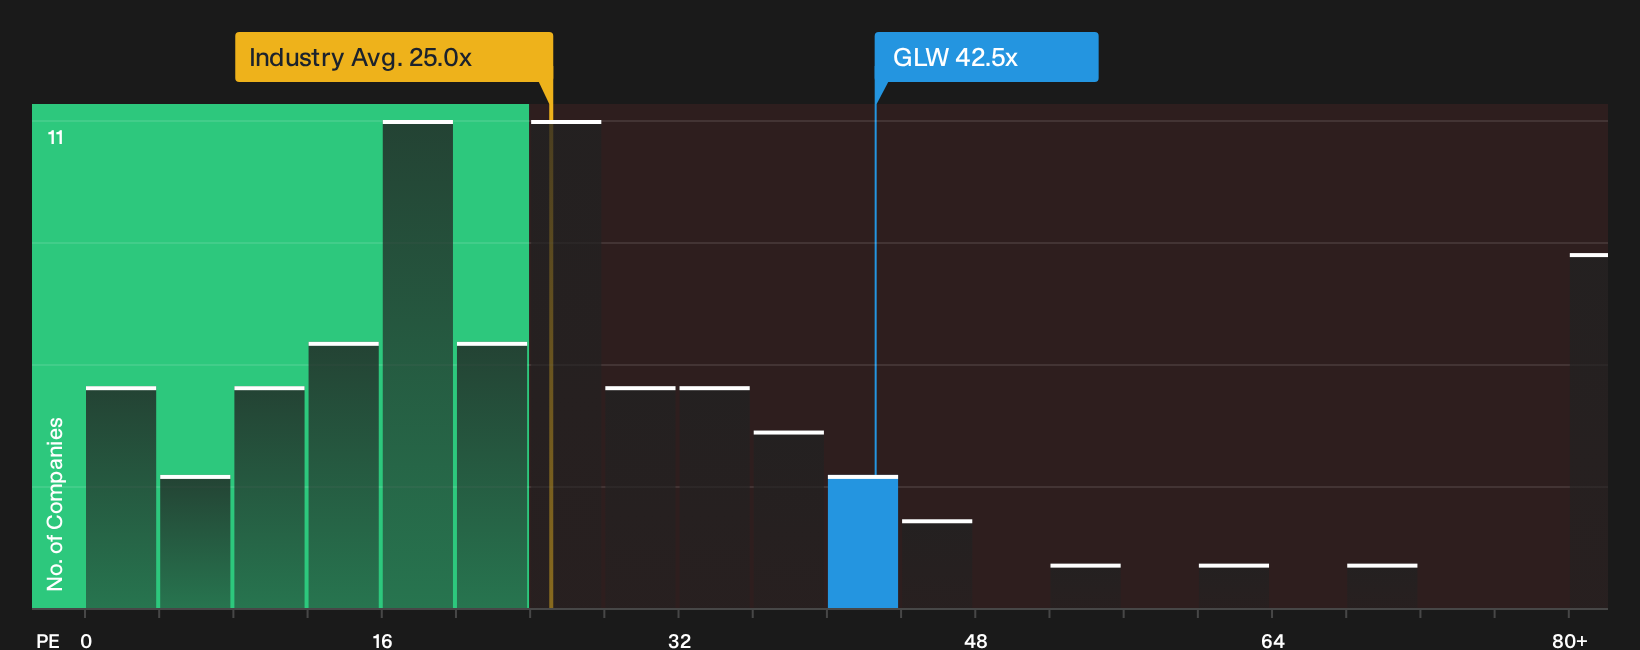
The popular narrative leans on discounted cash flows and points to Corning as undervalued. A plain P/E check tells a different story. The stock trades at 42.5x earnings, slightly above a fair ratio of 42.1x, and well above both the US Electronic industry at 25x and peers at 31.7x. That gap suggests investors are already paying a premium. How comfortable are you with that pricing if the bullish scenarios take longer to play out?
For a closer look at how this earnings based premium could evolve as sentiment shifts, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Corning is split, with some investors focused on the upside story and others zeroing in on the red flags. If you want to move quickly and reach your own verdict based on the underlying data, weigh the 4 key rewards and 1 important warning sign.
Looking for more Corning investment ideas?
If Corning has sharpened your focus, use that momentum and scan a wider field of opportunities so you are not relying on a single story.
- Target resilient cash generators by reviewing our screener for companies with a list of solid balance sheet and fundamentals (25 results) that can better withstand shocks and still fund growth.
- Hunt for mispriced opportunities and compare Corning against a curated set of 38 high quality undervalued stocks that pair quality fundamentals with value oriented pricing.
- Strengthen your income game by lining up Corning beside a group of dependable 7 dividend fortresses that focus on higher yields backed by solid financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com