


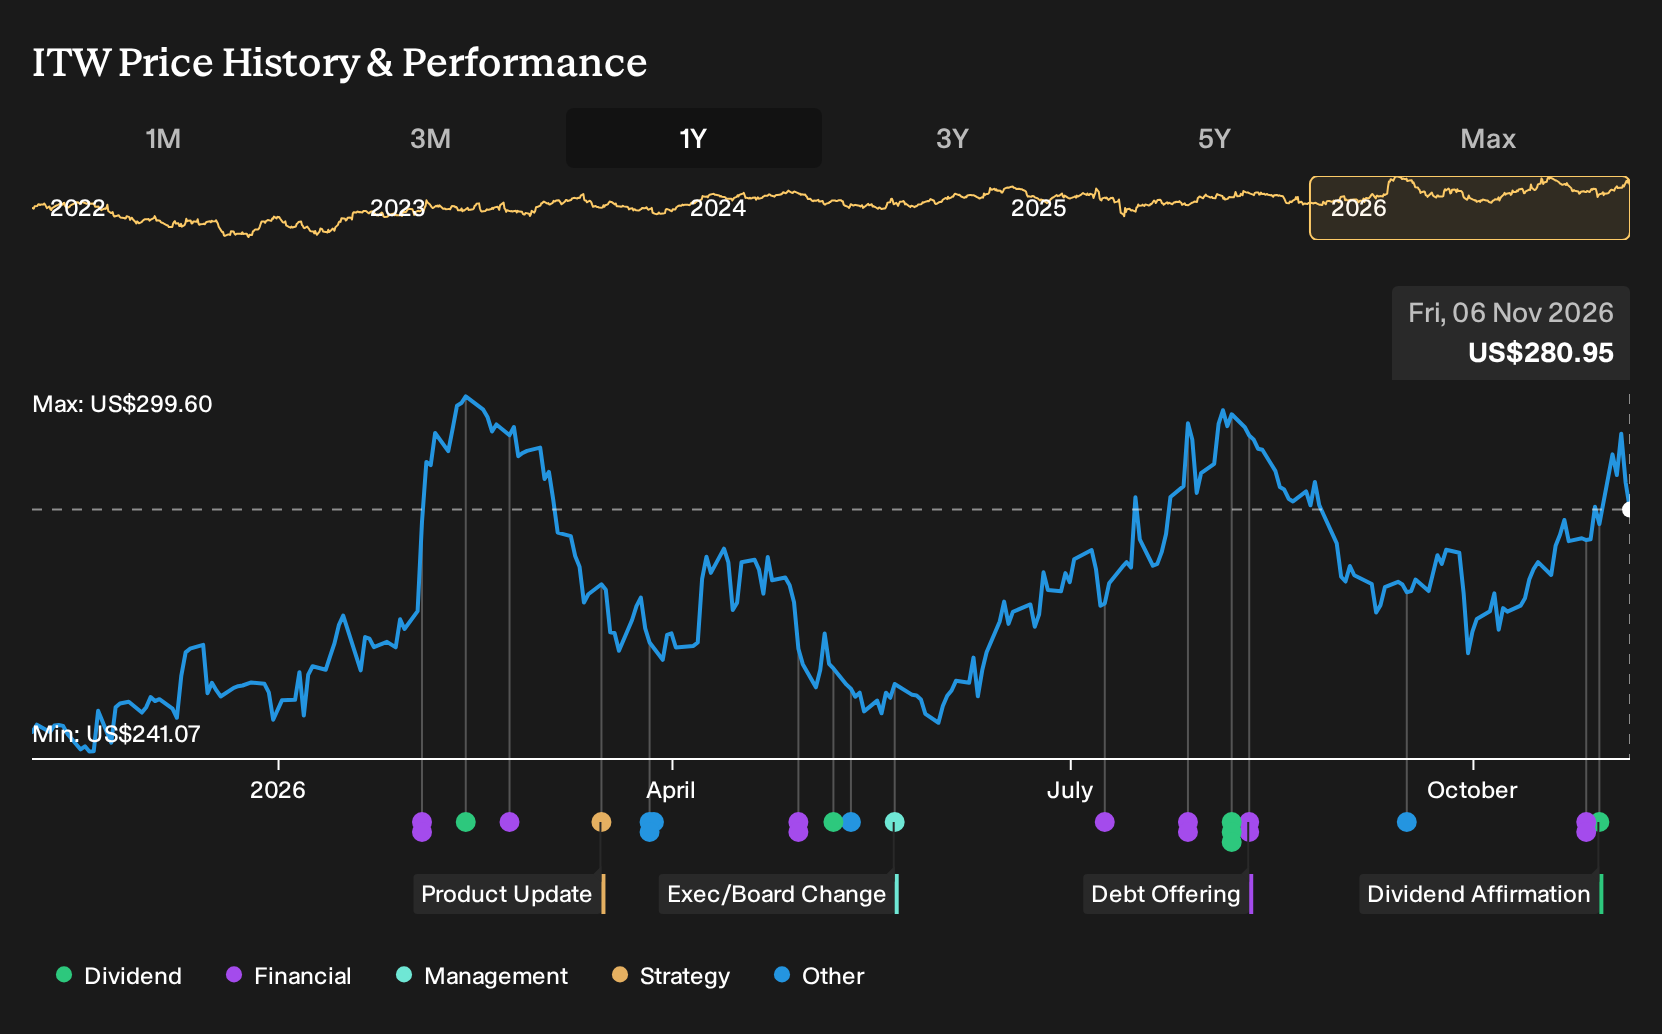
- Illinois Tool Works reported third quarter 2026 sales of US$4,236 million and net income of US$855 million, raised full year 2026 GAAP EPS guidance to US$11.45 to US$11.55 per share, increased revenue growth guidance to 4.5% to 5.5%, and affirmed a US$1.72 fourth quarter dividend payable in January 2027.
- The tighter EPS range, higher revenue growth outlook, and continued dividend payments indicate that Illinois Tool Works is focusing on consistent execution, disciplined cost control, and ongoing cash returns to shareholders, supported by current demand conditions and foreign exchange assumptions.
- We will now assess how Illinois Tool Works' third quarter earnings and higher 2026 guidance could reshape the existing investment narrative.
Scan how Illinois Tool Works' tightened guidance and affirmed payout compare with those of other established dividend payers through a curated list of 7 dividend fortresses.
Illinois Tool Works Investment Narrative Recap
To own Illinois Tool Works, you generally need to believe this industrial group can keep turning steady demand across its seven segments into consistent earnings and free cash flow, helped by enterprise initiatives and product refreshes. The raised 2026 guidance points to management confidence in execution, although input cost timing and softer consumer exposed businesses still hang over the near term.
The key short term swing factor is whether pricing and productivity are enough to offset the expected 2026 margin headwind from costs. The main operational risk remains weaker trends in cyclical areas such as Food Equipment and Specialty Products, where a slower recovery could cap organic growth even as enterprise programs support margins.
The guidance upgrade on October 27 looks most relevant. Illinois Tool Works now targets GAAP EPS of US$11.45 to US$11.55 and revenue growth of 4.5% to 5.5% for 2026, while keeping organic growth guidance at 3% to 4%. That tighter range, coming alongside third quarter sales of US$4,236 million and net income of US$855 million, frames near term expectations more clearly.
For you as an investor, the raised outlook highlights execution around customer backed products, margin initiatives and capital allocation, but it does not remove the known risks. Input cost pressure, high leverage and exposure to softer end markets can still affect how closely actual results track that guidance, which keeps earnings delivery the core catalyst to watch into 2027.
Illinois Tool Works' current earnings of US$3.2b are set against consensus forecasts for US$18.4b in revenue and US$3.8b in earnings by 2029, which implies analysts are building in 3.8% yearly revenue growth and an earnings increase of about US$0.6b by that year.
Uncover why Illinois Tool Works' fair value indicates a 5% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$174 to US$295, which shows how far apart private investors can be on Illinois Tool Works. Set that against the raised 2026 guidance and affirmed US$1.72 dividend. You are weighing execution on pricing and margins against pockets of softer, cyclical demand.
Explore another Illinois Tool Works fair value estimate, including one that suggests it could be worth as much as $294.57.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Illinois Tool Works research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Illinois Tool Works. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Illinois Tool Works' overall financial health at a glance.
Looking For More Investment Ideas Beyond Illinois Tool Works?
Once you have a view on Illinois Tool Works, it can help to widen the lens and compare it with other companies that fit different return and risk profiles using the Simply Wall St Screener.
- For investors who care about income resilience before anything else, start with a shortlist of potential "paycheck" stocks through the 7 dividend fortresses.
- If preservation of capital ranks high for you, scan a curated pool of steadier businesses using the 31 resilient stocks with low risk scores.
- When you want to hunt for quality stories that are not yet on many radars, broaden your watchlist with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com