


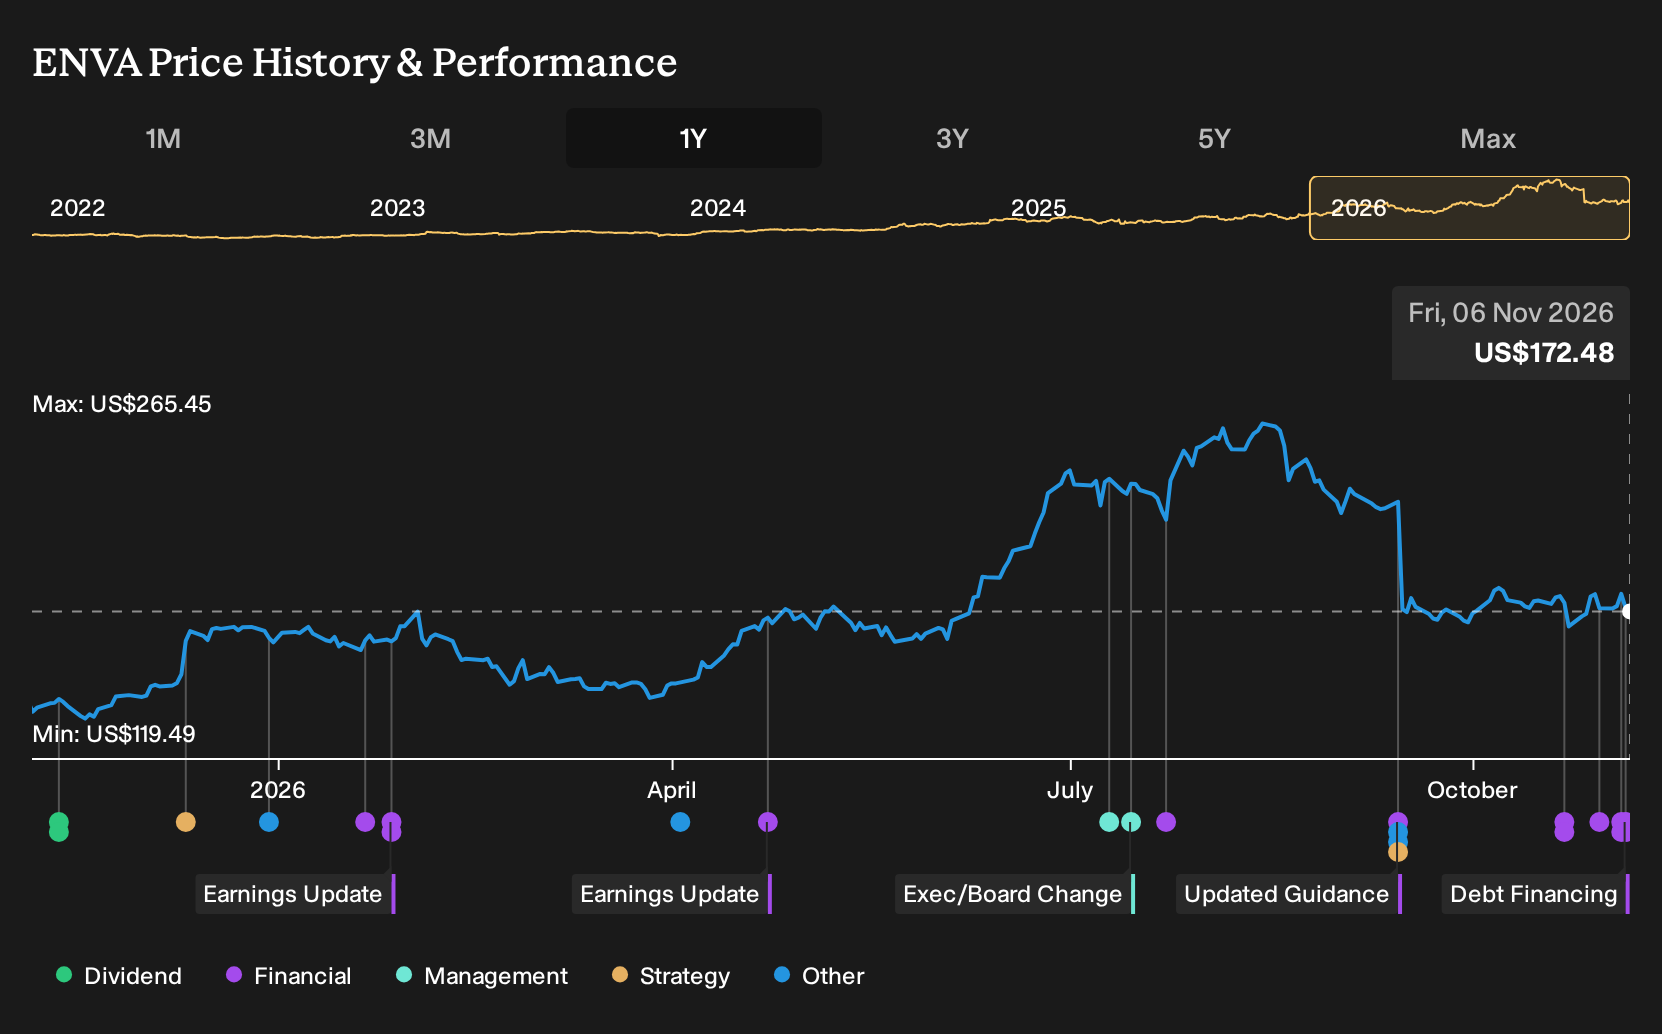
- Enova International priced and completed a US$600 million private offering of senior unsecured 8.75% notes due 2031, guaranteed by certain domestic subsidiaries, and intends to redeem its outstanding 11.25% senior notes due 2028 and repay part of its revolving credit facility with the proceeds.
- This refinancing move reshapes Enova International's funding mix, with the shift from 11.25% notes to 8.75% paper directly affecting interest costs and flexibility around its US$900 million asset backed revolving facility.
- We will examine how Enova International's investment narrative is affected by this refinancing and its move to 8.75% senior notes.
Enova International Investment Narrative Recap
To own Enova International you need to be comfortable with a tech driven non bank lender that leans on AI underwriting and capital markets funding to keep small business and consumer originations flowing. The key short term swing factor is whether credit performance and funding access stay aligned with its growth ambitions rather than working against them.
This new 8.75% senior note and the planned redemption of the 11.25% 2028 notes mainly reshuffle the liability stack rather than rewrite the operating story. The move directly touches funding costs and flexibility, but the bigger near term risk still sits with regulation on high cost lending and any tightening in wholesale credit conditions.
The recent Fourth Amendment to Enova International’s secured asset backed revolving credit facility, lifting total commitments from US$825m to US$900m, matters when you read it next to the fresh US$600m senior notes. Together they frame how much receivable growth the balance sheet can support without stretching liquidity.
In terms of catalysts, that larger revolver can support more small business and consumer receivables if demand holds and credit metrics behave as expected. The flip side is clear: reliance on external borrowing rather than deposits, plus a higher absolute debt load, keeps funding risk in focus if capital markets or securitization appetite were to weaken.
Enova International's current analyst narrative points to US$6.7b in revenue and US$601.7m in earnings by 2029, built on a 58.4% yearly top line growth rate and an earnings increase of about US$246m from US$355.5m today.
Uncover why Enova International's fair value indicates a 38% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest analysts frame Enova International very differently. They worry that rapid small business expansion could strain underwriting, so their pre news models pointed to about US$6.6b in revenue and US$596.5m in earnings by 2029. You should treat this refinancing as a fresh data point that might shift those views in either direction.
Explore 2 other Enova International fair value estimates, including one that suggests as much as 38% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Enova International research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Enova International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enova International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Enova International?
Once you have a view on Enova International, it can help to compare that thesis against other businesses with very different balance sheets and risk profiles. The Simply Wall St Screener lets you do that quickly by filtering for the kind of traits you care about most, whether that is quality, value, dividends, or resilience.
- If you care most about paying a fair price for quality, start with companies that screen as 38 high quality undervalued stocks based on both cash generation and balance sheet strength.
- If resilience comes first for you, focus your search on a 31 resilient stocks with low risk scores that filters for stocks with more durable financial profiles and fewer red flags.
- If you are hunting for fresh ideas off the beaten path, widen your watchlist with a 19 high quality undiscovered gems that still show solid fundamentals even if they are not widely followed yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com