


- LVMH Moët Hennessy Louis Vuitton Société Européenne has appointed Hector Muelas as Chief Brand Creative Officer of Louis Vuitton, effective 1 November 2026. He will be responsible for global brand storytelling, campaigns and content production, reporting to Deputy CEO Damien Bertrand.
- The creation of a group-level brand creative role at Louis Vuitton focuses management attention on how marketing execution, cultural relevance and client connection support LVMH's wider multi-division earnings profile.
- We will now look at how LVMH's investment narrative could be influenced by Hector Muelas taking charge of Louis Vuitton's storytelling.
Scan how LVMH's renewed brand focus compares with other consumer leaders by lining up its story against 226 high quality undervalued stocks that could be setting up their next reputational breakout.
LVMH Moët Hennessy - Louis Vuitton Société Européenne Investment Narrative Recap
To own LVMH Moët Hennessy Louis Vuitton Société Européenne you need to believe its brand power and multi division model can handle softer Fashion and Leather Goods trends, volatile Chinese demand and currency pressure. The near term swing factor is whether weak Asia, especially China, stops worsening. On that axis, this brand creative hire is not a material operational shift.
The biggest near risk still sits in volume softness meeting cost inflation and FX headwinds, which could squeeze margins if sales stay sluggish. Centralising Louis Vuitton storytelling may help protect desirability and reputation, particularly after recent disputes in China, but any financial effect is likely to be gradual.
Recent commentary around LVMH Moët Hennessy Louis Vuitton Société Européenne has highlighted cost discipline and a 22.5% group operating margin in H1 2026 as a key support for the thesis. That efficiency focus matters more for earnings over the next year than a new creative leadership role, which is primarily about long term brand health and cohesion.
Against that backdrop, Hector Muelas taking control of Louis Vuitton campaigns and client facing content sits alongside ongoing investments in AI, product development and experiential retail. For investors tracking catalysts, the hire slots into the broader question of whether LVMH can keep margins resilient while Fashion and Leather Goods digest weaker Chinese demand and other divisions, such as Sephora or Watches and Jewelry, carry more of the growth load.
LVMH Moët Hennessy Louis Vuitton Société Européenne's analyst narrative points to €91.1 billion of revenue and €15.0 billion of earnings by 2029, based on revenue growing 4.6% a year and earnings rising by about €4.1 billion from €10.9 billion today.
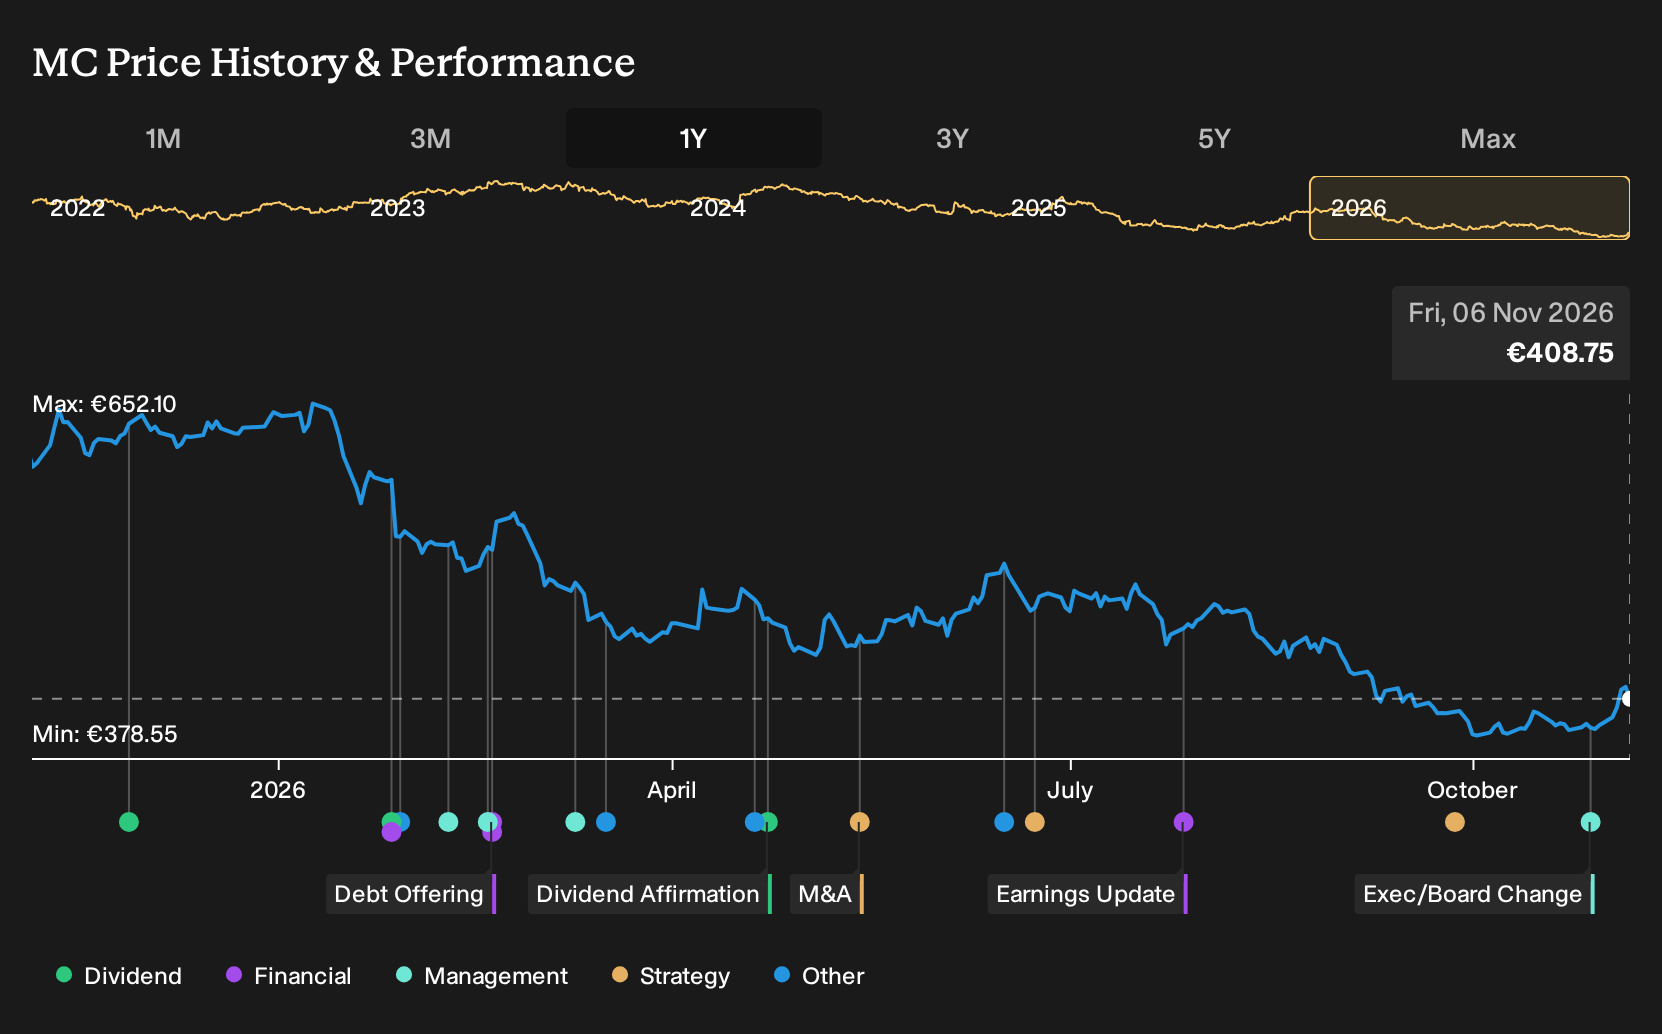
Uncover why LVMH Moët Hennessy - Louis Vuitton Société Européenne's fair value indicates a 20% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish catalyst you might weigh against the consensus focus on Chinese softness is capital redeployment. The most optimistic analysts were already assuming revenue of €96.7b and earnings of €17.1b by 2029, helped by higher margin projects and acquisitions. With Hector Muelas shaping Louis Vuitton storytelling, those projections could shift again, in either direction.
Explore 13 other LVMH Moët Hennessy - Louis Vuitton Société Européenne fair value estimates, including one that suggests as much as 66% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your LVMH Moët Hennessy - Louis Vuitton Société Européenne research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for LVMH Moët Hennessy - Louis Vuitton Société Européenne. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate LVMH Moët Hennessy - Louis Vuitton Société Européenne's overall financial health at a glance.
Looking For More Investment Ideas Beyond LVMH?
Once you have a view on LVMH Moët Hennessy Louis Vuitton Société Européenne, it can help to line it up against other opportunities so you can see where the risk and return trade off looks more appealing.
- If you want to focus on quality at a discount, start by scanning our list of 226 high quality undervalued stocks that combine robust fundamentals with lower market expectations.
- For investors who care most about balance sheet strength, you can filter for companies with conservative leverage and healthy liquidity using the list of solid balance sheet and fundamentals (193 results) so you can compare resilience across sectors.
- If you are hunting for fresh ideas away from crowded trades, you can sort through 574 high quality undiscovered gems that may not be on every analyst's radar yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com