


- Merck has reported detailed Phase 3 data in endometrial cancer for KEYTRUDA and sacituzumab tirumotecan, advanced melanoma results for intismeran plus KEYTRUDA, new COPD work with OHTUVAYRE, expanded HIV presentations, and raised its 2026 sales outlook to US$66.8b to US$67.3b.
- Together, these updates highlight how Merck is leaning on late stage oncology programs and a broader respiratory and HIV portfolio to support future cash flows as KEYTRUDA moves closer to loss of exclusivity.
- Attention now turns to how Merck's investment narrative evolves as its oncology strength, centered on KEYTRUDA, is reinforced by new endometrial cancer data.
Scan beyond Merck and compare this oncology and respiratory story with a hand picked group of resilient healthcare names in the 31 resilient stocks with low risk scores.
Merck Investment Narrative Recap
To stay comfortable as a Merck shareholder, you need to believe the business can convert its broad late stage pipeline into durable cash flows as KEYTRUDA heads toward loss of exclusivity. The analyst consensus Narrative on Simply Wall St leans on more than US$70b of potential mid 2030s revenue from over 20 planned growth drivers to support that view.
Near term, the raised 2026 sales outlook and solid third quarter revenue of US$18,085 million keep attention on execution, not reinvention. The biggest operational risk remains that newer oncology, cardiometabolic, respiratory and HIV products do not scale quickly enough, which would leave earnings and already thin 3.6% margins under pressure.
The ENHANCE 3 launch for OHTUVAYRE matters because it shows Merck putting real weight behind respiratory medicine as a future pillar alongside oncology. Moving straight from recent US approval into a 2,136 patient exacerbation focused study is an operational signal that management wants hard data on outcomes, not just lung function.
If ENHANCE 3 reads out well, OHTUVAYRE could become more than a niche bronchodilator and instead contribute to the broader “20 plus growth drivers” pipeline story investors are watching. If efficacy or safety disappoint in this higher risk exacerbating COPD population, it would not break the Merck thesis, but it would trim one of the cleaner non oncology catalysts on the table.
Merck's current analyst narrative points to revenues of US$74.9b and earnings of US$22.1b by 2029, based on an assumed 4.0% yearly revenue growth rate and an earnings increase of US$18.9b from US$3.2b today.
Uncover how Merck's fair value indicates a 9% potential upside to its current price before that discount closes for Merck investors.
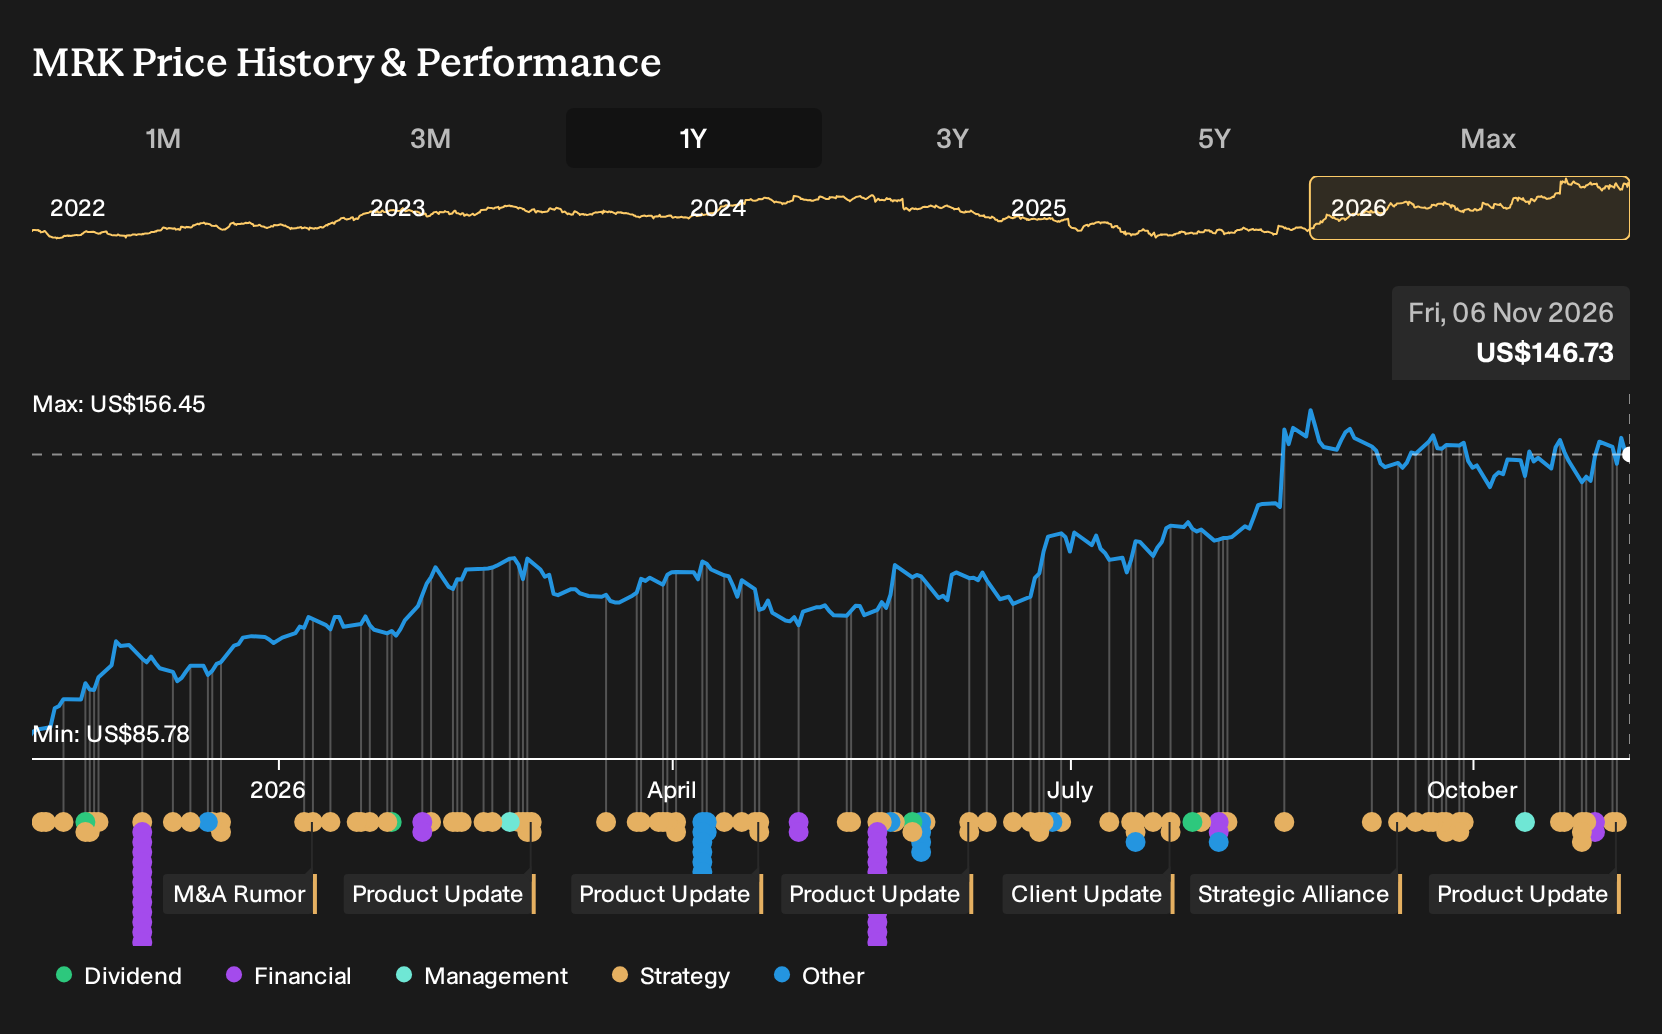
Exploring Other Perspectives
One bullish catalyst the highest analysts focus on is Merck’s broader pipeline beyond oncology, including respiratory and HIV. Before this COPD and HIV news, they were modeling revenues of about US$82.1b and earnings of US$30.2b by 2029. That is far more optimistic than consensus, and these new data could shift those narratives again.
Explore 5 other Merck fair value estimates, including one that suggests as much as 60% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Merck research is our analysis highlighting 2 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for Merck. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Merck's overall financial health at a glance.
Looking for more Merck investment ideas?
If this Merck story has sharpened your thinking and you want to widen the opportunity set, the Simply Wall St Screener can help you hunt for other listed businesses that match your risk tolerance and income goals.
- For investors who care most about resilience and balance sheet strength, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without relying on heavy leverage.
- If you are hunting for potential mispricing, check out a 38 high quality undervalued stocks that combines stronger fundamentals with prices that analysts think sit below fair value.
- Income focused investors can look for steadier cash distributions through a 7 dividend fortresses that offers higher yields backed by underlying earnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com