


- Recent commentary on Valley National Bancorp highlights that its broad lending, deposit, and wealth services platform is positioned to benefit from higher interest rates, with commercial and specialty deposit accounts playing a central role in funding.
- The focus on growing commercial and specialty deposits is reshaping Valley National Bancorp's funding mix, which may affect how its net interest margin responds to changes in the rate cycle.
- We will look at how Valley National Bancorp's growing commercial and specialty deposit base reshapes its investment narrative in a rising rate backdrop.
Look beyond Valley National Bancorp and compare its rate sensitive model with a hand picked list of banks and financials in the list of solid balance sheet and fundamentals (25 results)
Valley National Bancorp Investment Narrative Recap
To be comfortable owning Valley National Bancorp, you need to believe its push toward core commercial and specialty deposits keeps funding relatively stable while it works on loan profitability and efficiency. The analyst consensus Narrative on Simply Wall St leans on this shift, with earnings forecasts tied to deposit mix, digital small business banking, and AI driven cost savings.
In the very near term, the key swing factor is how deposit costs and net interest margin behave as rates move. The main risk is that a still modest net interest margin and geographic concentration in New Jersey, New York, and Florida leave earnings more exposed if loan pricing, mix, or credit quality disappoint.
The Bluevine deposit and small business banking combination is central to this story. Management expects about US$2.1b of low cost Bluevine small business deposits and roughly 175,000 active small business clients to be added, which ties directly into the current focus on rate sensitive funding and operating accounts.
For you as a shareholder, the operational question is whether Valley National Bancorp can bring those balances on balance sheet smoothly, replace higher cost brokered funding, and then cross sell treasury and lending products without stressing credit or systems. Execution on that integration, alongside the AI efficiency targets and CRE de risking, will likely shape how quickly the current catalysts play through earnings and returns.
Valley National Bancorp's current analyst narrative points to revenues of US$3.1b and earnings of US$1.0b by 2029, based on forecast revenue growth of 15.1% a year and an increase in profit from US$663.9m today to that 2029 consensus level, which represents about a 50% earnings increase from current earnings.
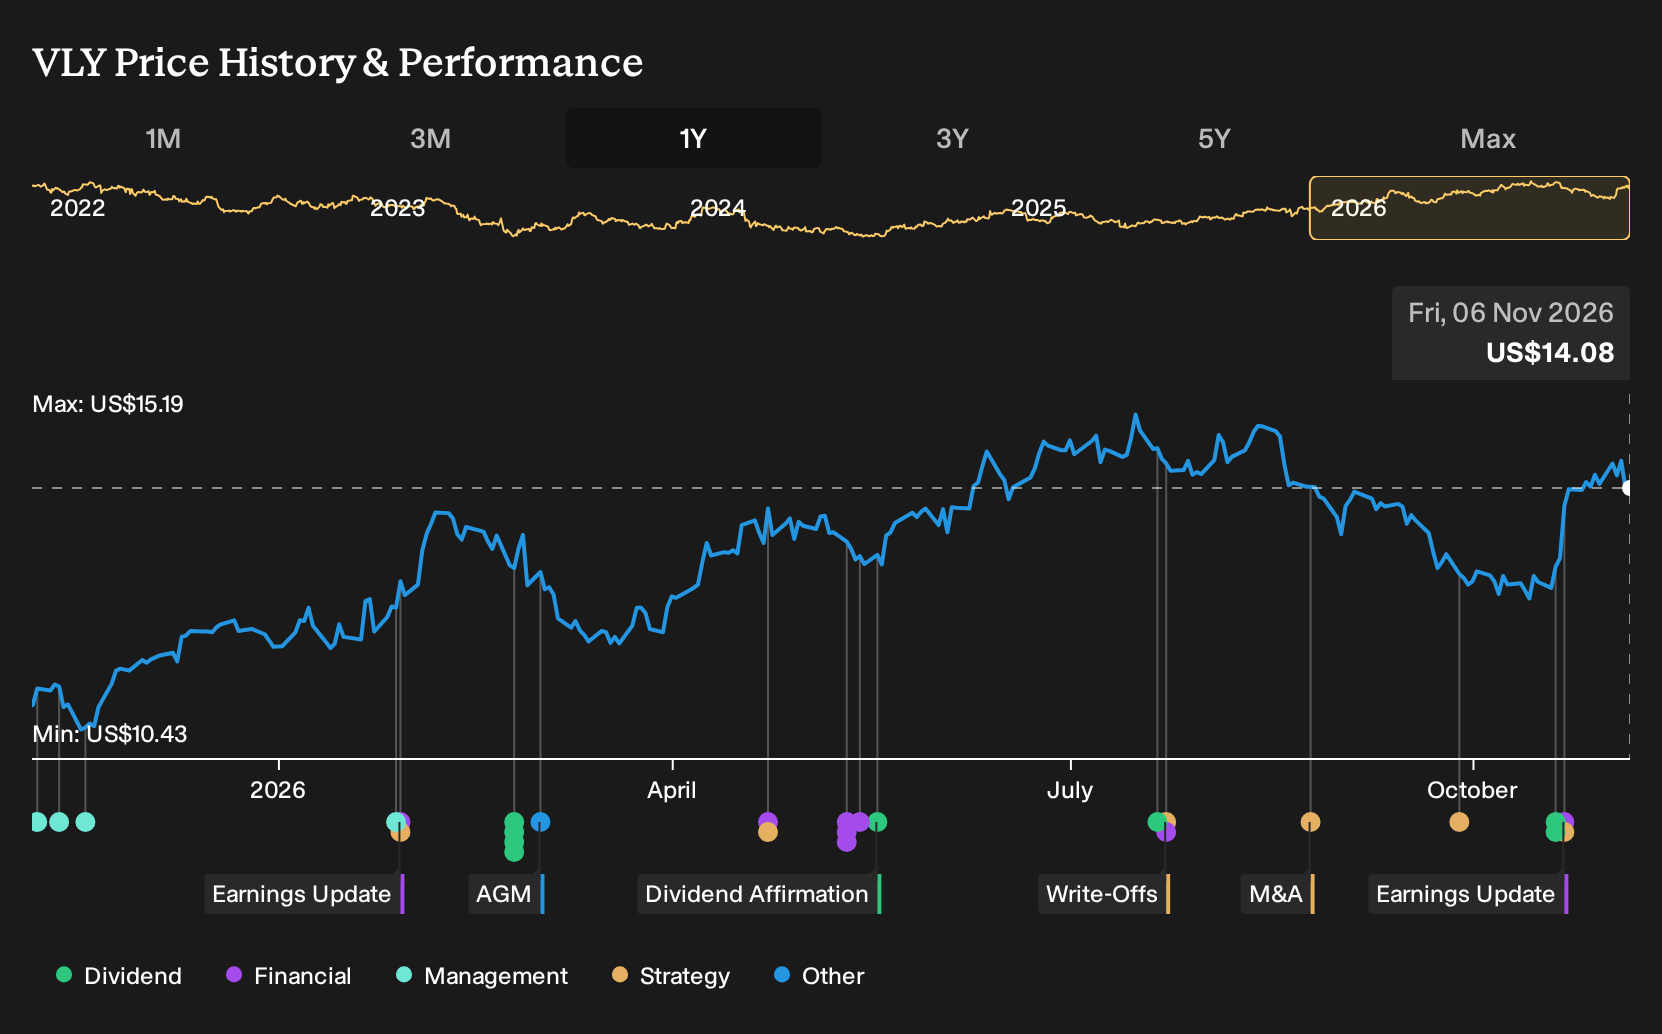
Uncover why Valley National Bancorp's fair value indicates an 18% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$16.57 to US$24.05 per share for Valley National Bancorp, which shows how far opinions can stretch. Those views sit beside live questions on geographic concentration, weaker loan profitability, and deposit mix shifts, so you should weigh several perspectives before leaning on any single narrative.
Explore 2 other Valley National Bancorp fair value estimates, including one that suggests it could be worth just $16.57.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment outcomes rarely result from following the herd, so consider trusting your own analysis.
- A great starting point for your Valley National Bancorp research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Valley National Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Valley National Bancorp's overall financial health at a glance.
Looking for more investment ideas beyond Valley National Bancorp?
If Valley National Bancorp has sharpened your thinking about rate sensitivity, funding mix, and balance sheet strength, you can apply the same lens to a wider opportunity set using the Simply Wall St Screener.
- If you want potential value combined with quality fundamentals, start with a curated group of companies in the 38 high quality undervalued stocks.
- For those who prefer income and stability, focus on businesses that prioritize reliable payouts in the 7 dividend fortresses.
- If capital preservation and resilience matter most to you, filter for financially robust businesses through the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com