


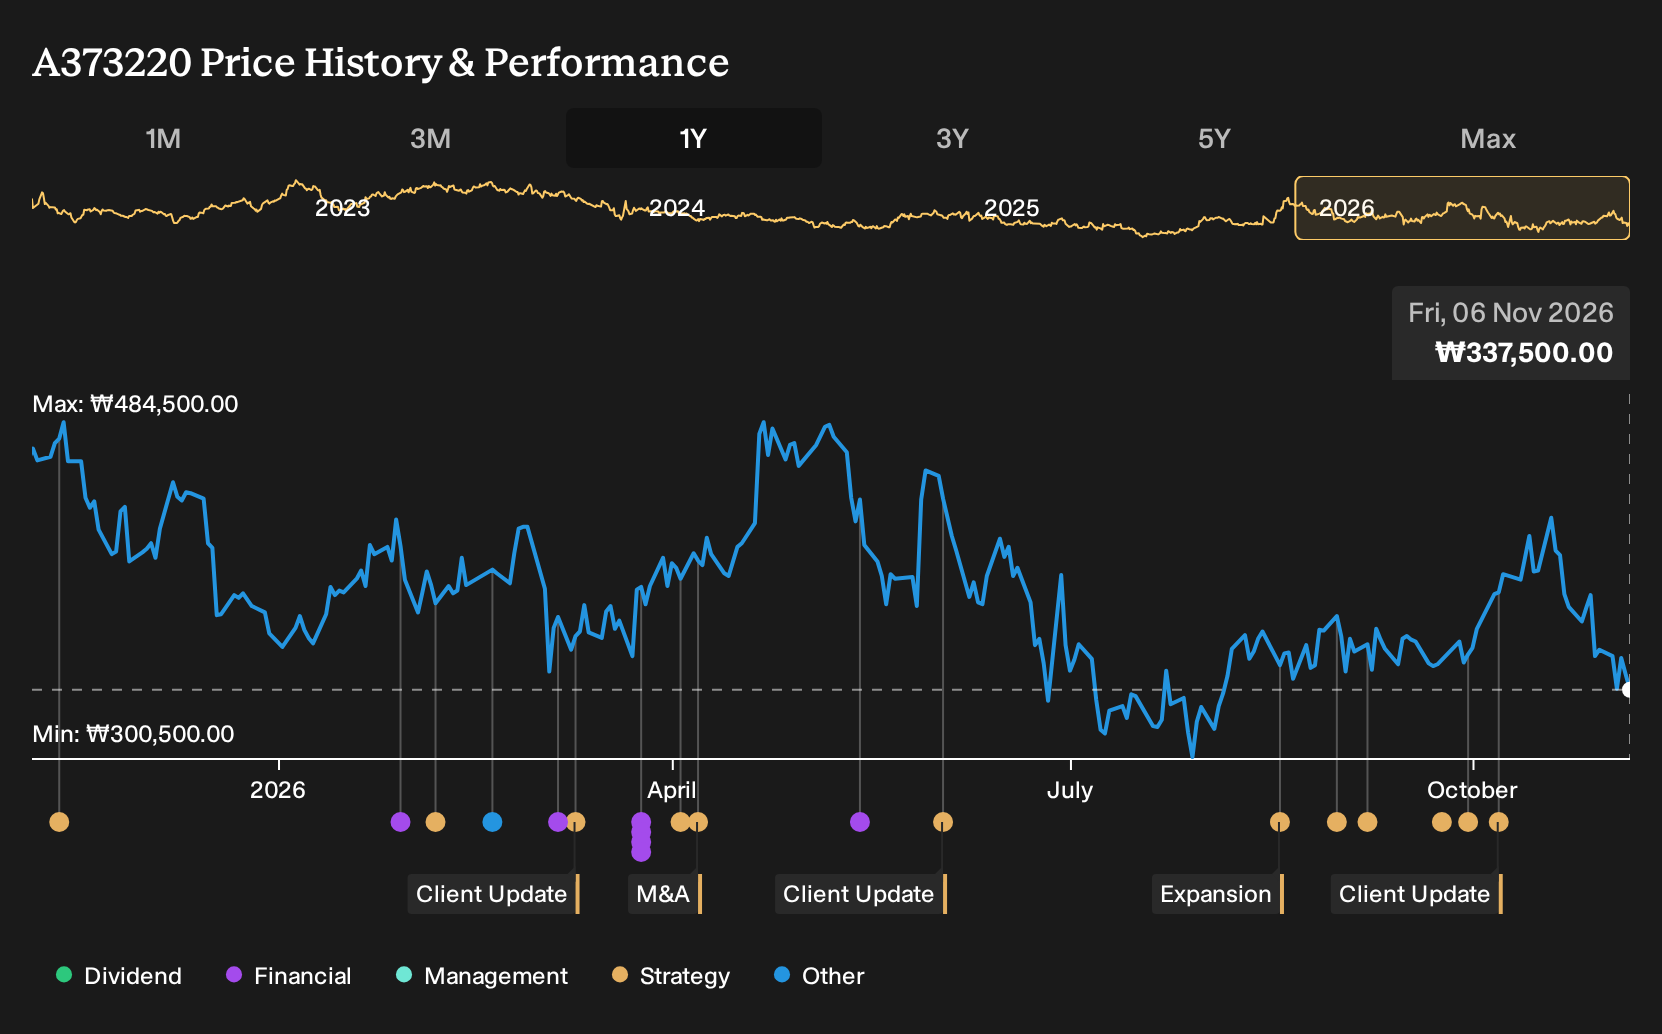
LG Energy Solution looked busy building capacity and signing ESS and EV battery deals while shareholders were watching something very different happen in their portfolios. For LG Energy Solution shareholders, the loss over the past year was 27.2%, including dividends. If you had been weighing that bullish analyst upside against the more cautious targets back on 6 November 2025, how much warning did those early disagreements really give you about what came next?
This theme extends beyond LG Energy Solution. See which of 41 power grid technology and infrastructure stocks may still merit a closer look.
What Investors Thought LG Energy Solution Was Worth Back Then
The shares cost ₩471,500 at the start of the period, and investors were choosing between two very different stories about where LG Energy Solution might be heading.
On the bullish side, one narrative put Fair Value at ₩531,000, a notional price that would make sense if global EV and renewables demand translated into strong volume growth and higher margins, helped by first-mover status in LFP ESS production.
The more cautious case suggested a Fair Value of ₩427,293, assuming 17.4% annual revenue growth and an 8.7% profit margin while warning that heavy capital spending and rising competition could strain cash flow and earnings stability.
What The Results Changed For The LG Energy Solution Debate
LG Energy Solution’s 2026 third quarter update highlighted higher ESS and EV battery shipments, and new behind the meter contracts in data centers, which supported the optimistic focus on scale and product reach. The Q2 2026 figures told a tougher story. Revenue was ₩7,141,475m against ₩5,565,408m a year earlier, while the business still reported a loss and net margin stayed at -5.3%. The period cut both ways.
The real swing factor was not volume or capacity announcements. It was whether rising sales translated into positive earnings. When you assess another battery producer, check if promised demand shows up in the income statement as sustained profits, not just bigger revenue lines.
What LG Energy Solution’s Lower Price Asks You To Believe
LG Energy Solution now trades at ₩337,500, with the share price down 27.2% over the past year. The analyst consensus Narrative on Simply Wall St places its Fair Value above the current price and frames that gap around storage demand, cylindrical batteries and tighter capital discipline.
The core claim is that ESS and cylindrical orders, plus reduced CapEx, can eventually turn recent losses into more stable profitability. For the fall to look like a potential opportunity rather than a warning, a buyer today would need confidence that this pivot is executed without stretching the balance sheet further.
"The view on LG Energy Solution has shifted from a broad electrification and EV led growth story to a more focused thesis. It now centers on the pivot toward ESS and cylindrical batteries, supported by policy driven demand, a larger ESS and 46 series backlog, and a stronger emphasis on capital discipline."
One Narrative disagrees with today's price. → See where this Narrative says LG Energy Solution should trade
Where LG Energy Solution Connects Next
LG Energy Solution keeps drawing attention to storage demand. Your next question might be what keeps all that stored energy earning its keep.
AI data centers and cloud facilities need reliable power and cooling to stay online. Without robust infrastructure, even abundant battery capacity cannot prevent downtime.
Another specialist builds the power systems and thermal equipment that keep those facilities running. Its hardware and services help data centers handle dense, heat intensive computing loads.
As AI workloads spread and energy storage scales, that behind the scenes role could matter more. If you are studying LG Energy Solution, checking that adjacent piece may round out the picture.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 123% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com