


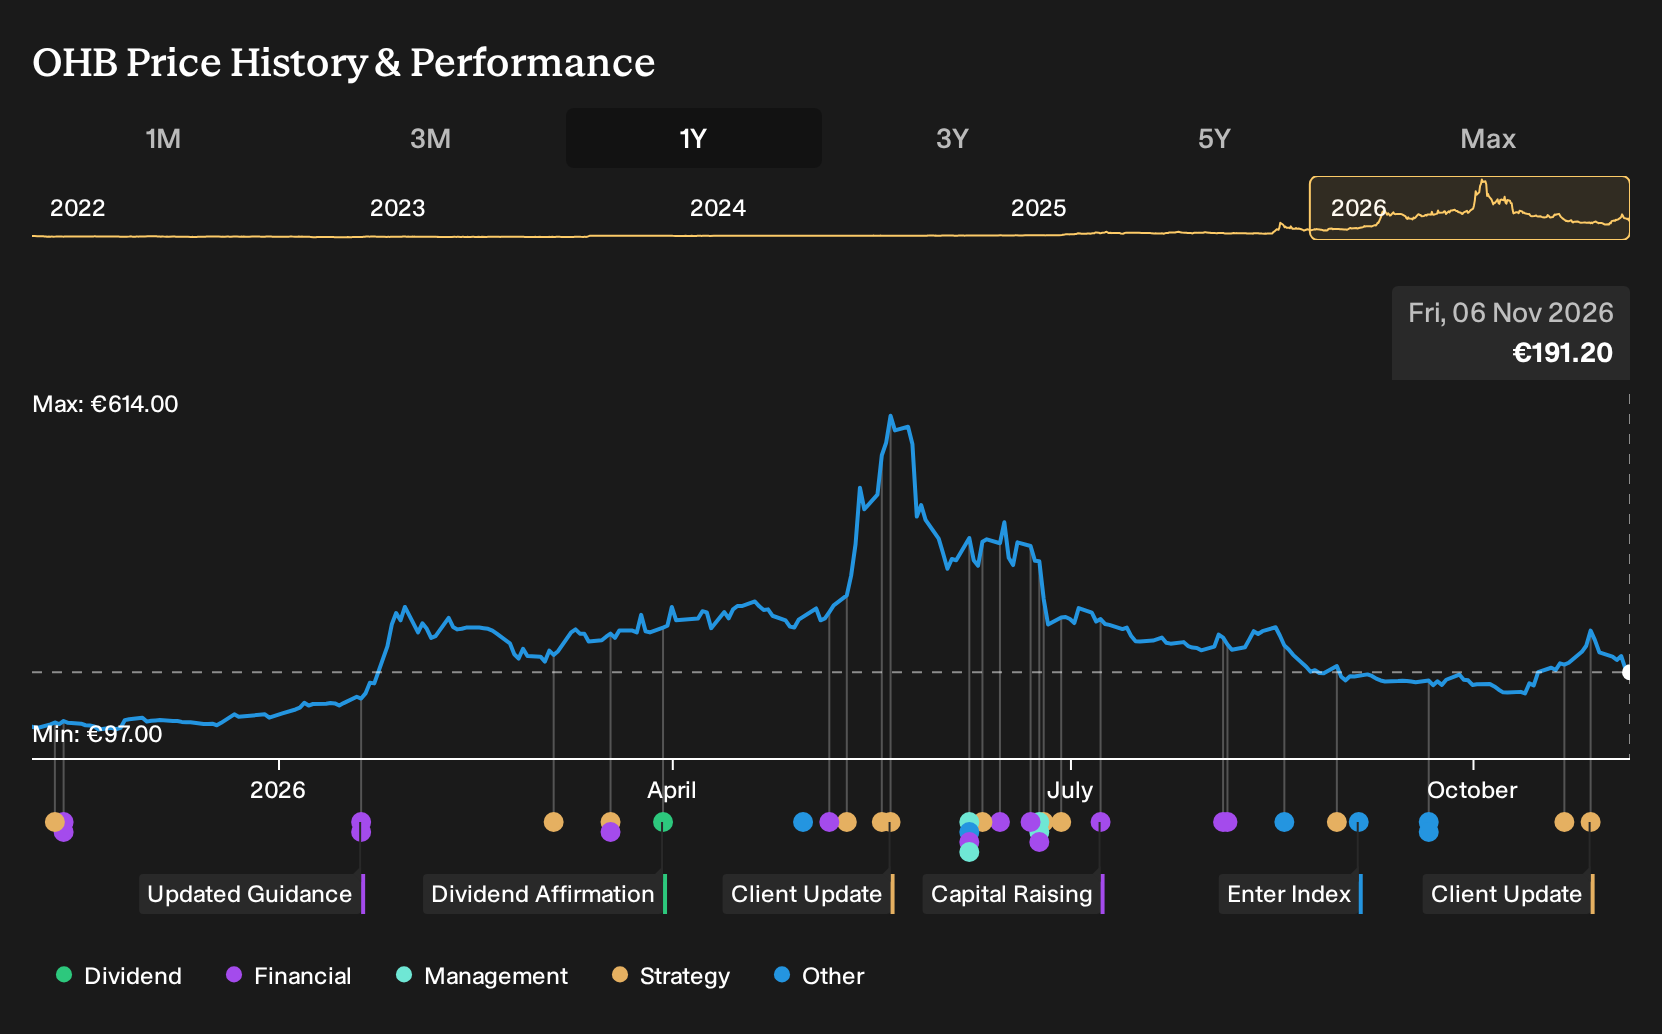
- OHB SE secured a €554 million ESA contract to build the first Sentinel-3 Next Generation Topography satellite and signed a prior Memorandum of Understanding with Astroscale to explore joint projects in space security, space domain awareness and in-orbit servicing across Europe, the UK and Japan.
- The ESA earth observation contract and Astroscale collaboration both point to OHB deepening its role in long duration infrastructure and service style space projects. These initiatives can reshape workload mix, capital needs and execution risk across its satellite and security portfolio.
- This article examines how OHB's investment narrative is influenced by the large ESA Sentinel-3 contract and its expanding space security collaboration.
Explore the space infrastructure theme beyond OHB with a curated list of orbital and aerospace contractors in our 41 power grid technology and infrastructure stocks
OHB Investment Narrative Recap
To own OHB, you need to be comfortable with a project heavy space contractor that is ramping capacity while managing long contract cycles and complex execution. The analyst consensus Narrative on Simply Wall St focuses on strong revenue and earnings growth forecasts and a large backlog. The recent ESA Sentinel 3 award and Astroscale Memorandum of Understanding mainly reinforce that long term workload story rather than changing it.
In the short term, the key swing factor remains how smoothly new facilities, hiring and major programs like Ariane 6 and EPS Sterna are filled and executed without cost overruns. The biggest risk is underutilization of that expanded footprint or delivery issues on large contracts, which would pressure EBIT margins and push out any margin improvement that analysts are expecting.
The Astroscale Memorandum of Understanding looks most relevant here because it connects directly to the space security and resilience theme behind OHB capacity expansion. It gives the group more potential entry points into space domain awareness and in orbit servicing work alongside its existing satellite and launch activities, particularly in Europe, the UK and Japan.
For catalysts, investors are watching whether partnerships like this convert into concrete orders that help absorb new manufacturing and engineering capacity. If joint projects emerge, they could diversify OHB revenue streams across more service style contracts and reduce dependence on a handful of European institutional awards. Any delays or operational setbacks on these complex missions would feed directly into the execution risks already flagged by analysts.
OHB's narrative projects €2.5b revenue and €178.1m earnings by 2029. This reflects forecast revenue growth of 25.5% per year and roughly a threefold earnings increase from €56.1m today.
Uncover why OHB's fair value indicates a 61% potential upside to its current price before that gap begins to close.
Exploring Other Perspectives
Some of the lowest analysts focus on earnings volatility risk instead of upside from the OHB and Astroscale partnership. They see OHB only reaching about €2.5b revenue with €157.9m earnings by 2029 and expect a higher 48.3x P/E. That is a much more cautious story. Use this new MoU as a prompt to compare both narratives yourself.
Explore 2 other OHB fair value estimates, including one that suggests it could be worth just €258.18!
Reach Your Own Conclusion
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your OHB research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for OHB. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OHB's overall financial health at a glance.
Looking for more investment ideas beyond OHB?
Once you have a handle on OHB, it can help to set it alongside a few clear comparables so you can judge risk, quality and price in context.
- If you care most about sturdy balance sheets and resilient fundamentals, start with this curated list of solid balance sheet and fundamentals (193 results) to see which businesses match that profile.
- For readers hunting for mispriced quality, compare OHB against a broader pool of 227 high quality undervalued stocks that combine robust cash flows with stronger financial footing.
- Income focused investors can round out their watchlist by scanning 227 dividend fortresses that prioritize higher yields alongside stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com