


- American Homes 4 Rent reported third quarter 2026 sales of US$498.07 million and net income of US$85.8 million, with diluted earnings per share from continuing operations of US$0.23.
- Over the first nine months of 2026, American Homes 4 Rent produced US$1.44 billion in sales and US$334.17 million in net income, indicating that year-to-date profitability moved differently from the softer quarterly figures.
- We will examine how American Homes 4 Rent's investment narrative is affected by higher sales alongside softer third quarter net income.
Scan beyond American Homes 4 Rent and compare its latest earnings trend with a curated list of solid balance sheet and fundamentals (25 results) that may handle profit swings in very different ways.
American Homes 4 Rent Investment Narrative Recap
To hold American Homes 4 Rent, you need to be comfortable with a business that leans on build to rent projects, lease management and portfolio churn to support funds from operations, even when quarterly earnings move around. The latest quarter shows higher sales but softer net income and EPS, which points attention to cost control and interest expense rather than demand.
In the short term, the key catalyst that the analyst consensus narrative on Simply Wall St focuses on remains execution on moderated in house development and joint ventures, where yields have been underwritten in the mid to high single digit range. The biggest current risk is still a higher for longer rate backdrop that keeps refinancing and acquisition costs elevated. This earnings update does not materially change that risk reward balance.
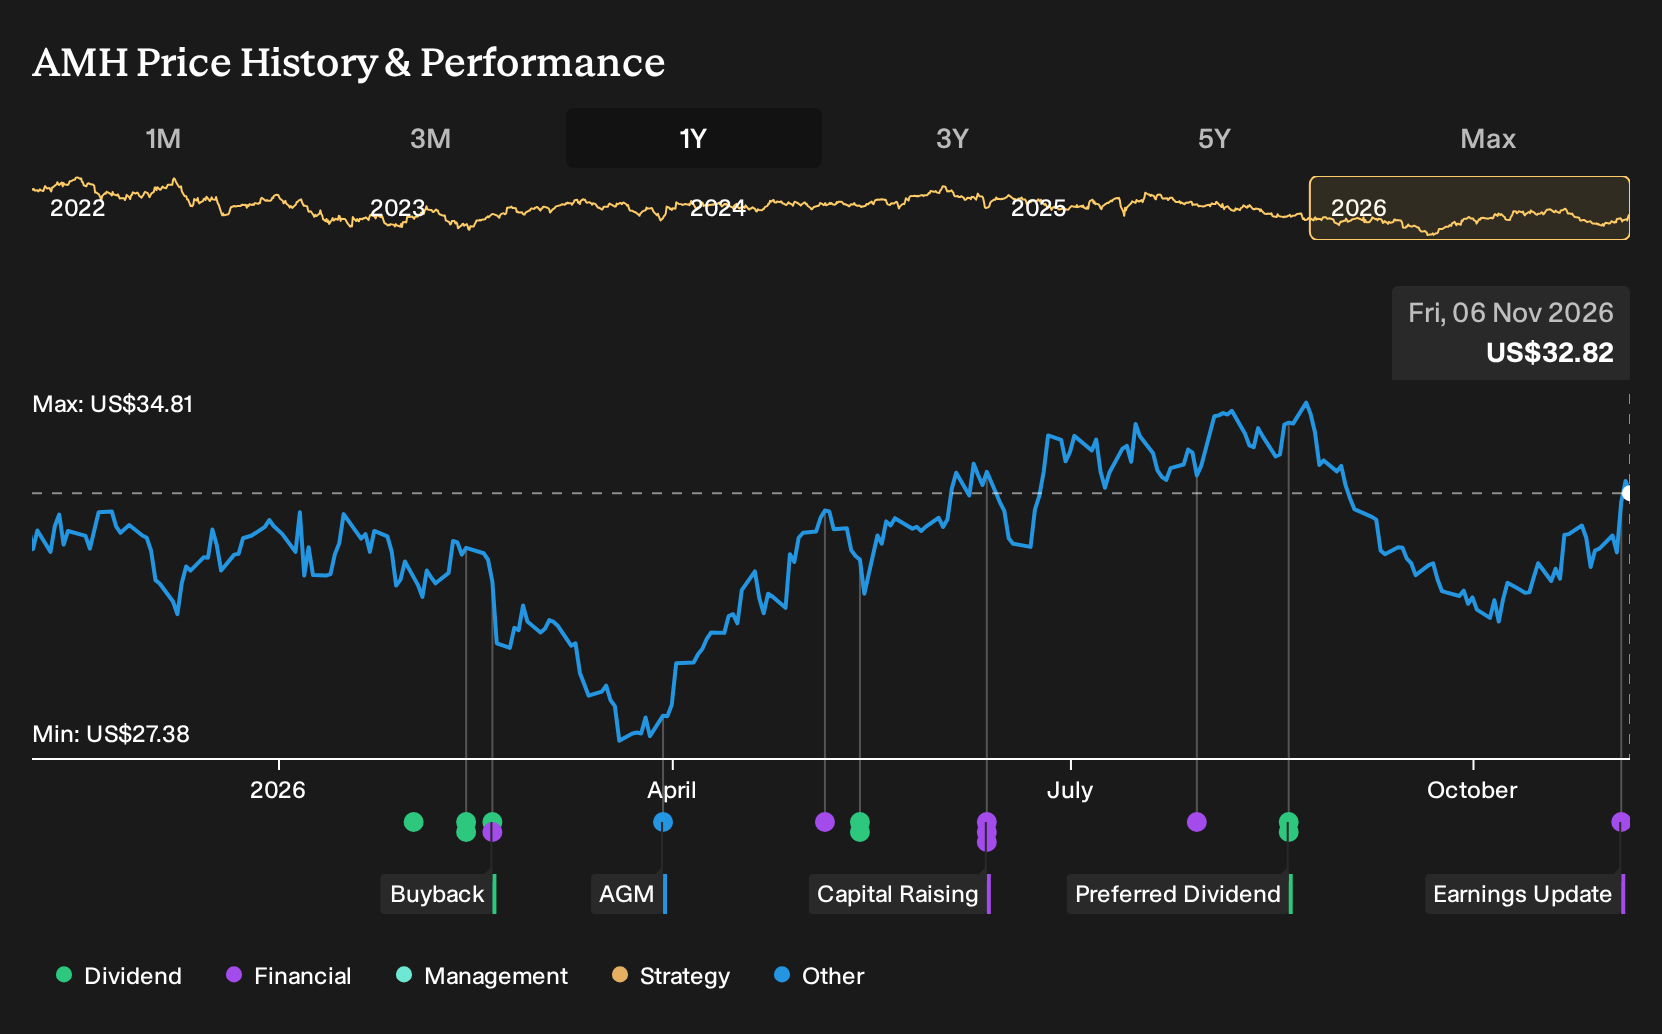
The fresh earnings release for the quarter and nine months to 30 September 2026 is the clearest recent data point to line up against those catalysts. Sales of US$498.07 million in the quarter and US$1.44b year to date, alongside net income of US$85.8 million and US$334.17 million, give you a snapshot of how the portfolio is currently converting rent into profit.
Basic and diluted EPS from continuing operations of US$0.23 for the quarter and US$0.89 for the first nine months sit against analyst expectations that earnings could decline on a multi year view. For a shareholder, the operational question now is whether American Homes 4 Rent can keep using development yields, lease expiry management and portfolio optimization to support funds from operations while managing interest costs and any pressure on single family rental markets such as Texas, Florida and Phoenix.
American Homes 4 Rent's narrative projects US$2.1b revenue and US$218.8 million earnings by 2029. That outlook lines up with analysts using a 3.8% yearly revenue growth rate and assuming earnings decline from US$463.5 million today to US$218.8 million, a drop of about US$244.7 million from current earnings.
Uncover why American Homes 4 Rent's fair value indicates a 13% potential upside to its current price before the market prices that gap away.
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community span roughly US$28.51 to US$52.88, so private investors are clearly not aligned on where American Homes 4 Rent should trade. Consider that range alongside the risk of prolonged higher interest costs, as well as the potential catalyst of stronger joint venture development, then explore several contrasting viewpoints before forming your own stance.
Explore 3 other American Homes 4 Rent fair value estimates, including one that suggests as much as 61% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your American Homes 4 Rent research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for American Homes 4 Rent. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Homes 4 Rent's overall financial health at a glance.
Looking for more investment ideas beyond American Homes 4 Rent?
Once you have a view on American Homes 4 Rent, it helps to widen the lens and compare it with other businesses that share some of the same qualities or risks. A focused screener can surface candidates that fit your preferences on valuation, balance sheet strength or income reliability in a fraction of the time it would take to sift through tickers manually.
- For investors who care most about strong fundamentals and low leverage, start with a list of solid balance sheet and fundamentals (25 results) that highlights companies with sturdier financial footing than the average stock.
- If your priority is paying a reasonable price for quality, put together a watchlist from a 39 high quality undervalued stocks that filters for businesses where fundamentals and market price appear out of sync.
- Income focused readers who want yield plus resilience can scan a 7 dividend fortresses that concentrates on companies aiming to combine higher payouts with more robust financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com