


China’s factory gate inflation has picked up speed, while consumer prices stay muted. That mix keeps pressure on producers and can unsettle global supply chains, which often leads investors to pay closer attention to hard cash coming through the door rather than headline earnings stories. This article looks at three Canadian stocks where current cash flows suggest a lower price than our fair value estimates, and why that gap matters for you.
The three Canadian stocks covered next are only a small sample from this cash flow focused idea, and the full screen on Simply Wall St has surfaced 0 more companies that share similar valuation gaps and stories that are not detailed below.
If you want to identify and analyze more potential value opportunities built on discounted cash flow work, head straight into the Undervalued Stocks Based On Cash Flows screener
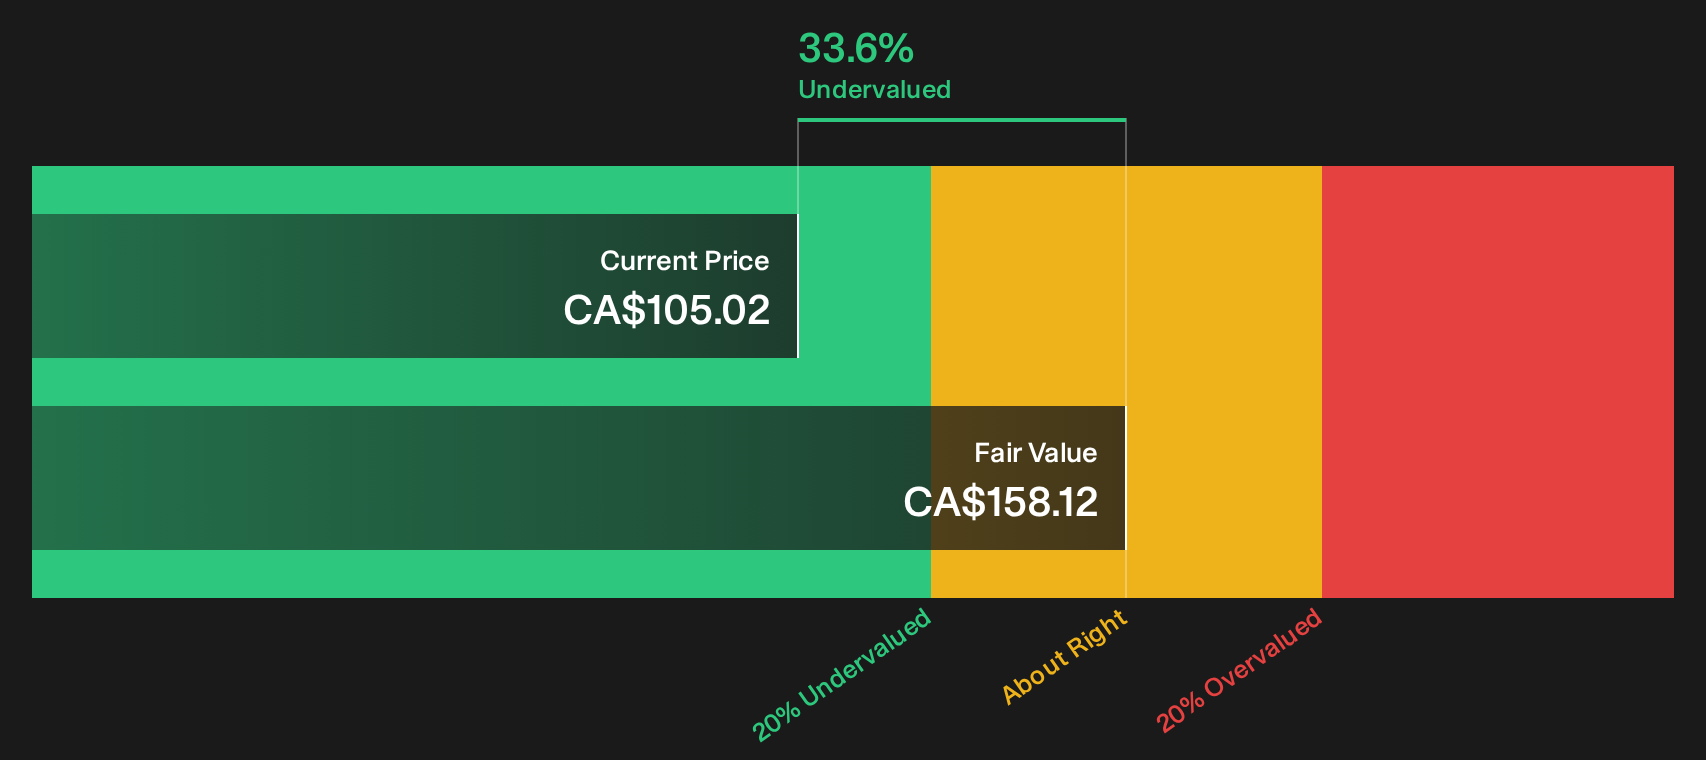
Stantec (TSX:STN)
Stantec is a global design and engineering group focused on infrastructure, water, buildings and environmental projects, where long term, contract based work feeds directly into the cash flow story that puts it in this screener.
Stantec runs fee based consulting and project management services for infrastructure, water systems, buildings and energy projects, generating about CA$3.6b from the United States, CA$1.7b from its global segment and CA$1.6b from Canada, and carries a market value of roughly CA$11.8b.
The analyst consensus Narrative on Simply Wall St highlights how Stantec’s long dated project pipeline links back to that cash flow angle for patient investors.
Demand for infrastructure upgrades, water and wastewater treatment, energy transition and climate adaptation projects remains very strong globally. This is reflected in double digit organic growth in Water across multiple regions and a record contract backlog of about $9.2b, which points to an extended runway for net revenue and earnings growth as multi year projects are executed.
What happens if one quiet pressure point starts to change how much of that backlog actually drops through to future margins?
If that pressure on margins is what you are watching, read the full narrative for Stantec to see how Stantec’s cash flows, backlog and valuation could be decoupling.
Green Thumb Industries (CNSX:GTII)
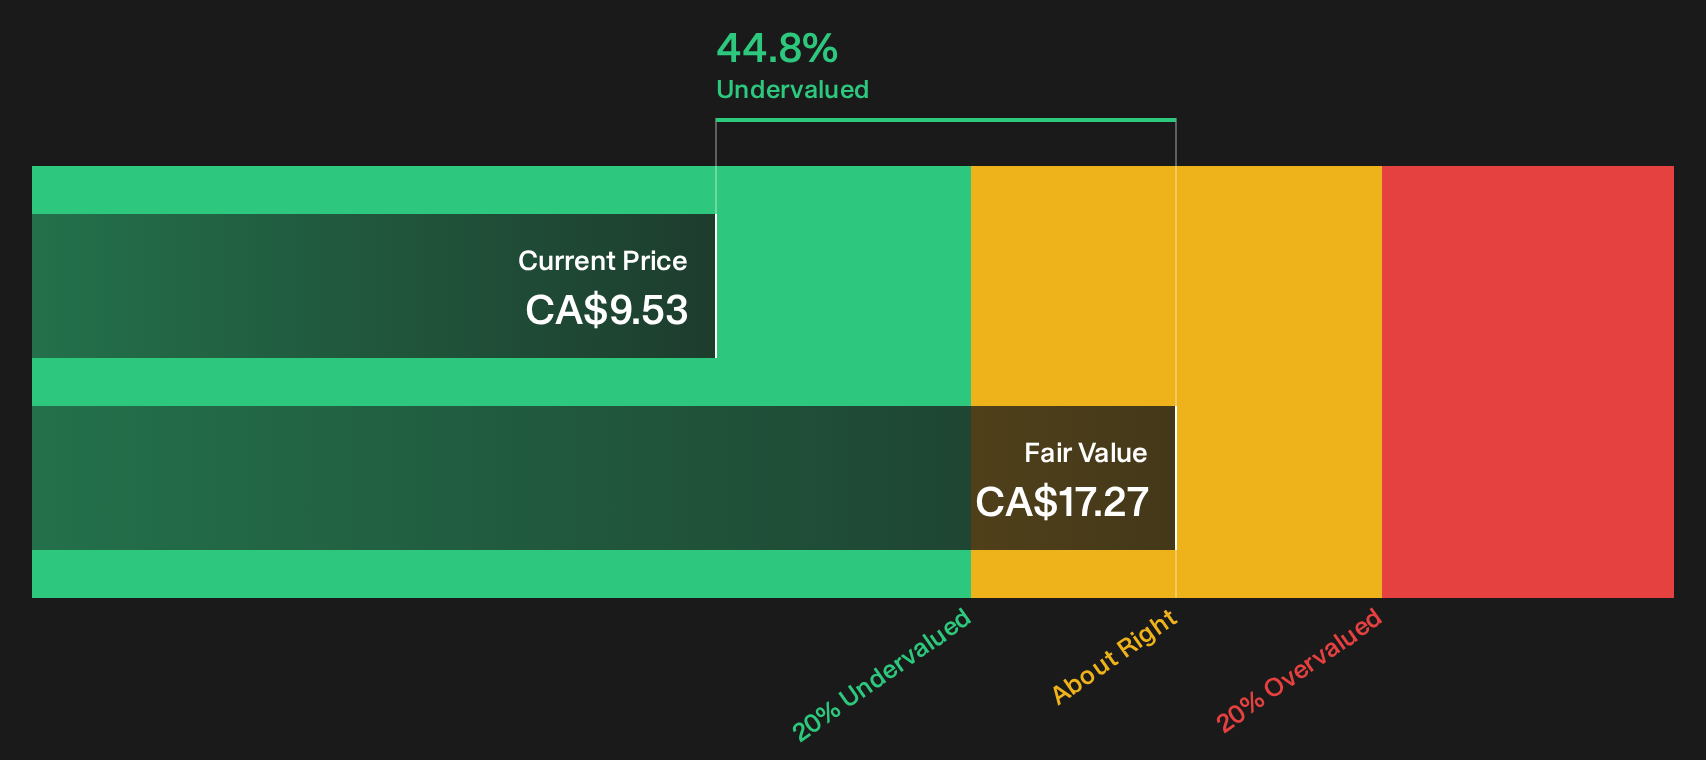
Green Thumb Industries is a vertically integrated US cannabis group, and the bullish analyst Narrative on Simply Wall St points to its branded Consumer Packaged Goods engine as the key cash generator behind the discounted cash flow story, with the stock valued by the market at about CA$2.1b.
Continued federal rescheduling progress and Green Thumb Industries’ DEA registrations for medical operations create scope for lower effective tax rates and cheaper financing over time, which could lift net margins and earnings power beyond what current models assume.
What happens if that one moving regulatory variable changes how investors value every future dollar of CPG driven cash flow?
That hinge on future tax and financing makes the full narrative for Green Thumb Industries the place to see how Green Thumb Industries’ cash engine could accelerate or stall next.
AGF Management (TSX:AGF.B)
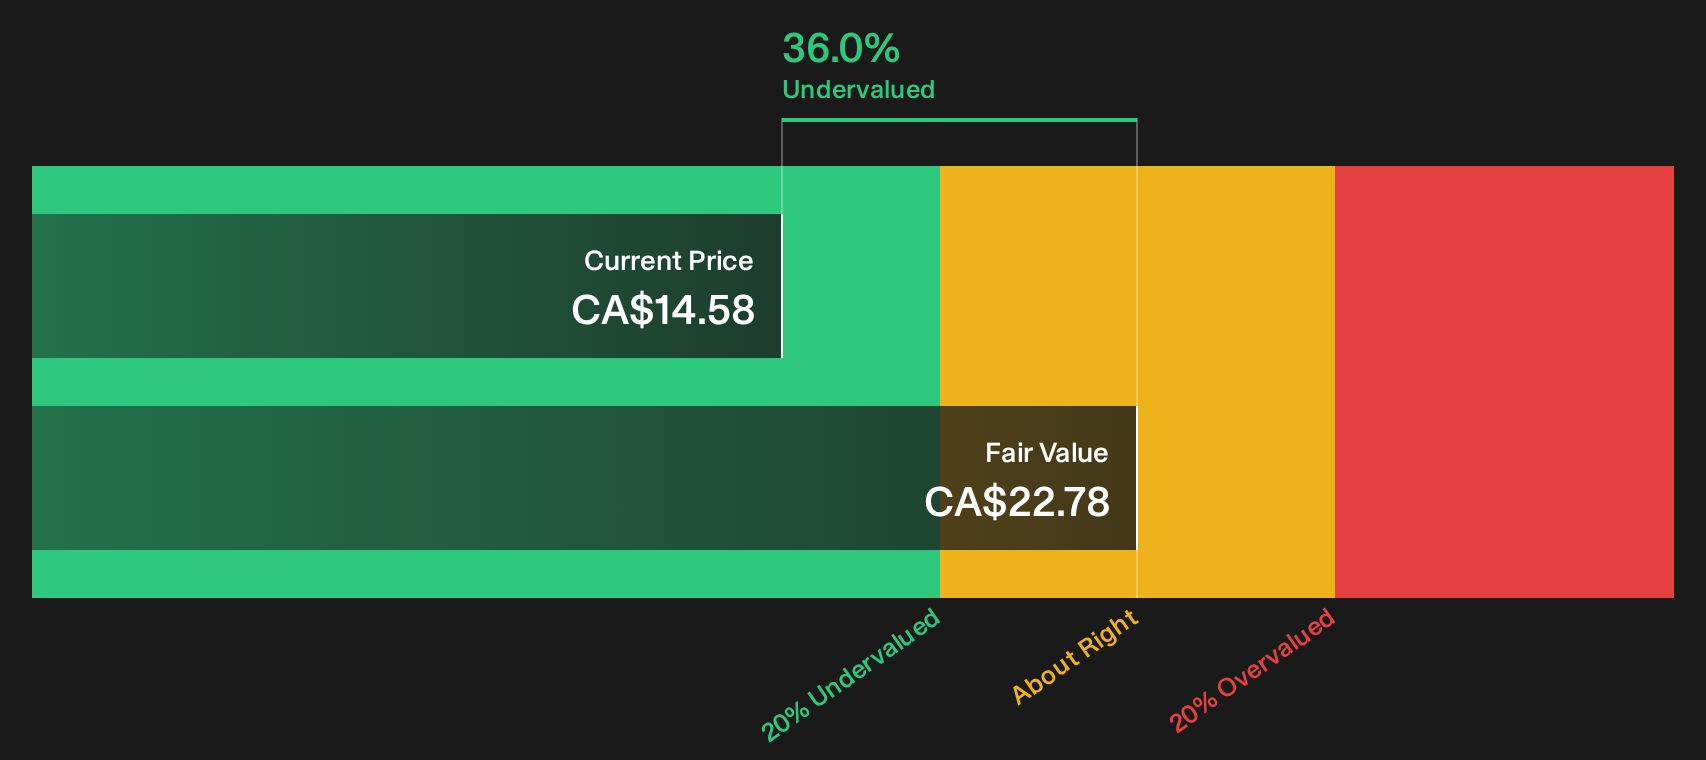
AGF Management runs a broad wealth platform built around mutual funds, ETF and SMA portfolios, and private investment mandates, where fee based asset management is the main cash engine. That recurring revenue focus helps anchor its place in a cash flow driven value screen.
AGF Management earns about CA$612 million from asset management related activities, serving investors across mutual funds, portfolios and private wealth solutions, and the stock carries a market value of roughly CA$931 million.
The analyst consensus narrative on Simply Wall St frames AGF Management as a business leaning into higher fee ETF and SMA assets. The company is using that shift to reinforce the cash flow profile that underpins this undervalued on cash flows theme.
AGF Management is expanding its ETF and SMA platform, with assets in these vehicles reaching $5.5b and growing across Canada, the U.S. and Asia.
What happens to that cash flow story if one moving piece in AGF Management’s fee mix quietly changes how much economics actually reach the bottom line?
That fee shift is exactly where the story can change, and the full narrative for AGF Management shows how AGF Management’s economics could be accelerating or quietly capped.
Seeking Fresh Alternatives Before They Fly
Markets move fast and the next breakout ideas rarely stay under the radar for long. Scan fresh watchlist candidates before momentum gets fully caught by the crowd. Act now.
- Spot sturdier compounders by filtering for balance sheets that can absorb shocks using the curated list of solid balance sheet and fundamentals (5 results) while it still feels under the radar for now.
- Shift your income watchlist toward payouts built on stronger foundations by running the curated 3 dividend fortresses before the highest yields get repriced by momentum buyers.
- Position ahead of the next infrastructure and electrification wave by checking the hand picked 41 power grid technology and infrastructure stocks while pricing dislocations still matter for entry points.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com