


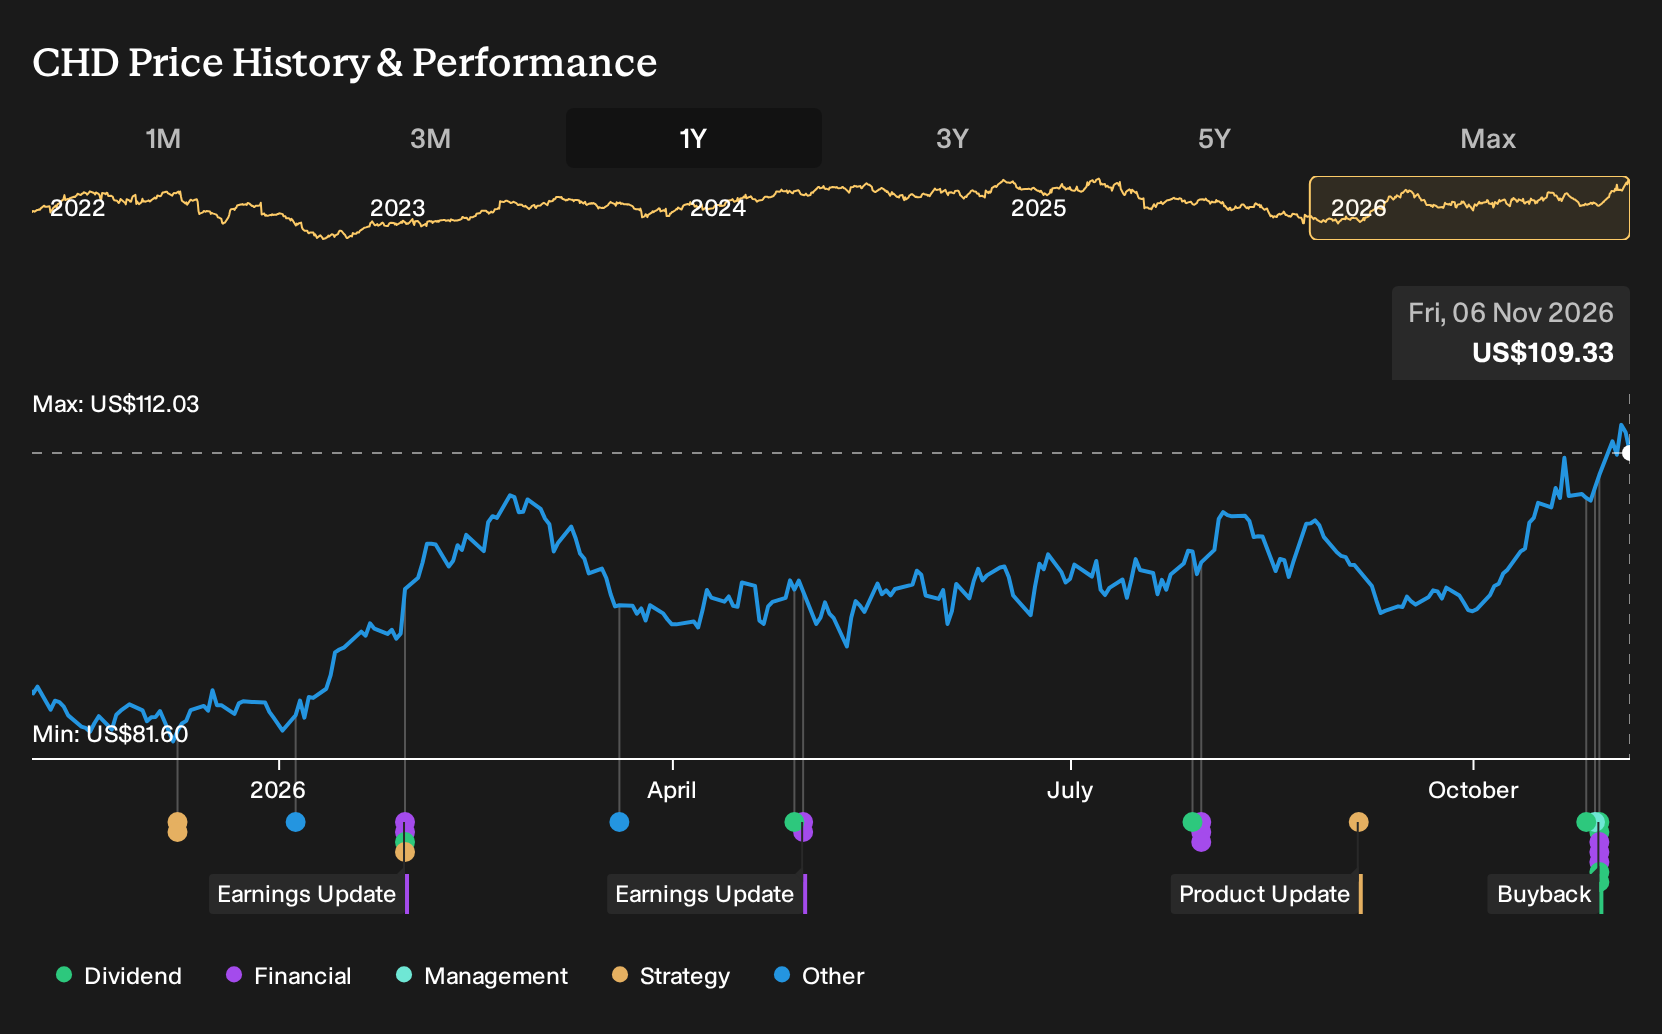
- Church & Dwight reported third quarter 2026 sales of US$1,602.1m and net income of US$212.2m, alongside full year guidance that points to about 0.5% net sales growth and an expected EPS of US$3.63.
- The board also approved a new US$1b share repurchase plan with no expiry date, which gives Church & Dwight added flexibility in how it returns cash to shareholders over time.
- We will now look at how Church & Dwight's stronger earnings and fresh US$1b buyback authorization could reshape its investment narrative.
Compare how Church & Dwight's latest earnings jump, buyback plan and steady dividend stack up against a curated group of companies in the 31 resilient stocks with low risk scores.
Church & Dwight Investment Narrative Recap
To own Church & Dwight, you need to believe the consumer health and household portfolio can keep compounding steadily while SG&A and underperforming categories are kept in check. The analyst consensus Narrative on Simply Wall St leans on growing online sales, brand expansion and modest earnings growth. The latest quarter fits that script, although guided Q4 sales softness tied to prior portfolio pruning keeps near term revenue momentum muted.
The key near term swing factor is margin delivery while vitamin gummies and multivitamins remain under pressure and SG&A sits above the evergreen model. Q3 EPS strength and full year EPS guidance of US$3.63 support that margins are holding up. The main risk is that higher costs and weaker categories offset the benefits from e commerce, wellness brands and product launches.
The fresh US$1b share repurchase authorization is the announcement that most connects with this earnings update. Management is pairing EPS guidance of about 20% growth for 2026 with a long dated buyback pool funded by cash generation and balance sheet capacity. That combination concentrates attention on cash conversion, not just accounting profit.
For you as a holder or potential holder, this plan tightens the link between execution on brands like THERABREATH, HERO and TOUCHLAND and per share metrics over time. It also raises the bar on capital allocation discipline. If SG&A and underperforming segments drag on returns, buybacks may not offset those pressures. If the operating plan tracks guidance, repurchases can reinforce EPS progress alongside the regular dividend.
Analysts currently model Church & Dwight reaching about US$7.0b in revenue and US$1.0b in earnings by 2029. This builds on forecast yearly revenue growth of 3.7% and an earnings increase of roughly US$225m from current earnings of about US$774.8m.
Uncover why Church & Dwight's fair value aligns with its current price.
Exploring Other Perspectives
One alternative angle on Church & Dwight focuses on capital deployment as a powerful upside catalyst. The most optimistic analysts were already penciling in about US$7.0b of revenue and US$1.1b of earnings by 2029, assuming a P/E of 31.2x. The fresh US$1b buyback and updated guidance could lead those views to shift, so it makes sense for you to compare several narratives rather than rely on a single storyline.
Explore 3 other Church & Dwight fair value estimates, including one that suggests as much as 22% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own independent analysis and instincts.
- A great starting point for your Church & Dwight research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Church & Dwight. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which can help you evaluate Church & Dwight's overall financial health at a glance.
Looking for more investment ideas beyond Church & Dwight?
If Church & Dwight has sharpened your focus on quality, it can help to widen the lens and compare it with other listed businesses that share similar strengths or offer something very different for your portfolio.
- For investors who want potential upside paired with balance sheet strength, scan a curated list of solid balance sheet and fundamentals (25 results) that meet strict financial resilience criteria.
- If value is your priority, weigh Church & Dwight against a 39 high quality undervalued stocks that combine quality fundamentals with prices that some investors may view as appealing.
- Income focused investors can round out their watchlist by checking a 7 dividend fortresses that aim to offer higher yields with a focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com