


With the European Central Bank contender Klaas Knot signalling a firm stance on keeping bond markets orderly, income seekers are paying closer attention to reliable cash payouts. Stable borrowing conditions matter for UK dividend stocks because they can help companies plan their financing and shareholder returns with more confidence. This article walks through three high-yield British dividend payers from our list, each offering more than a 3% income stream.
The three stocks highlighted here offer a compelling starting point if you want exposure to well covered, growing and stable dividend payouts above 3%. However, if you want the strongest names, these 4 dividend aristocrats stocks are the top of the list.
RHI Magnesita (LSE:RHIM)
RHI Magnesita is central to this Dividend Powerhouses theme because its refractory products and services support heavy industries that typically rely on long running, cash generative operations, and the analyst consensus Narrative on Simply Wall St frames that steady industrial footing as key to its income appeal.
RHI Magnesita develops refractory materials and services for high temperature industries, with regional revenue spread across North America (€852 million), Europe & CIS (€693 million), Latin America (€532 million), India (€422 million), China & East Asia (€368 million), META (€339 million) and Minerals (€78 million), and the group carries a market value of about £1.29b.
"The company's leadership in developing circular economy solutions via new recycling infrastructure is still intended to attract more ESG focused customers and reduce raw material cost exposure. This can support both sales volumes and gross margins as recycling usage increases."
Dividend investors will be watching how one pressure on future profitability plays out, because it could heavily sway the long term income story.
That pressure point is only half the picture, and the full narrative for RHI Magnesita lays out how RHI Magnesita’s recycling push, capital needs and payout ambitions could be quietly decoupling.

Man Group (LSE:EMG)
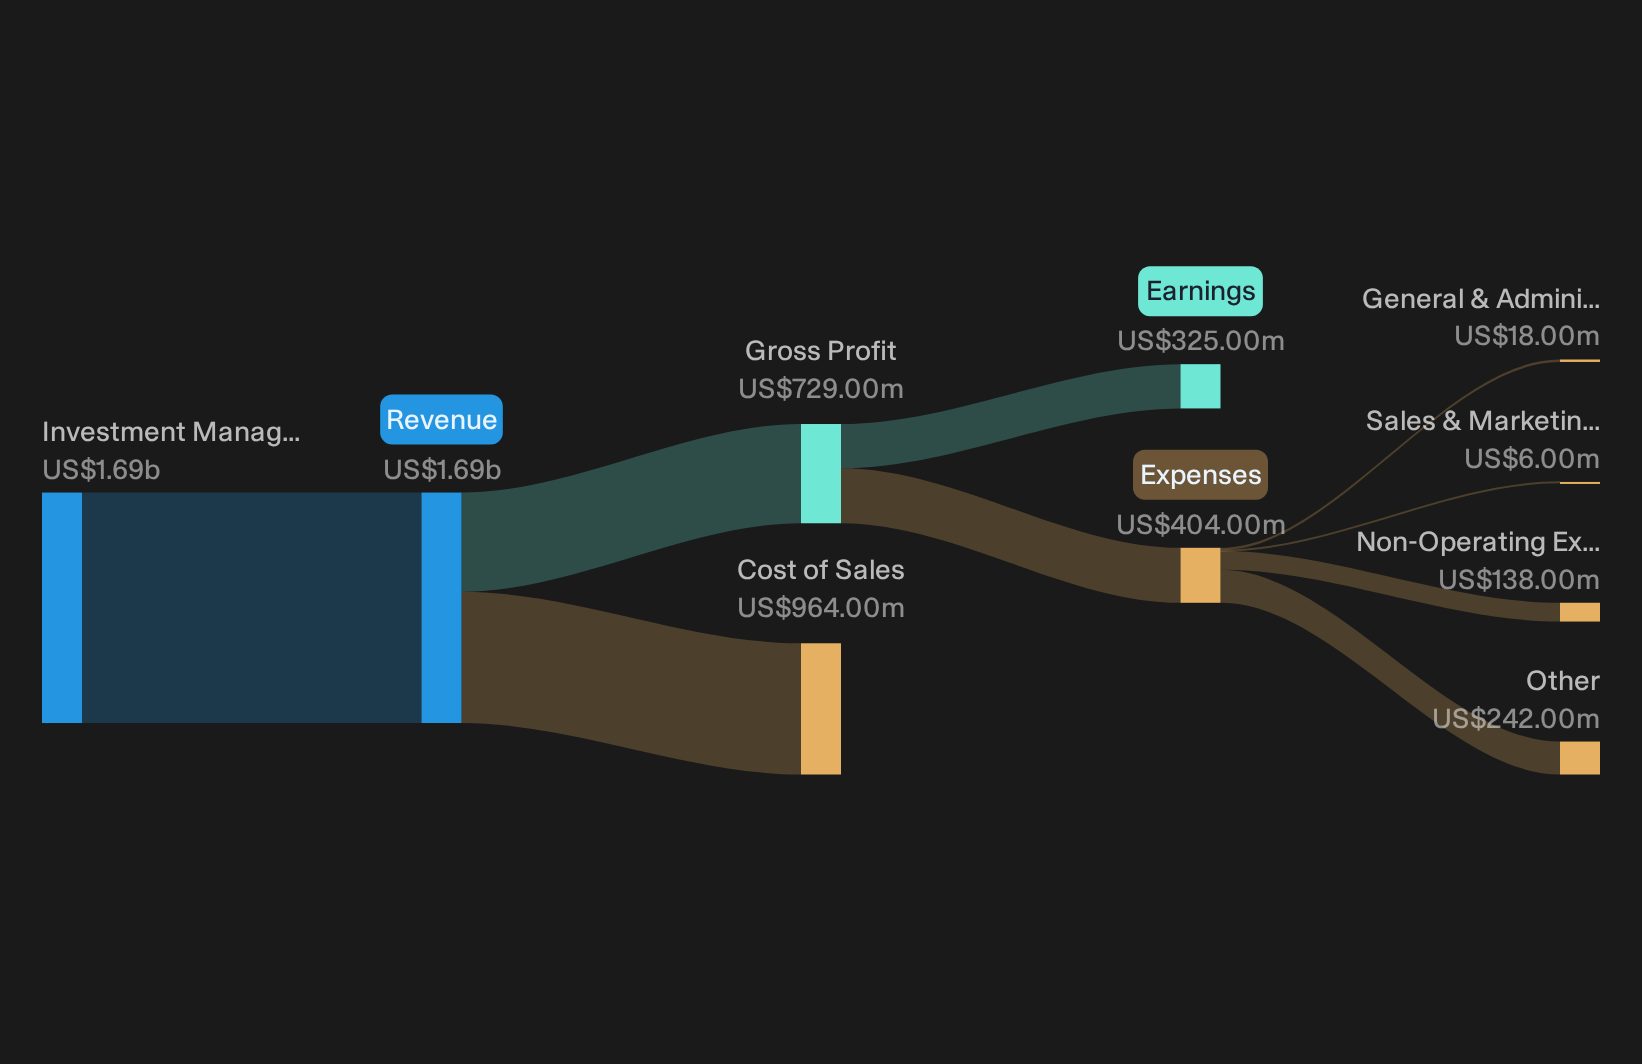
Man Group plugs into the Dividend Powerhouses theme through its regular cash payouts, which are backed by fee income from a broad investment management franchise rather than one-off events. The analyst consensus Narrative on Simply Wall St argues that this recurring engine is still underappreciated.
"Continued build out of the credit and private credit platform, including over $60b of credit AUM and $17.6b in private credit by mid 2026 plus $4.9b of uncalled committed capital, gives scope for further deployment that can support fee revenue and diversify profit drivers."
The real swing factor for Man Group’s dividend comfort is what happens if one unseen pressure on its fee margins starts to bite.
If that margin squeeze does start to build, the full narrative for Man Group shows how Man Group’s fee mix, capital return and credit build out could keep the story accelerating.
OSB Group (LSE:OSB)
OSB Group is a specialist mortgage lender whose buy to let, residential and development loans generate the interest margin cash flows that connect it directly to the 3%+ Dividend Powerhouses theme, with £421.8 million of revenue from OneSavings Bank, £233.9 million from Charter Court and a market value of about £1.7b.
For income investors, OSB Group matters because its specialist lending engine helps underpin dividend coverage, and the analyst consensus Narrative on Simply Wall St argues that the real story now sits in how its technology program reshapes costs, margins and capital returns.
"OSB Group's ongoing cloud, data and AI transformation program is on time and on budget, with about £85m still to be invested through 2027. Core operating costs already edged down 0.4% year on year in H1 2026 even as transformation expenses rose. This points to further potential improvement in cost to income ratios and net margins as more of the benefits flow through earnings."
The real test for those future payouts is what happens if one unseen pressure on its funding costs collides with this improving efficiency story.
If that funding squeeze worries you, the full narrative for OSB Group explains in detail how OSB Group’s margin pressures, tech spend and capital return plans could still be quietly accelerating the income story.

Seeking Alternatives Before The Crowd?
Fresh opportunities do not stay quiet for long. By the time momentum headlines hit, the early entry window can be gone. Scan these ideas now and consider moving before conditions change.
- Identify income engines that aim to keep paying even when headlines turn noisy by reviewing a curated group of 4 dividend fortresses while it still flies under the radar for now.
- Track where infrastructure demand could build by scanning the hand picked 41 power grid technology and infrastructure stocks before later capital reacts to already extended moves.
- Explore early movers in a niche many investors overlook by filtering through the curated 33 best rare earth metal stocks while prices may still be developing into potentially attractive ranges.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com