


China’s energy and resource producers sit in a strange cross current right now, with factory gate prices heating up through a 5.7% PPI while consumer inflation stays muted at 0.7%. That mix can punish some sectors and create sudden pricing power for others. If you care about owning the right side of that squeeze, this piece walks through three Chinese stocks exposed to these forces and explains why the current setup matters for your portfolio.
The stocks covered below are just a starting sample, and the wider screen surfaced 62 more Chinese energy and resource producers with equally detailed stories that are not unpacked in this article.
Head straight to the Chinese Energy & Resource Producers screener to identify, compare, and analyze the highest conviction plays for your own watchlist.
Anhui Hengyuan Coal Industry and Electricity PowerLtd (SHSE:600971)
Anhui Hengyuan Coal Industry and Electricity PowerLtd is an upstream Chinese coal producer focused on mining, washing, processing, and selling various coal grades into power, metallurgy, petrochemical, and building materials demand. The stock sits firmly in the coal-focused slice of this energy and resource screen and is valued at about CN¥8.68b by the market.
Anhui Hengyuan Coal Industry and Electricity PowerLtd gives you direct exposure to China’s upstream coal cycle at a time when PPI is elevated and input prices are in focus. Recent earnings and buyback activity indicate improving profitability, yet returns still depend on how one unseen pressure shapes coal pricing power and operating margins.
That hidden pressure is exactly what sits behind the 3 key rewards and 1 important warning sign, so you can see what might really drive the next swing in Anhui Hengyuan Coal Industry and Electricity PowerLtd.
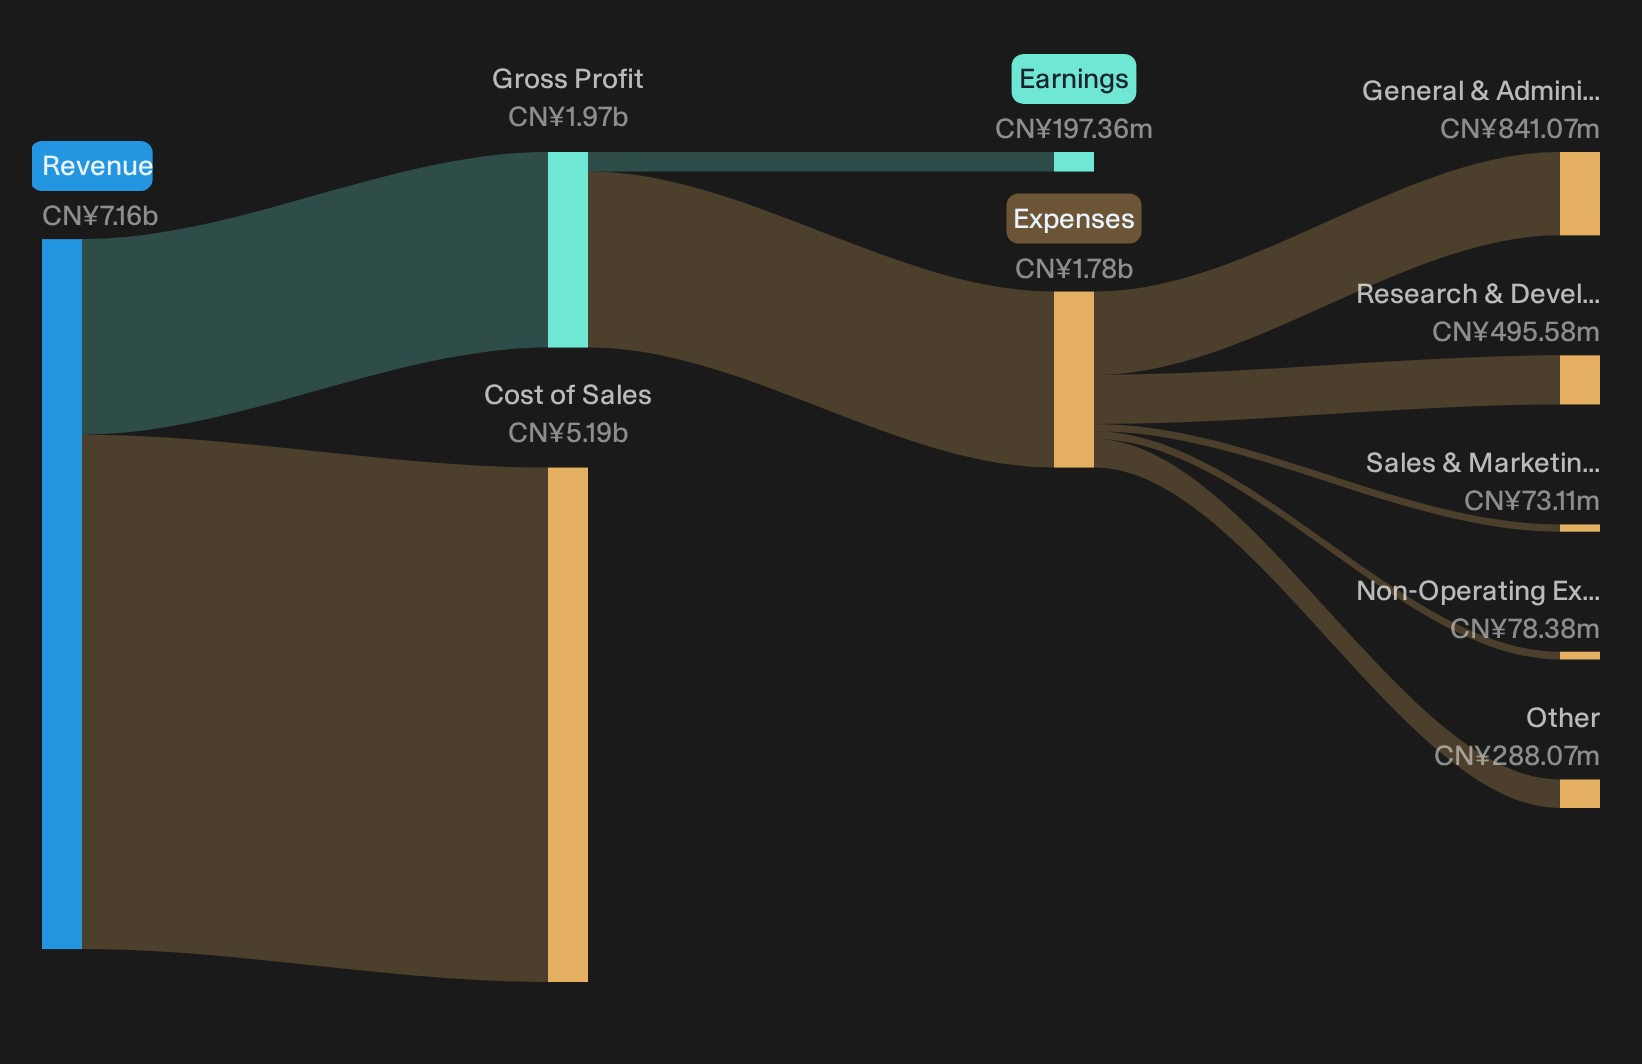
Huaibei Mining HoldingsLtd (SHSE:600985)
Huaibei Mining HoldingsLtd plugs directly into the Chinese Energy & Resource Producers theme as a large upstream coal and coal-chemicals group spanning mining, washing, processing, logistics, explosives, and power generation, with the stock valued by the market at about CN¥38b.
Huaibei Mining HoldingsLtd provides broad exposure to China’s coal chain at the point where higher PPI and firmer input prices feed into mining and processing profits. The business sits on the upstream side of the energy equation, which means earnings and cash generation depend heavily on the relationship between coal pricing momentum and its funding profile.
That funding hinge is exactly why investors check the 2 key rewards and 1 important warning sign to see where Huaibei Mining HoldingsLtd’s pricing power could decouple from its capital needs.

Kailuan Energy ChemicalLtd (SHSE:600997)
Kailuan Energy ChemicalLtd is a coal and coal chemicals producer operating mines, washing plants, coking assets, and downstream chemical facilities in China and overseas, tying it closely to the Chinese Energy & Resource Producers theme. The stock carries a market value of about CN¥8.54b.
Kailuan Energy ChemicalLtd provides direct exposure to upstream coal and coal chemicals at a time when China’s PPI is running at 5.7% and input prices are in the spotlight. Forecasted earnings acceleration, a low 0.4x P/S, and high financial leverage all move together, depending on how one unseen pressure plays out.
That pressure could be your edge, so check the analyst forecasts for Kailuan Energy ChemicalLtd to see whether accelerating expectations justify Kailuan Energy ChemicalLtd’s mix of low P/S and high leverage.

Seeking Alternatives Before The Crowd?
Fresh ideas do not wait. Breakout themes gain momentum, then get caught by the crowd. Use these under the radar for now screens while it matters and act now.
- Target income streams that can keep paying through cycles by scanning the curated 227 dividend fortresses before yields start dropping and the best candidates get fully priced.
- Hunt for underappreciated quality by running the curated 572 high quality undiscovered gems while these stories are still flying below most radars and pricing has not fully caught up.
- Sharpen your watchlist around resilience and capital protection using the focused 207 resilient stocks with low risk scores so you are positioned before money rotates toward sturdier balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com