


Amerant Bancorp (AMTB) has drawn fresh attention after trading around $29.60 per share, with recent performance data giving investors a new reference point for assessing this regional bank stock.
In the short term, momentum has cooled a little, with the share price return dipping over the past week. However, the 30-day share price return of 2.9% and year-to-date share price return of just over 50% sit alongside a 1-year total shareholder return of about 73%. This points to a story that has been building for a while, rather than a one-day move.
See how Amerant Bancorp compares with other regional lenders that have been hand-picked for resilient balance sheets and fundamentals in our list of solid balance sheet and fundamentals (25 results)
Amerant Bancorp now trades at a discount to both analyst targets and estimated fair value, even after this strong run. Is the market being appropriately cautious, or is it leaving too much on the table?
Most Popular Narrative: 7% Undervalued
Amerant Bancorp is trading at $29.60 against an analyst consensus fair value of about $31.88. That gap sits within a broader analyst consensus Narrative on Simply Wall St that ties together earnings forecasts, margins and capital use into a single valuation story.
Previously the focus was on loan growth and physical expansion to lift revenue and NII. Now the emphasis is on a cleaner balance sheet, more granular underwriting and lower criticized credits to support steadier credit costs and earnings.
See why 0 investors see Amerant Bancorp as 7% undervalued.
Result: Fair Value of $31.88 (UNDERVALUED)
Still, the narrative around Amerant Bancorp could shift quickly if credit costs stay elevated or if pressure on net interest income and margins persists.
Find out about the key risks to this Amerant Bancorp narrative.
Another View On Amerant Bancorp’s Valuation
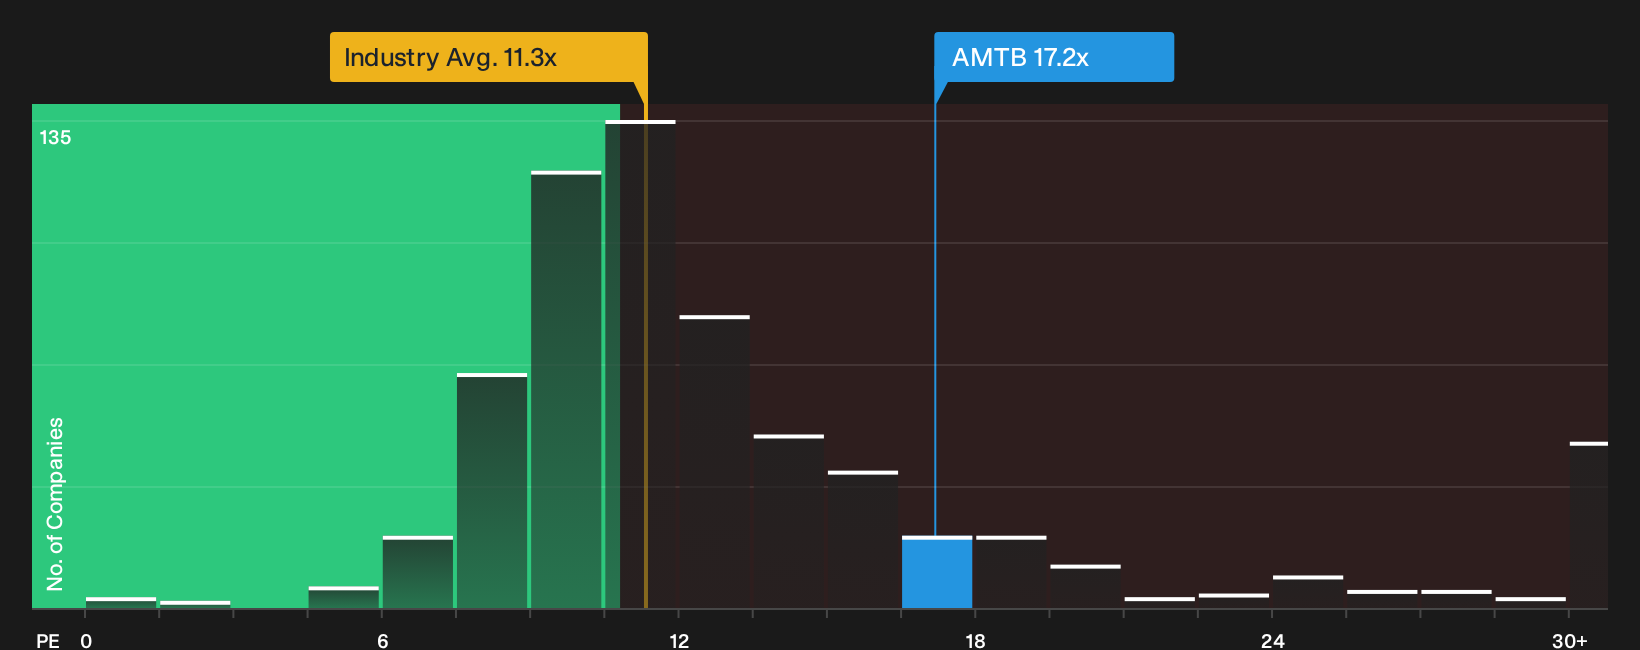
The analyst narrative tags Amerant Bancorp as about 7% undervalued on a fair value of $31.88. Yet on a simple P/E lens, the picture flips. The stock trades around 17.2x earnings, compared with 11.3x for both peers and the wider US Banks industry, and a fair ratio of 14.8x.
That richer earnings multiple suggests investors are already paying up versus both sector averages and the level the fair ratio points to. Investors may wish to consider whether this premium still feels comfortable if credit costs stay uneven or revenue growth trails the broader market.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Amerant Bancorp's valuation and risk profile can spark debate, so move fast, review the underlying numbers, and weigh the 2 key rewards and 2 important warning signs.
Looking for more Amerant Bancorp sized investment ideas?
If you only stick with Amerant Bancorp, you could miss other opportunities that fit your style. Put a shortlist together now using targeted screeners that surface stocks by quality, value and resilience.
- Zero in on quality at a discount and build a watchlist of potential bargains through the 40 high quality undervalued stocks.
- Prioritise resilience and aim to sleep easier at night by focusing on companies filtered through the 31 resilient stocks with low risk scores.
- Stay ahead of the crowd by finding underfollowed opportunities using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com