


Stronger payrolls, firm wage gains and a higher chance of future Fed rate hikes are reshaping the playing field for corporate credit right now. Shorter maturity and floating rate exposures sit closer to the action when borrowing costs and inflation expectations keep shifting. This article explains how that backdrop relates to three U.S. floating rate and short maturity corporate credit stocks that are linked to the latest jobs data, and why their positioning may be relevant for your portfolio decisions.
The three U.S. floating rate and short maturity corporate credit stocks in the list below are just a starting sample. The full screen on Simply Wall St surfaced 16 more companies with equally compelling credit narratives that are not covered here. To identify and analyze those additional ideas directly, head into the U.S. Floating-Rate and Short-Maturity Corporate Credit screener.
GCM Grosvenor (GCMG)
Overview: GCM Grosvenor is a Chicago based alternative asset manager that builds and runs funds across credit, private equity, real assets and hedge fund strategies, including floating rate and short duration corporate credit vehicles.
Operations: GCM Grosvenor generates about US$567 million of asset management revenue, almost entirely from clients based in the United States.
Market Cap: US$2.6b
GCM Grosvenor matters for this U.S. Floating-Rate and Short-Maturity Corporate Credit screen because its multi strategy platform channels client money into credit funds that can lean into floating rate or shorter duration exposure. The analyst consensus Narrative on Simply Wall St outlines how that model ties into fee potential.
"Persistent growth in alternatives allocations across institutional, insurance, and individual clients, together with expansion of GCM Grosvenor’s distribution teams in Europe, the Middle East, and Asia, is feeding a broad fundraising pipeline that can support higher management fees and fee-related revenue."
What investors watch now is how one unseen cost pressure interacts with that expanding fundraising engine to shape future fee margins.
That cost pressure is exactly where the story gets interesting. The full narrative for GCM Grosvenor lays out how fee growth, fundraising momentum and risks could be decoupling.

Capital Southwest (CSWC)
Overview: Capital Southwest provides credit and non control equity financing to lower and upper middle market businesses across North America, often via floating rate loans.
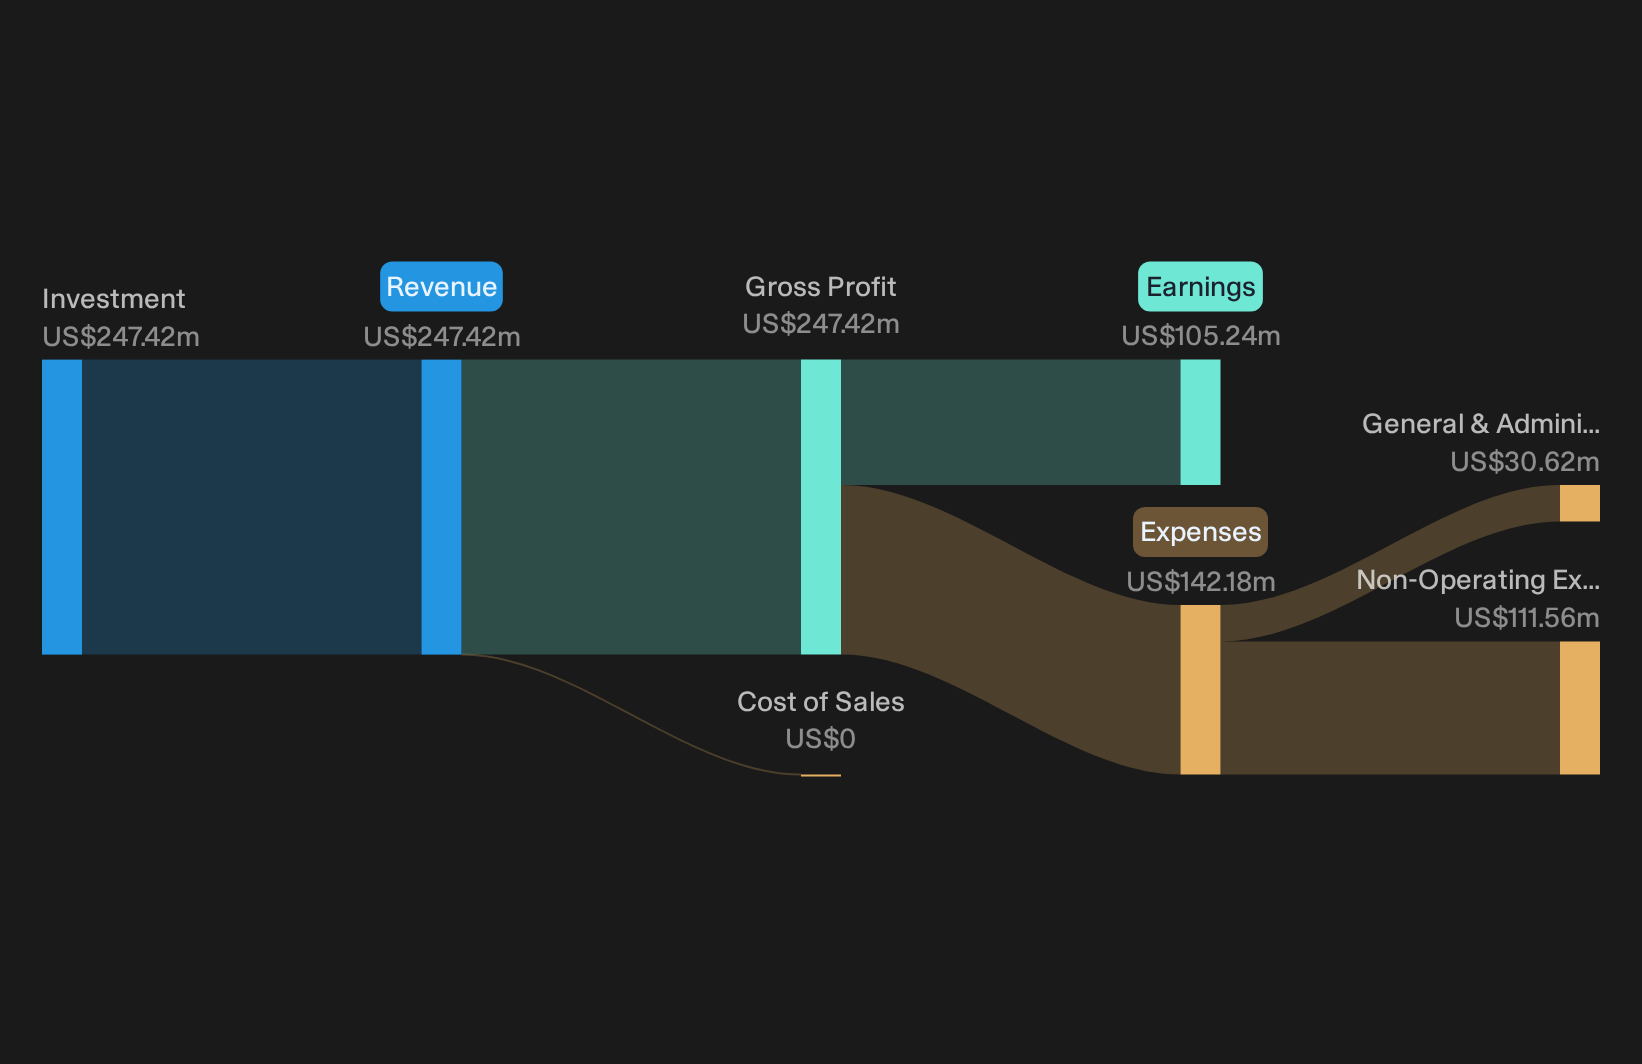
Operations: Capital Southwest generates about US$247 million of investment income, almost entirely from borrowers based in the United States.
Market Cap: US$1.5b
Capital Southwest matters for a U.S. Floating-Rate and Short-Maturity Corporate Credit screen because its middle market loan book leans toward shorter term and floating rate structures. The analyst consensus Narrative on Simply Wall St argues that the funding side is being built to match that opportunity.
"Expansion of low cost and flexible funding capacity, including an increased US$250 million SBA leverage commitment for SBIC II and a larger US$595 million corporate credit facility with a lower margin and longer maturity to 2031, gives Capital Southwest additional room to scale earning assets relative to its equity base and support net investment income."
What happens to that equation if one pressure point in the cost of money for lenders moves faster than asset yields can adjust?
If that funding squeeze is what you are worried about, the full narrative for Capital Southwest shows how Capital Southwest’s model could absorb shocks while keeping income momentum intact.
Hercules Capital (HTGC)
Overview: Hercules Capital is a business development company that provides floating rate and short term loans plus equity-linked financing to venture backed and emerging growth firms.
Operations: Hercules Capital generates about US$568 million of revenue from its lending and investment activities, primarily through structured debt.
Market Cap: US$3.0b
For a screener built around floating rate and shorter maturity corporate credit, Hercules Capital offers direct exposure to venture lending where many loans reset with short term rates. The analyst consensus Narrative on Simply Wall St highlights how that niche is tied to a growing pipeline of high growth borrowers.
"Sustained expansion in Hercules Capital's technology and life sciences verticals, reflected in record first half 2026 originations of US$2.74b and record fundings of US$1.35b, continues to support visibility on future total investment income and net investment income growth."
The real question is how one quietly rising funding cost pressure might influence that earnings visibility if conditions tighten further.
If that risk is what concerns you, the full narrative for Hercules Capital explains in detail how Hercules Capital’s funding costs, venture exposure and income potential might be quietly decoupling.

Curious About Credit Alternatives?
Fresh credit themes can move from quiet accumulation to full breakout before most investors notice. Scan what is flying or quietly dropping under the radar for now and consider your next steps.
- Track income ideas built around reliable cash flows and payout strength, starting with a curated set of 7 dividend fortresses that focus on durability as much as yield.
- Spot early momentum in real assets and monetary hedges by reviewing a filtered group of 34 elite gold producer stocks before the crowd chases the next spike.
- Scan powerful trends in automation and industry efficiency by working through hand picked 91 robotics and automation stocks that connect real-world adoption with listed opportunities.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com