


New York Times (NYT) is back in focus after its 3Q 2026 earnings, where higher revenue, net income and digital driven income trends, plus upbeat management commentary on future digital growth, have drawn fresh investor attention.
Recent trading around New York Times reflects that tension between strong digital earnings and valuation questions. The share price was up 4.25% on the day of the 3Q 2026 release and showed a 7.27% 90 day share price return, while the 3 year total shareholder return of 62.97% and 5 year total shareholder return of 49.63% point to momentum that has played out over a longer horizon rather than just this quarter.
Spot fresh momentum in New York Times, and then scan a curated group of similar media and digital subscription plays using our 19 high quality undiscovered gems.Bulls highlight The New York Times’ digital growth and its recent 3Q increase in performance. Bears point to strong past returns and potential margin risks. Which side does the current valuation math favor from here?
Most Popular Narrative: 11% Undervalued
New York Times closed at $68.36, while the analyst consensus Narrative on Simply Wall St points to a fair value of about $76.89, which frames the current setup through an 11.1% discount and a 9.18% discount rate.
The key thing that has to go right is that the company turns heavy investment in areas like video, technology and marketing into sustained engagement and monetization, without letting cost growth consistently outpace revenue.
The current valuation implies the share price does not fully reflect this narrative: that The New York Times is undervalued and that its subscription, advertising and cash flow profile could justify a higher multiple than the market is giving it credit for today.
See why 13 investors see New York Times as 11% undervalued.
Result: Fair Value of $76.89 (UNDERVALUED)
Still, the New York Times story can weaken if video spending erodes margins for longer than analysts model or if referral traffic from big platforms keeps shrinking.
Find out about the key risks to this New York Times narrative.
Another View: New York Times on Earnings Multiples
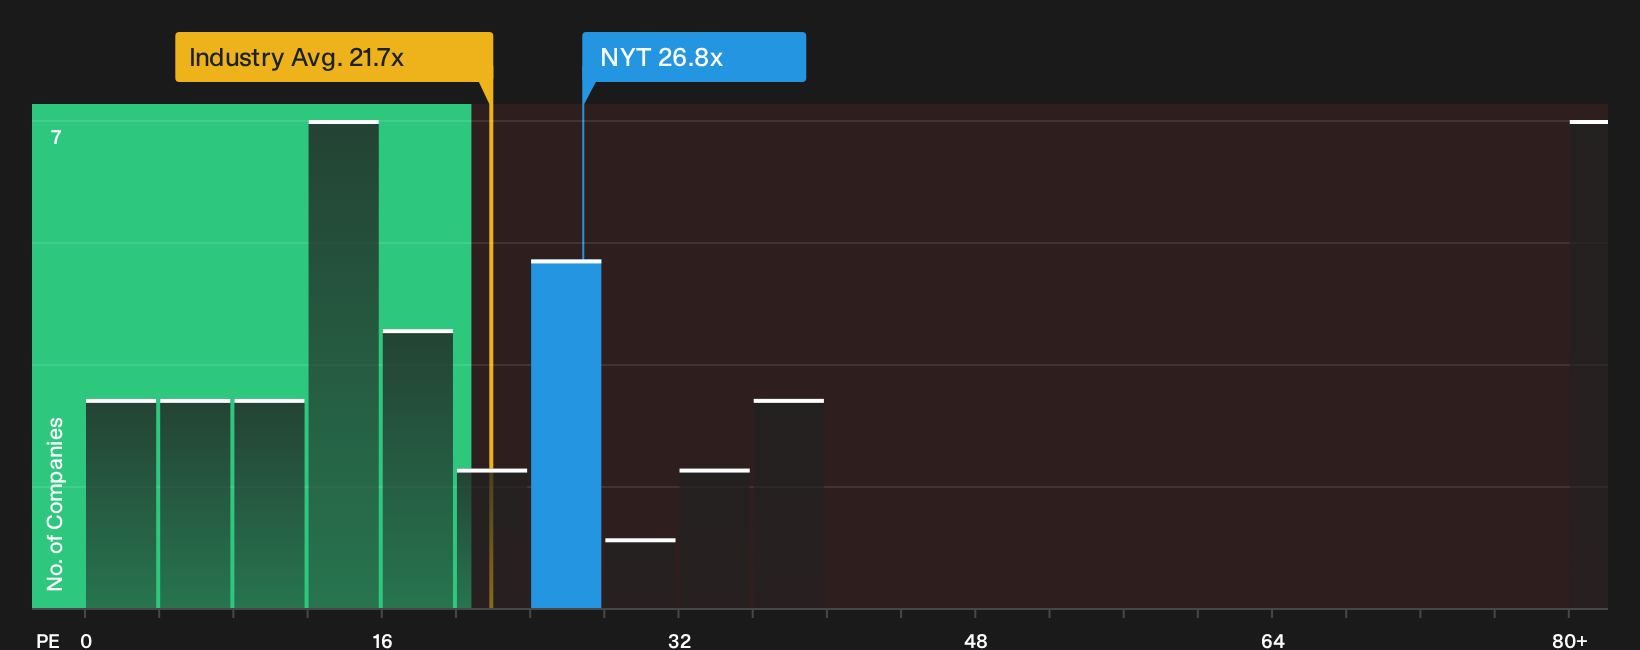
Our DCF work points to a small 2.3% discount to future cash flow value, yet the earnings multiple tells a different story. New York Times trades on a P/E of 26.8x, compared with a fair ratio of 18.3x, a peer average of 15x and a 21.7x industry level. That gap suggests investors are paying a clear premium. This raises the question of whether the market is overestimating how durable NYT’s growth and margins will be.
For a closer look at how this earnings multiple premium stacks up, and how it feeds into valuation risk, see the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages in the New York Times story so far, or mostly optimism with a few clear risks. Either way, act quickly, stress test the numbers yourself, and see how the positives stack up in the 3 key rewards.
Looking for more New York Times style investment ideas?
Do not stop with New York Times. Use the Simply Wall St Screener to spot fresh opportunities other investors might miss across quality, value and income ideas.
- Target resilient potential by scanning a 31 resilient stocks with low risk scores that can help you focus on businesses with steadier risk profiles.
- Hunt for mispriced quality using the 40 high quality undervalued stocks to see companies where fundamentals and current pricing may be out of sync.
- Strengthen your shortlist with a list of solid balance sheet and fundamentals (25 results) that highlights businesses backed by healthier financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com