


- Krones reported third quarter 2026 sales of €1,384.8 million and net income of €80.6 million, with basic EPS from continuing operations at €2.55.
- Over the first nine months of 2026, Krones kept sales close to prior year levels while lifting net income and basic EPS from continuing operations.
- We will now look at how Krones' higher earnings per share from continuing operations may influence the broader investment narrative.
Compare Krones' latest earnings trend with other industrial names that pair resilient profits with solid balance sheets by scanning the hand picked list of solid balance sheet and fundamentals (193 results) in just a few minutes.
Krones Investment Narrative Recap
To own Krones, you need to be comfortable with a story that leans on a large order backlog, ongoing local for local expansion and tight cost control, as set out in the analyst consensus Narrative on Simply Wall St. The latest quarterly report, with earnings per share from continuing operations moving to €2.55 for Q3 and €6.94 for the nine months, supports that profitability focus.
The key short term catalyst is still execution on the capacity investments in China and India, as well as higher local production in North America, while keeping working capital under control. The new figures help the margin narrative, but they do not remove the risk that elevated inventories and Netstal underperformance continue to weigh on cash generation.
Against that backdrop, the fresh Q3 and nine month numbers are the headline development investors are processing right now. Sales of €1,384.8 million in the quarter and €4,099.7 million for the first nine months, together with net income of €80.6 million and €219.4 million respectively, give a current read on how Krones is converting its backlog into earnings.
Those results intersect directly with the catalysts in the analyst consensus Narrative on Simply Wall St. This highlights structurally lower material cost ratios and tighter personnel spending as potential drivers for stronger EBITDA margins over time. The latest uplift in basic earnings per share from continuing operations, compared with the prior year periods, lines up with that margin story but still sits next to the risk that higher working capital keeps restraining near term free cash flow.
Krones' narrative projects €6.4b revenue and €361.6 million earnings by 2029. This implies 3.9% yearly revenue growth and an earnings increase of about €69.5 million from €292.1 million today.
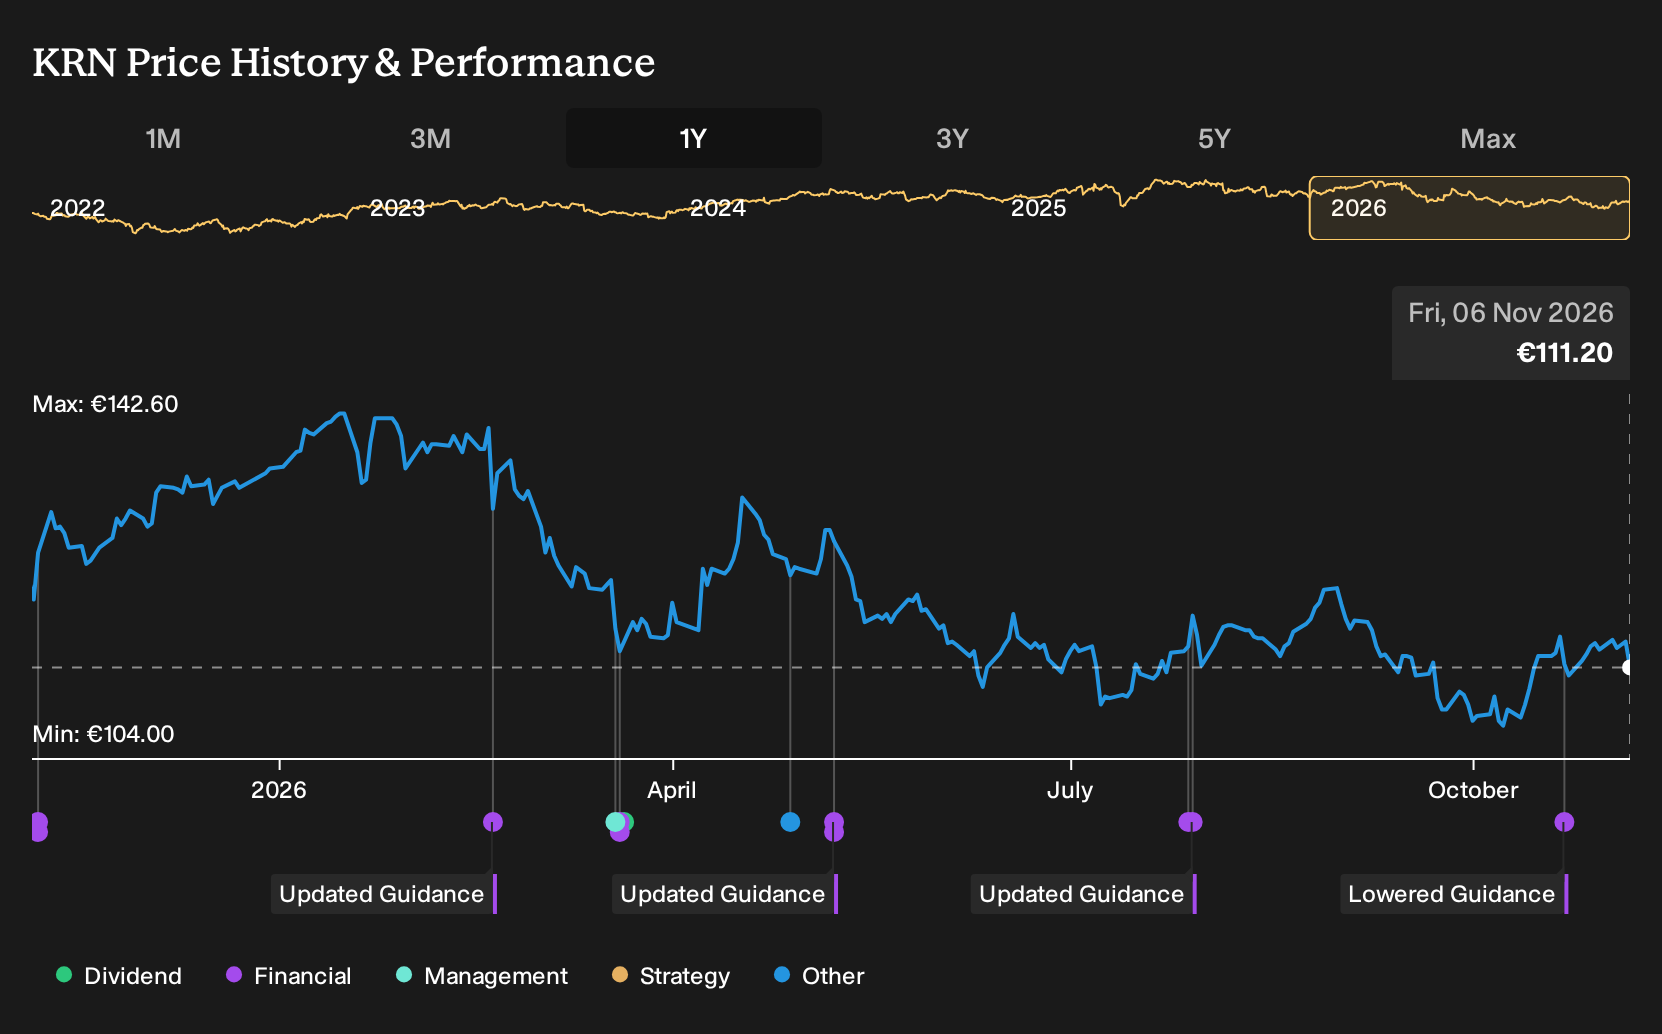
Discover why Krones' fair value points to a potential 28% upside from its current price before the market closes that gap.
Exploring Other Perspectives
One bullish twist on Krones focuses on that sizeable cash pile and broader liquidity, with some of the highest analysts assuming revenue of about €6.6b and earnings of €439.3 million by 2029. You are looking at a far more optimistic script that predates these Q3 results, which means those views could still shift meaningfully.
Explore 7 other Krones fair value estimates, including one that suggests up to 94% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Krones research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Krones. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Krones' overall financial health at a glance.
Looking For More Investment Ideas Beyond Krones?
If Krones has sharpened your thinking about quality, balance sheet strength and earnings power, it can be useful to compare it with other companies that share similar traits or offer something very different. The Simply Wall St Screener helps you do that quickly by lining up businesses that fit tight financial criteria, so you can focus your time on weighing the story, risks and valuation.
- For investors who want steadier compounding with fewer surprises, scan a curated set of companies that score well on resilience and risk using the 207 resilient stocks with low risk scores.
- If you are hunting for stronger income potential, filter for businesses with higher yields that still keep fundamentals in view through the 226 dividend fortresses.
- Those looking for future potential that is less crowded can focus on under followed stocks with solid financial footing by running the 572 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com