


Unitil earnings mix raises fresh questions for investors
Unitil (UTL) has just reported third quarter results that paired higher year over year sales with a net loss for the period, a combination that can reshape how investors assess the stock.
Unitil’s recent pattern tells a mixed story for momentum. The share price is up 7.9% over the past month and 15.1% year to date, while the 1 year total shareholder return of 22.9% suggests longer term holders have seen steadier gains, even as the third quarter loss and the late October dividend declaration temper short term enthusiasm.
Compare Unitil’s results with other regulated utilities by screening for 42 power grid technology and infrastructure stocks that may offer different mixes of earnings stability, dividends, and rate base exposure.
Unitil appears to be a solid regulated utility on paper, with electricity and gas operations across New England and a long-running dividend. After this latest quarter and the recent share price climb, is that quality already fully reflected in the valuation, or not?
Most Popular Narrative: 4% Overvalued
Unitil last closed at $56.38 against a fair value of $54.00 in the analyst consensus Narrative on Simply Wall St, a small premium that frames the stock as slightly ahead of that narrative view and puts more focus on the underlying assumptions.
The current valuation and this narrative’s view that Unitil is fairly valued and bullish imply that the share price already reflects steady 5% to 7% EPS growth, a growing dividend, and a low risk regulated utility profile.
See why 0 investors see Unitil as 4% overvalued.
The discount rate in that work is 7.24%, which is used to bring the analyst revenue and earnings forecasts back to today’s dollars. That figure helps you judge whether the implied 2029 revenue of $631.6 million and earnings of $73.5 million look reasonable relative to Unitil’s current $608.0 million of sales and $54.9 million of net income.
Those same forecasts assume an 11.6% profit margin and a P/E of 17.4x on 2029 earnings. The current price near $56 is not far from the $54.00 narrative fair value, so even small changes in those inputs, or in how investors feel about regulated utilities, could shift whether Unitil looks slightly expensive or slightly cheap on this framework.
Result: Fair Value of $54 (OVERVALUED)
Still, the whole Unitil story depends on regulators supporting that US$1.2b capital plan and on earnings actually matching the analyst profit and P/E assumptions.
Find out about the key risks to this Unitil narrative.
Another View: Unitil Through The Cash Flow Lens
The analyst narrative tags Unitil as slightly overvalued around $56.38 compared with a $54.00 fair value, yet the SWS DCF model points in a different direction. On that cash flow work, the shares sit about 5.9% below an estimated value of $59.93, which raises a simple question: Which yardstick do you trust more when the story is this tight?
Look into how the SWS DCF model arrives at its fair value.
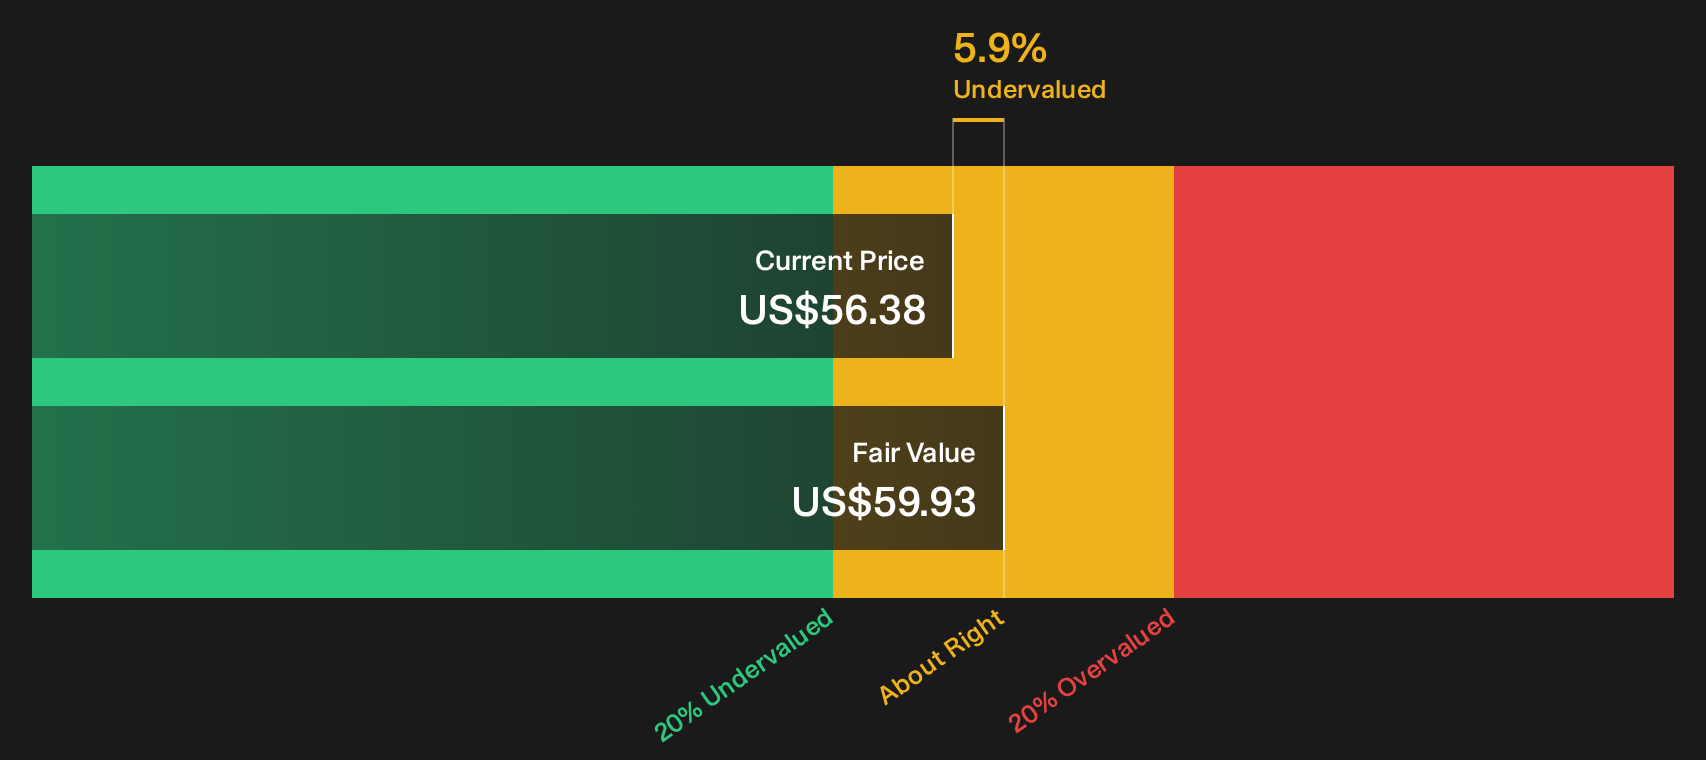
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Unitil for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 40 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around Unitil feels finely balanced, check the data for yourself and move fast to form your own view with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Unitil?
If Unitil has your attention, do not stop there. Broaden your watchlist with other opportunities that match your risk appetite and income goals.
- Target stronger balance sheets and sturdier cash flows by scanning a list of solid balance sheet and fundamentals (25 results) that highlights financially robust businesses.
- Hunt for mispriced opportunities by reviewing a focused 40 high quality undervalued stocks that combines quality metrics with attractive valuations.
- Build a steadier income stream by zeroing in on a curated 7 dividend fortresses featuring higher yielding companies with resilient profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com