


Stronger US jobs data has pushed interest rate expectations higher, which tends to reward companies that generate real cash rather than relying on cheap borrowing. For United Kingdom investors, that puts steady cash flow in the spotlight. When the share price of a solid cash generator sits below an estimate of its fair value, mispricing can appear. This article walks through three such opportunities from our cash flow focused United Kingdom value list.
The three stocks below are just a sample, with the full cash flow screen surfacing 20 more United Kingdom companies with equally compelling stories that are not covered here.
If you want to identify and analyze potential value ideas built around discounted cash flows, head straight into the Undervalued Stocks Based On Cash Flows screener
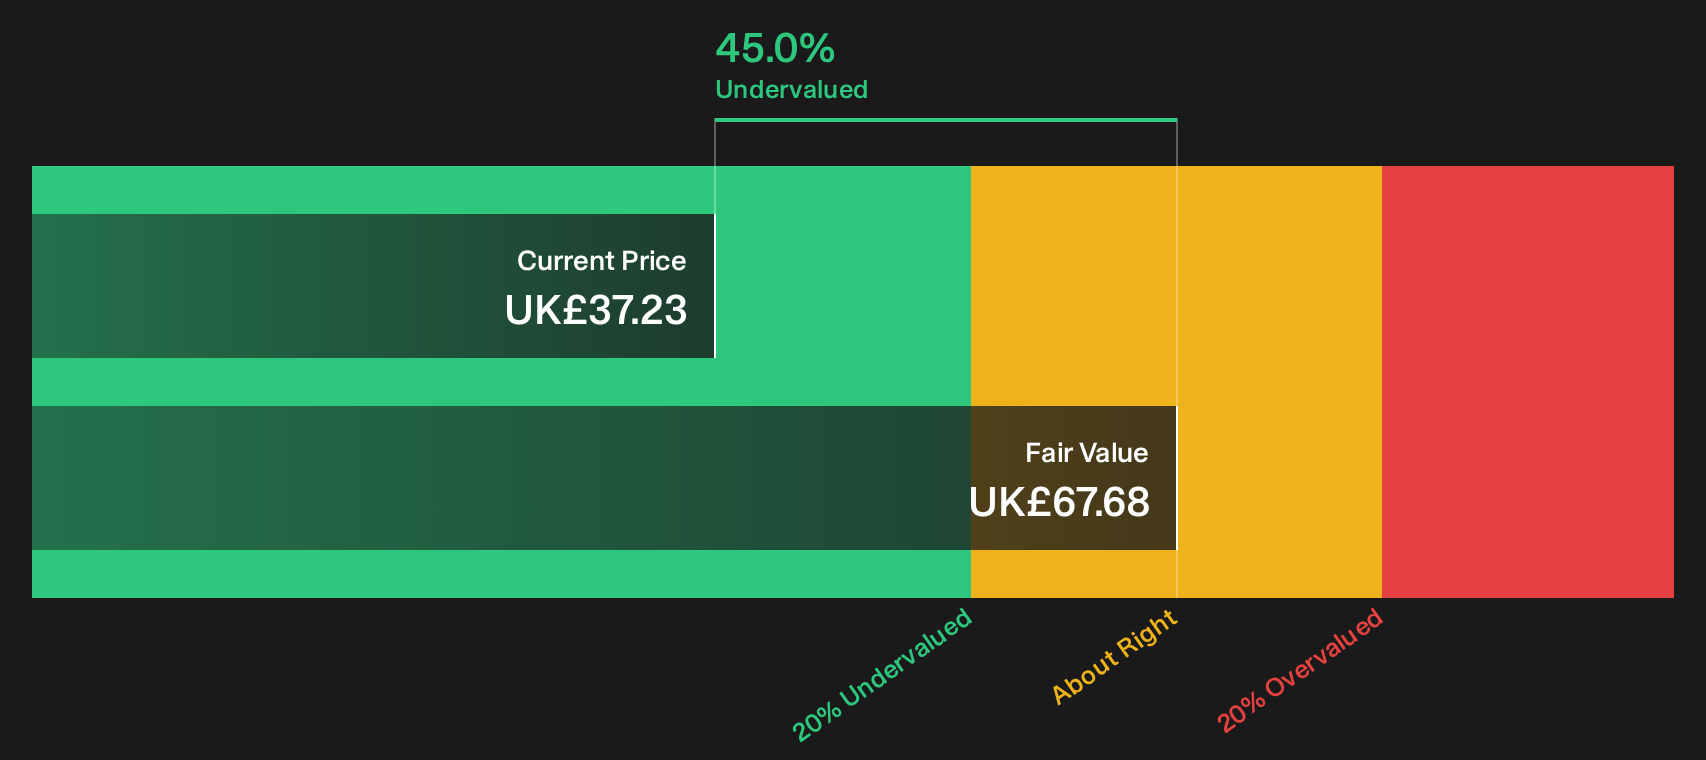
Shell (LSE:SHEL)
Overview: Shell is a global energy and petrochemical group whose refineries and marketing network convert oil and gas into cash-generative fuel and chemical products.
Operations: Shell’s largest revenue streams come from Marketing at about US$146b and Chemicals and Products at roughly US$143b, with Integrated Gas contributing around US$53b.
Market Cap: £212b
For a cash flow focused screen, Shell matters because its refinery, chemicals, and fuel marketing engine throws off sizeable free cash that feeds its discounted cash flow valuation, according to Composite_Research, an investor in the Simply Wall St Community.
"Global LNG trade volume reached a record high of 437 million tons in 2025, and Shell estimates it will increase by 65% to reach 700 million tons by 2050; the primary driving force behind this projection is the uninterrupted "baseload" electricity demanded by Hyperscalers for their artificial intelligence (AI) data centers."
What ultimately happens to Shell’s cash margins hinges on how one unresolved pressure shapes future pricing power in its most capital-efficient segments.
That pricing power question makes the full narrative for Shell especially useful for seeing how LNG demand, capex cycles and policy trends could be quietly reshaping Shell’s cash engine.
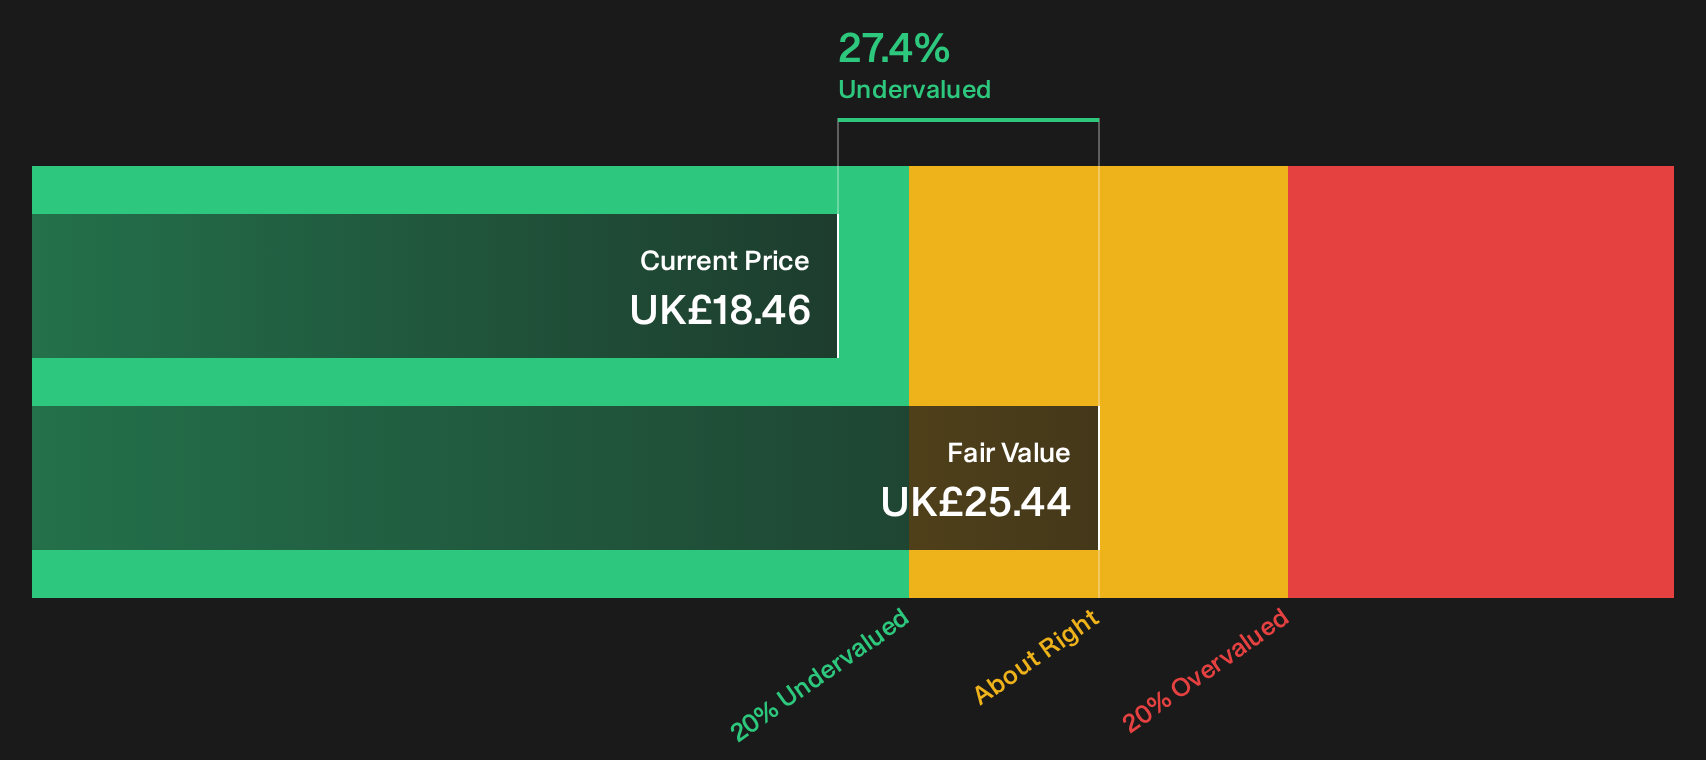
BAE Systems (LSE:BA.)
Overview: BAE Systems provides defense, aerospace, and security solutions, with Platforms & Services supplying long-term combat vehicles and support contracts that underpin recurring cash flows.
Operations: Revenue is broadly split across Electronic Systems at £7.8b, Air at £7.7b, Maritime at £6.7b, and Platforms & Services at £5.3b, with the United States contributing £13.5b and the United Kingdom £7.8b.
Market Cap: £52.2b
BAE Systems matters for a cash flow focused investor because its core work in combat vehicles, munitions, ship repair, and support services leans heavily on multi-year government contracts and after-market work. The analyst consensus Narrative on Simply Wall St highlights this as a foundation for years of revenue and earnings visibility.
"The company's order backlog reached £84b with total backlog plus incumbent program positions of around £260b, which equals about 8x annual sales and points to multi year support for revenue and earnings."
What happens to BAE Systems’ margins will turn on how one ambitious capacity and digitalisation push translates that backlog into actual cash generation.
Turning that backlog into accelerating cash is the heart of the full narrative for BAE Systems. This plan lays out how BAE Systems could convert orders into resilient earnings power.
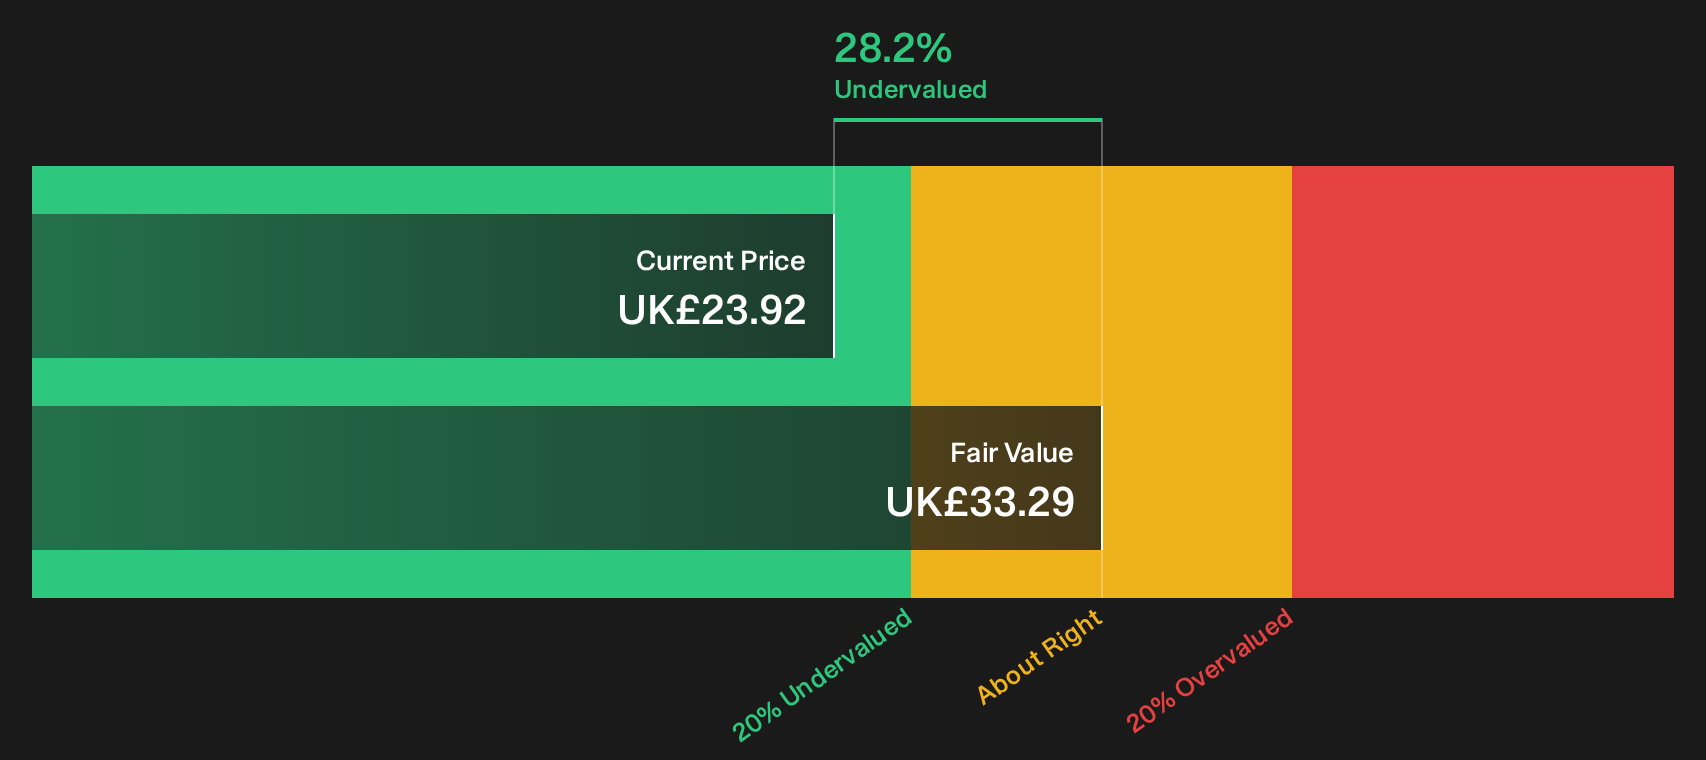
Genus (LSE:GNS)
Overview: Genus is an animal genetics group supplying breeding pigs, dairy and beef genetics, and herd-management services to commercial farmers worldwide.
Operations: Genus PIC generates £355.8 million and Genus ABS £299.8 million, supported by diversified customer demand across North America, Latin America, Europe, Asia and the UK.
Market Cap: £1.5b
Genus matters for a cash flow focused investor because its PIC and ABS genetics franchises earn repeat income from long-term breeding and royalty arrangements, and the analyst consensus Narrative on Simply Wall St now frames that recurring model as a key driver of valuation debate.
"The build out of Genus’ high margin, recurring PIC royalty model, including more than 50% royalty revenue growth in China on top of 6% group royalty growth in H1 FY26, reflects expansion of royalty driven revenue and operating profit as contracts mature and penetrate a larger share of global pig herds."
What happens to Genus’ valuation depends in part on how one evolving China focused royalty stream shapes the balance between cash strength and earnings pressure.
That China royalty equation is only part of the story, with the full narrative for Genus revealing how Genus could see cash flows decoupling from near term earnings noise.
Seeking Fresh Alternatives Beyond These Picks?
Fresh ideas move first. Once momentum builds, clean entry points can vanish as prices start flying and under the radar stories get caught by the crowd. Consider reviewing potential opportunities promptly.
- Target sturdier cash engines by scanning a curated list of solid balance sheet and fundamentals (9 results) while they are still under the radar for now.
- Explore early breakout potential by checking 5 high quality undiscovered gems that screens for strong fundamentals before momentum traders respond.
- Review dependable income streams by examining 5 dividend fortresses that focus on staying power while yields remain elevated.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com