


AI data center stocks are back in the spotlight after a sharp rebound in semiconductor heavyweights like TSMC, just as political shifts in the U.S. and fresh rate hike risks complicate the picture. That mix of renewed enthusiasm and policy risk is creating a window where prices and expectations may be out of sync. This article walks through 3 stocks exposed to these headlines and what that could mean for your portfolio.
The three AI data center infrastructure stocks covered below are just a sample, and the full screen surfaced 65 more Asian hardware and equipment companies with equally compelling narratives that do not fit into a single article. If you want to identify and analyze potential high conviction ideas tailored to your own risk limits, head straight into the Asian AI Data Center Infrastructure Suppliers screener.
Powertech Technology (TWSE:6239)
Overview: Powertech Technology provides outsourced IC packaging, testing, and assembly services for high performance chips used in AI data center hardware.
Operations: Powertech Technology generates NT$91,171 million of revenue from semiconductor related services, with semiconductors accounting for 100% of reported segment sales.
Market Cap: NT$150.3b
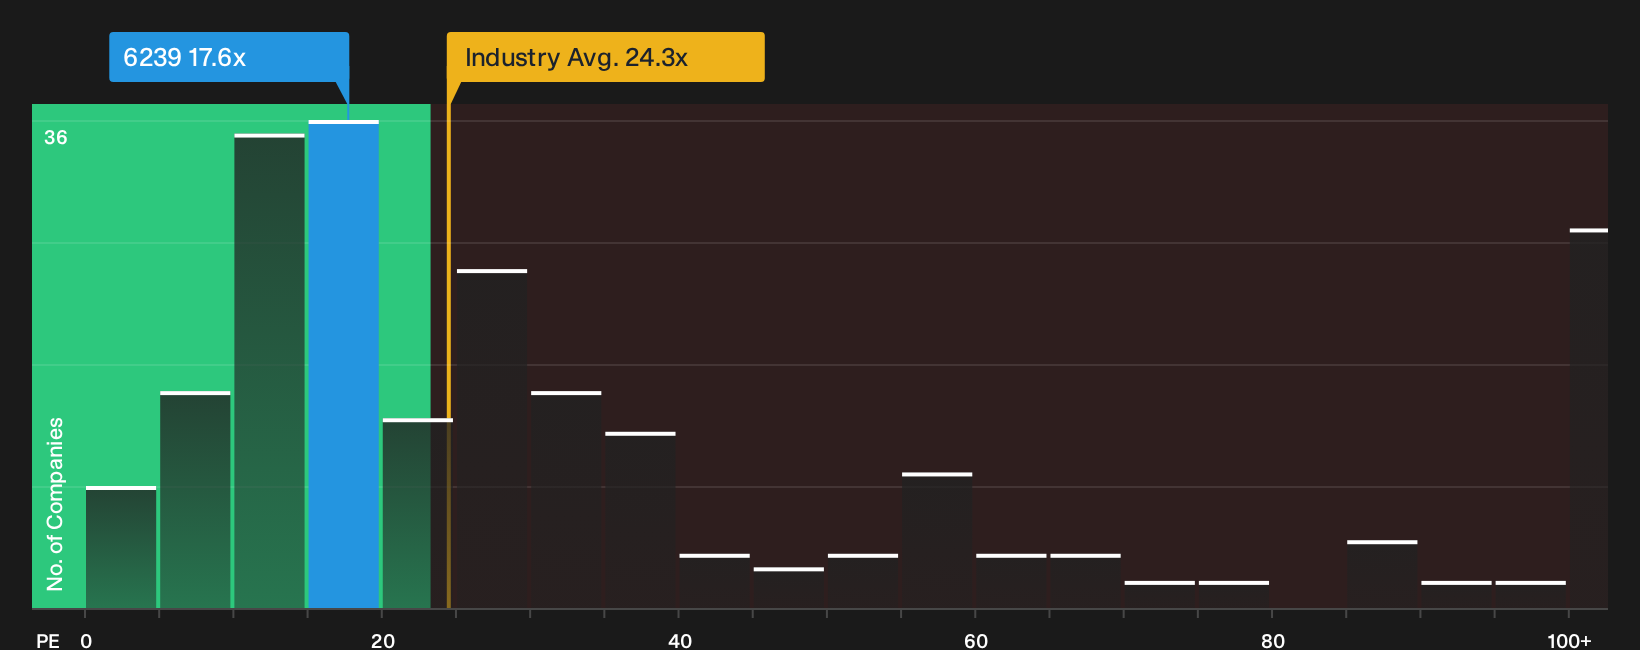
Powertech Technology participates in the AI data center build out by handling complex packaging and testing for logic and memory chips used in servers and accelerators. Earnings growth is projected through 2026, supported by higher volumes and improving margins, while the valuation currently sits below sector averages. This leaves investors exposed to the impact of potential changes in utilization and pricing.
That valuation gap and earnings path make it worth stress testing the 4 key rewards and 2 important warning signs so you see what the market might be mispricing.
Tokyo Electron (TSE:8035)
Overview: Tokyo Electron develops and sells semiconductor production tools that chipmakers rely on to build advanced logic and memory for AI data centers.
Operations: Tokyo Electron generates ¥2,931,320 million of revenue from semiconductor production equipment, with this segment accounting for 100% of reported sales.
Market Cap: ¥18,703.7 billion
Tokyo Electron is one of the clearest expressions of the screener theme. The bullish analyst Narrative on Simply Wall St focuses on its role supplying critical gear to the fabs racing to meet AI data center demand.
"The ramp of Tokyo Electron’s Miyagi Innovative Production Center, which management indicates could ultimately triple production capacity, creates room for equipment shipments to rise faster than many models assume, with potential upside to revenue scale and operating leverage if higher volumes spread fixed costs over a larger base."
What happens to that earnings power depends on how one less visible pressure on profitability and capital intensity actually plays out.
If that pressure on profitability is where your thesis lives, the full narrative for Tokyo Electron shows how Tokyo Electron’s capacity ramp, capital demands, and AI exposure could be decoupling expectations.

Sumco (TSE:3436)
Overview: Sumco manufactures high purity silicon wafers that global chipmakers use as base material for advanced AI and data center semiconductors.
Operations: Sumco generates ¥419,314 million from high purity silicon wafers, serving customers across Japan, Taiwan, China, South Korea, the U.S., Europe and other regions.
Market Cap: ¥624.1 billion
Sumco matters for this AI data center infrastructure screen because it sits at the raw material stage. The analyst consensus Narrative on Simply Wall St states that its wafer mix is shifting toward products that line up directly with data center logic and memory demand.
"Sumco's focus on ramping up production of leading-edge 300mm wafers for AI driven logic, HBM DRAM and NAND aligns with the reported recovery in global 300mm wafer shipments and growing AI related DRAM and NAND wafer needs."
What eventually happens to Sumco's future margins and cash generation hinges on how one quiet cost and capacity swing plays out.
That quiet swing is exactly where expectations can drift away from reality, and the full narrative for Sumco lays out how Sumco’s wafer mix could accelerate or cap that story.

Seeking Fresh Alternatives Before They Fly
Some of the sharpest breakout and momentum stories start quietly, then get caught once the crowd piles in. Scan curated ideas that are under the radar for now and consider them before they become widely followed.
- Spot early turnarounds that pair higher risk with tighter balance sheets by running through the 121 elite penny stocks with strong financials before the quickest movers are already flying.
- Track where real earnings momentum meets AI adoption by skimming the hand picked 42 profitable AI stocks that aren't just burning cash while the signals still matter.
- Stabilize the wilder parts of your portfolio by anchoring around the curated list of solid balance sheet and fundamentals (193 results) before volatility forces rushed decisions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com