


- Groupe Bruxelles Lambert reported nine month 2026 results showing sales of €5,117.6 million and net income of €28.6 million, compared with a net loss in the prior year period.
- The return to positive earnings per share from continuing operations, at €0.25 basic and diluted, reflects a shift in operating performance versus last year.
- Next, the focus moves to how this return to profitability influences Groupe Bruxelles Lambert's investment narrative and risk profile for investors.
What Is Groupe Bruxelles Lambert's Investment Narrative?
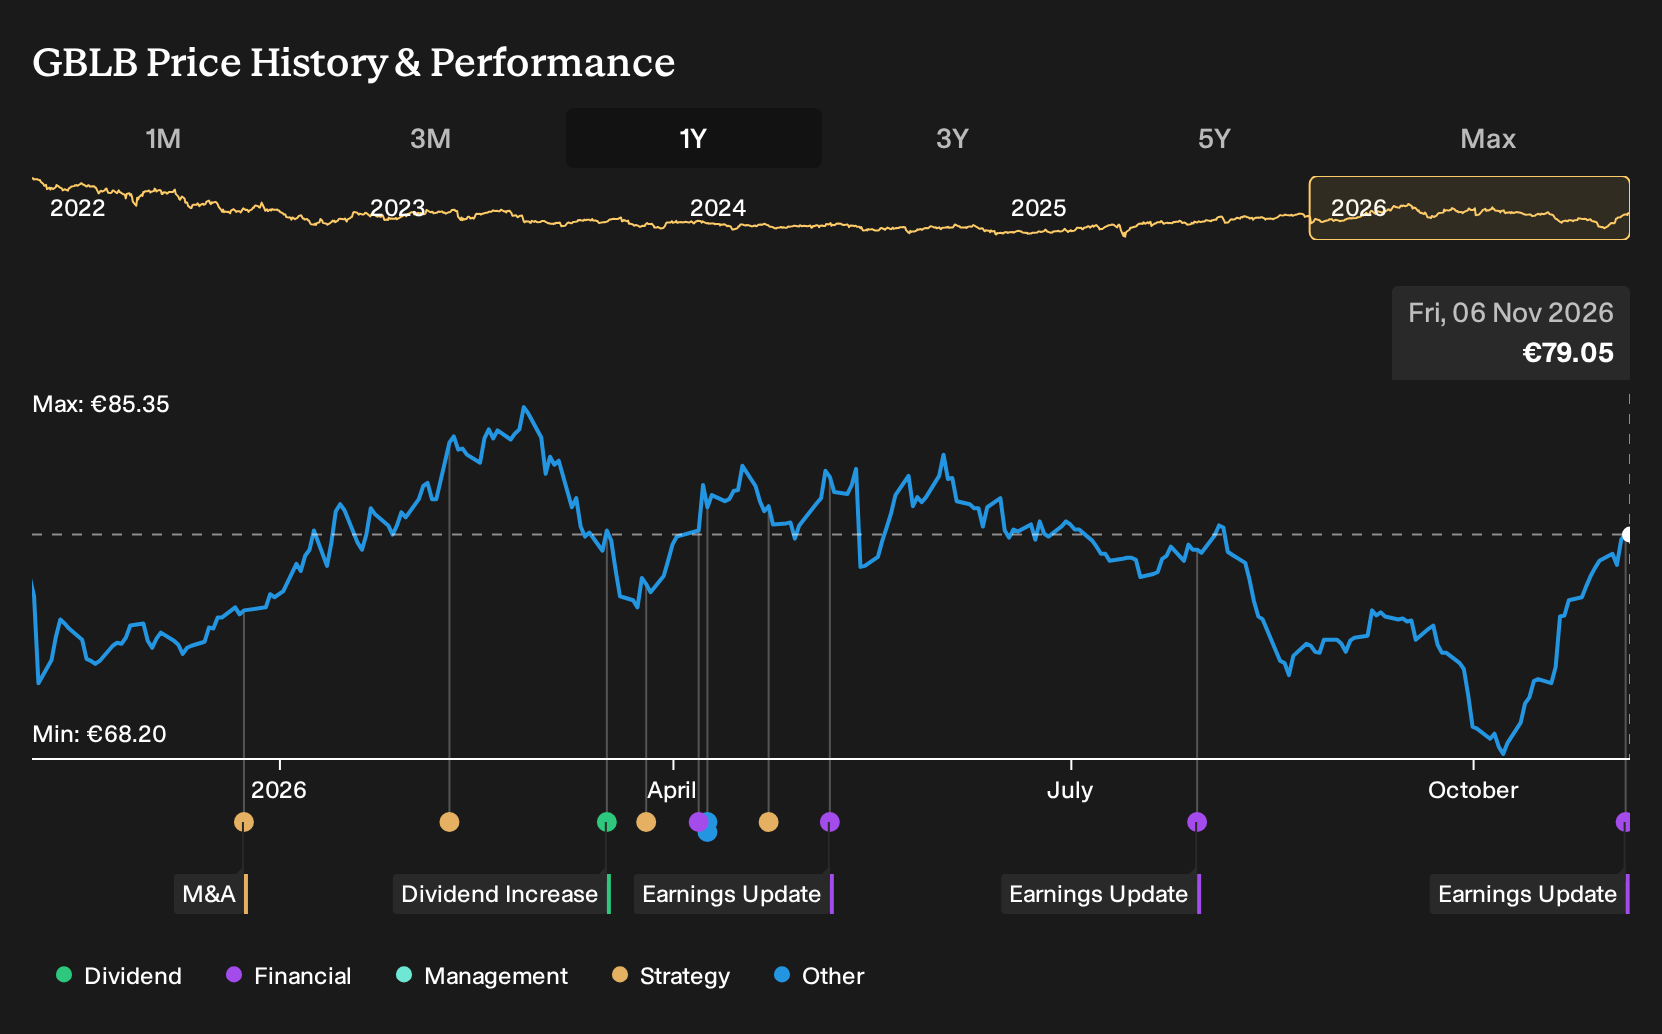
To own Groupe Bruxelles Lambert, you need to be comfortable owning a holding vehicle that lives and dies by the quality of its underlying assets and capital allocation. The recent nine month 2026 update, with €5,117.6 million in sales and a swing to net income of €28.6 million, feeds into that story by showing the portfolio can support positive earnings per share, even if the broader track record still includes periods of losses and a negative return on equity.
In the short term, the key levers are execution inside core holdings, cash generation to fund investments, and the balance between that and a dividend that was flagged as not well covered by earnings or free cash flows. Forecasts pointing to strong earnings growth and a path back to profitability over the next few years set expectations, yet the latest profit print raises the bar on consistency for Groupe Bruxelles Lambert’s managers from here.
That said, there is a less comfortable wrinkle once you line up that dividend, the funding mix, and the forecast profit path.
There's only one way to know the right time to buy, sell or hold Groupe Bruxelles Lambert. Head to Simply Wall St's company report for the latest analysis of Groupe Bruxelles Lambert's Fair Value.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd. Consider your own instincts and analysis.
- A great starting point for your Groupe Bruxelles Lambert research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Groupe Bruxelles Lambert. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Groupe Bruxelles Lambert's overall financial health at a glance.
Looking For More Investment Ideas Beyond Groupe Bruxelles Lambert?
Once you have formed a view on Groupe Bruxelles Lambert, it can help to compare it with other businesses that share similar financial traits or risk profiles. The Simply Wall St Screener lets you filter the market down to a focused shortlist that actually fits your style, whether you care more about balance sheet strength, income potential, or finding under-followed opportunities with improving fundamentals.
- If capital preservation and steadier profiles matter to you, start with a shortlist of companies screened as more resilient through the 207 resilient stocks with low risk scores.
- Income focused investors who care about getting paid while they wait can zero in on higher yielding opportunities by using the 225 dividend fortresses.
- For those hunting for under-the-radar opportunities with solid financial footing, filter the market down to a list of solid balance sheet and fundamentals (193 results) that still flies below most radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com