


Strong US jobs data has reinforced expectations of higher interest rates, which often puts pressure on richly priced growth stories and pulls attention back to hard cash generation. That shift matters if you care about paying less than something is worth. This article walks through three stocks that our cash flow based value screen flags as trading below a carefully estimated fair value and explains why they deserve a closer look now.
The three stocks covered next are just a small sample, and the full cash flow based screen surfaced 101 more companies with equally compelling stories that do not fit into this article. To size up that broader field and quickly identify which ideas best match your own criteria, head straight into the Undervalued Stocks Based On Cash Flows screener.
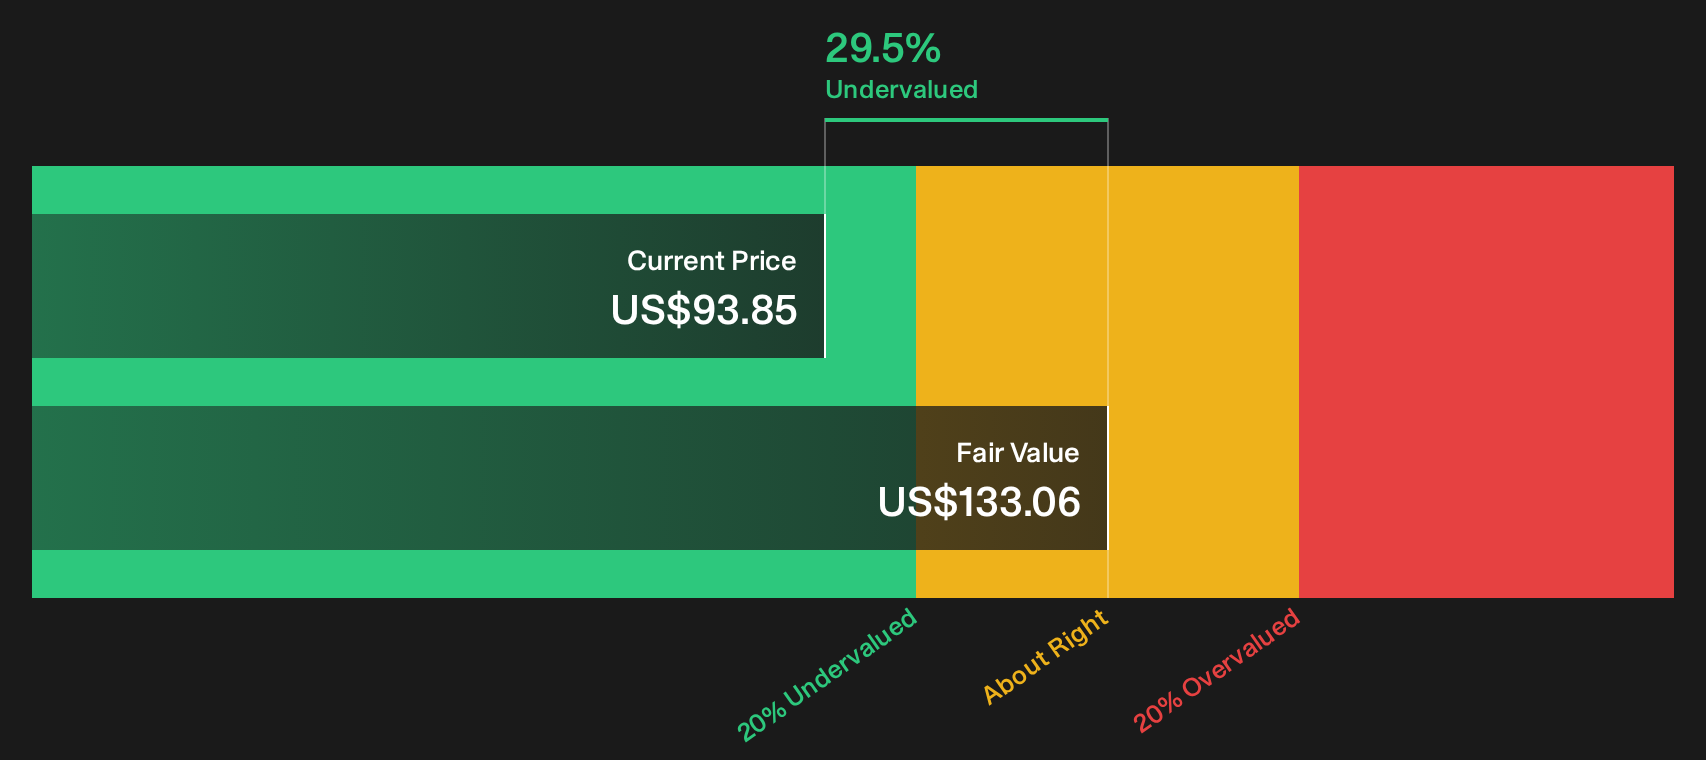
Cisco Systems (CSCO)
Overview: Cisco Systems provides networking hardware, software subscriptions, and security services that power and protect data centers, campuses, and cloud-connected businesses worldwide.
Operations: Cisco generates around US$63.3b from Computer Networks, with roughly US$34.4b from the United States and the rest split across APJC, EMEA, and other Americas.
Market Cap: US$369.5b
For the Undervalued Stocks Based On Cash Flows theme, Cisco Systems matters because its networking and security subscriptions convert AI and cloud demand into recurring cash streams that can be priced through discounted cash flow, according to CoksiBoy, an investor in the Simply Wall St Community who recently set out this thesis.
"The rollout transitions Cisco from experimental pilot programs to standardized, autonomous agentic workflows across sales, engineering, finance, legal, and customer support."
What ultimately happens to those cash flows may hinge on how one unseen pressure shapes the balance between AI demand and profitability.
That hidden pressure is exactly what could reshape Cisco Systems cash generation and the full narrative for Cisco Systems, including where recurring AI driven workflows might start to decouple from hardware cycles.
Crocs (CROX)
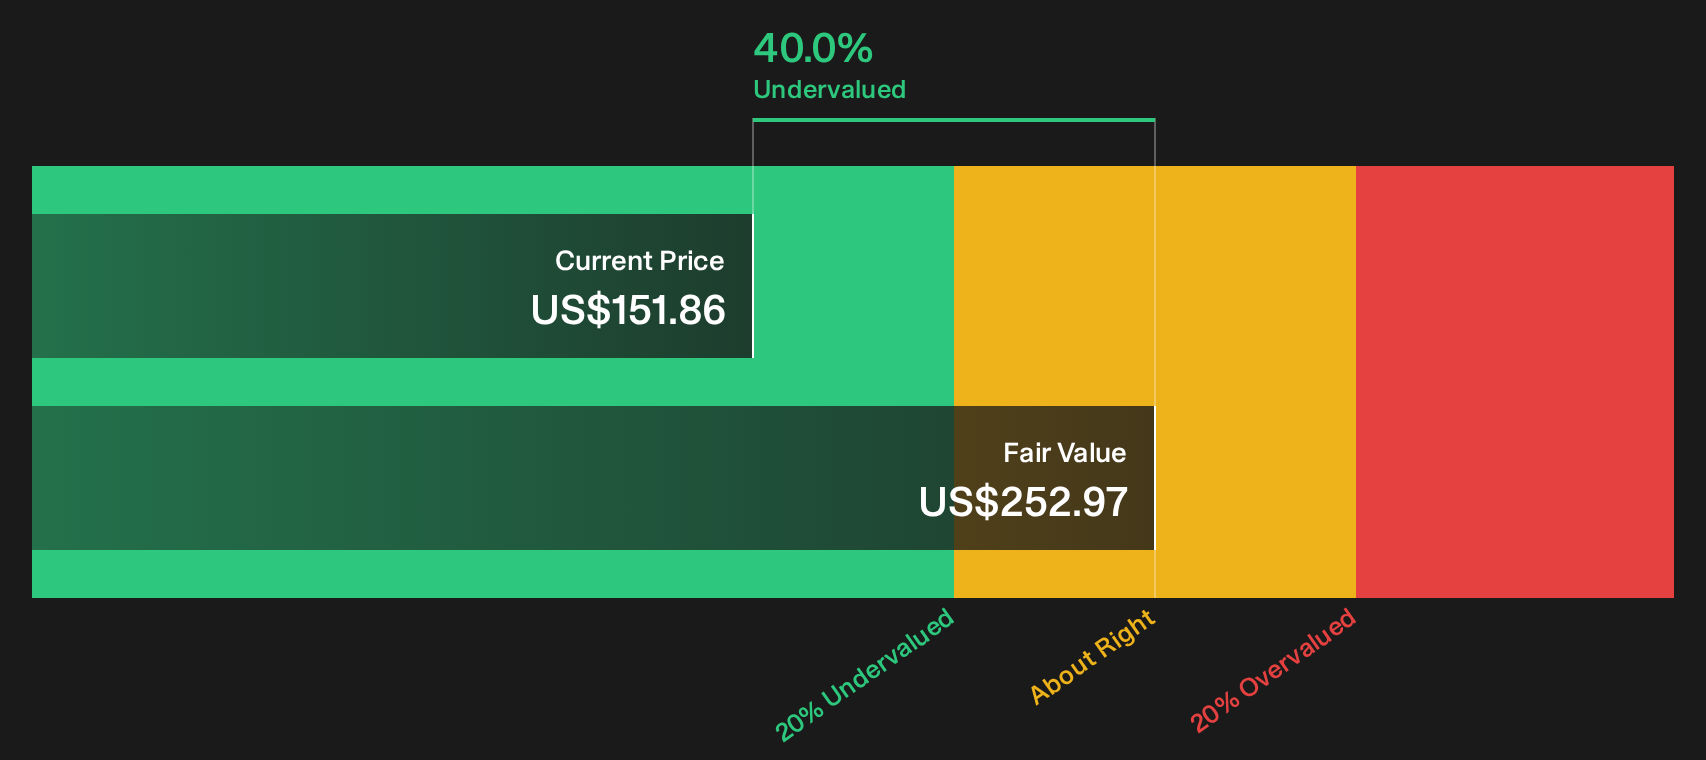
Overview: Crocs designs and sells casual footwear and accessories under the Crocs and HEYDUDE brands worldwide, generating cash from repeatable, high volume shoe franchises.
Operations: Crocs produces about US$3.4b from its Crocs brand and US$692 million from HEYDUDE, with US$1.9b earned internationally.
Market Cap: US$6.9b
Crocs fits the Undervalued Stocks Based On Cash Flows theme because its Crocs and HEYDUDE franchises turn simple, everyday footwear into sizeable, recurring cash that can be valued directly through discounted cash flow. The analyst consensus Narrative on Simply Wall St also notes that the range is widening beyond one hit product.
"Expansion of Crocs beyond the Classic Clog into sandals approaching $0.5b in expected 2026 revenue, new lifestyle franchises such as Ballet Flat and Mellow, and HEYDUDE extensions in sandals, work and boots points to a broader portfolio that can support a wider customer base and more stable revenue."
What happens to that cash flow story will depend on how one unresolved cost and tariff pressure interacts with the footwear demand curve.
That cost squeeze is exactly what the full narrative for Crocs unpacks in detail, revealing how Crocs could turn tariff pressure into accelerating brand reach and cash flow resilience.
Amazon.com (AMZN)
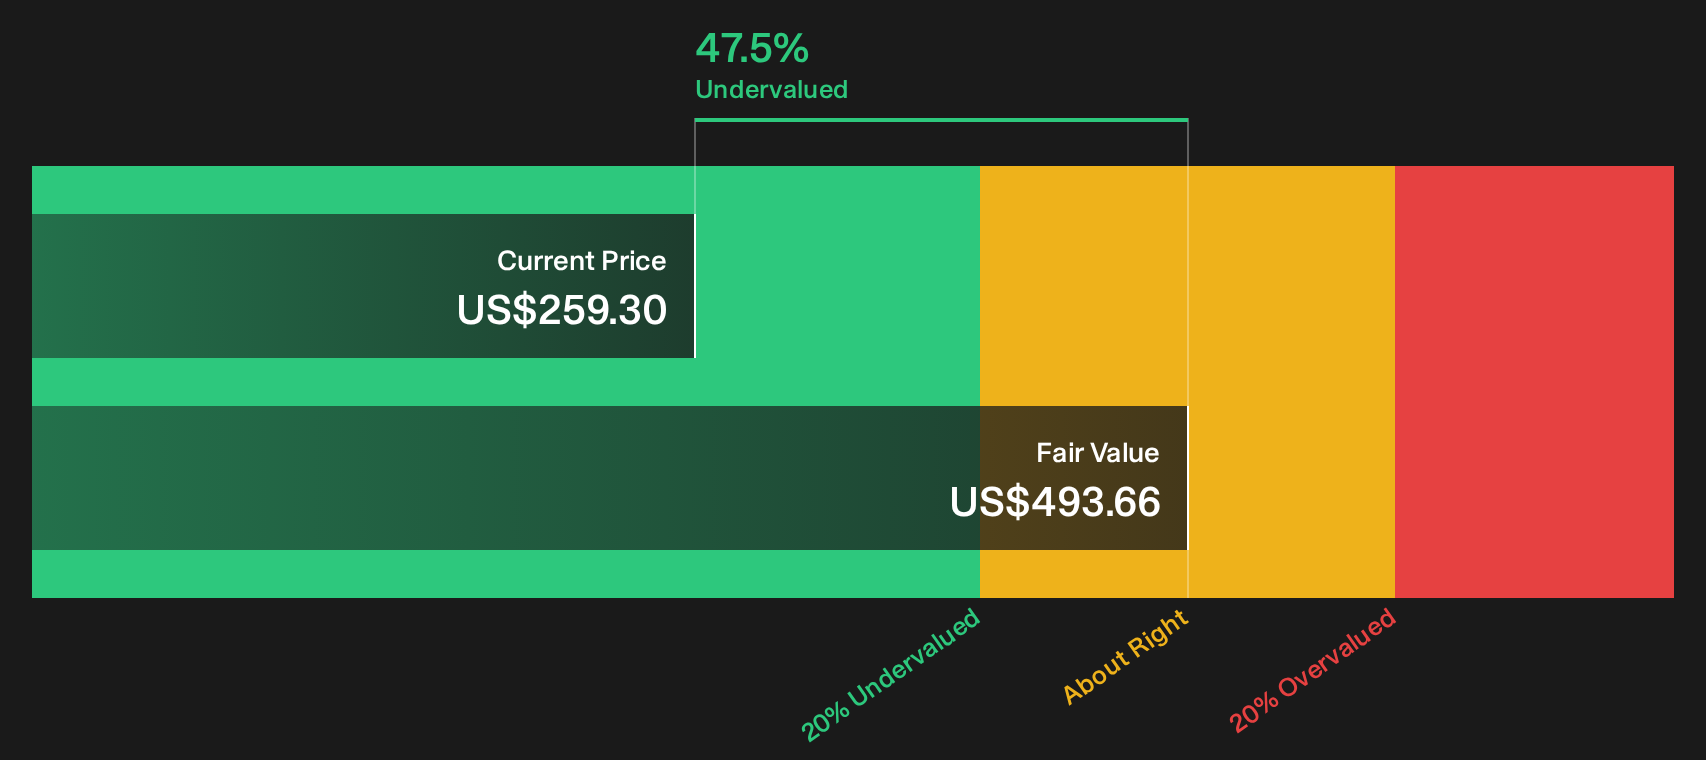
Overview: Amazon.com runs a global online and physical retail platform, cloud computing via AWS, digital content, devices, advertising, and subscription services.
Operations: Amazon.com generates about US$460.3b from North America, US$175.8b from International, and US$161.4b from AWS cloud services.
Market Cap: US$2,803.8b
Amazon.com matters for this cash flow focused screen because AWS turns long term cloud and AI infrastructure contracts into sizeable, model friendly free cash. MarketMuse, a Simply Wall St Community investor who wrote the Narrative, argues that the market still treats those reinvestment driven margins as a weakness rather than a source of future value.
"AWS continues to operate at high-20s to low-30s margins even while absorbing AI capex."
What those economics ultimately mean for Amazon.com comes down to how one sustained wave of AI data center spending interacts with future pricing power.
That tension is exactly what the full narrative for Amazon.com unpacks, distinguishing between temporary margin compression and accelerating cash generation as AI workloads scale through Amazon.com.
Seeking Fresh Alternatives Before They Fly
Fresh ideas move first, and the best breakout stories often gain momentum before the crowd even notices. Scan what others have not caught yet while it still matters, and consider acting early if it aligns with your strategy.
- Spot income workhorses that aim to keep paying investors while prices swing by scanning a curated set of 7 dividend fortresses before yields get crowded.
- Track early movers in automation as factories, warehouses, and supply chains upgrade, and sift through a focused pool of 91 robotics and automation stocks while they are still under the radar for now.
- Zero in on financially disciplined AI players instead of hype driven stories by filtering a refined list of 42 profitable AI stocks that aren't just burning cash before momentum traders pile in.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com