


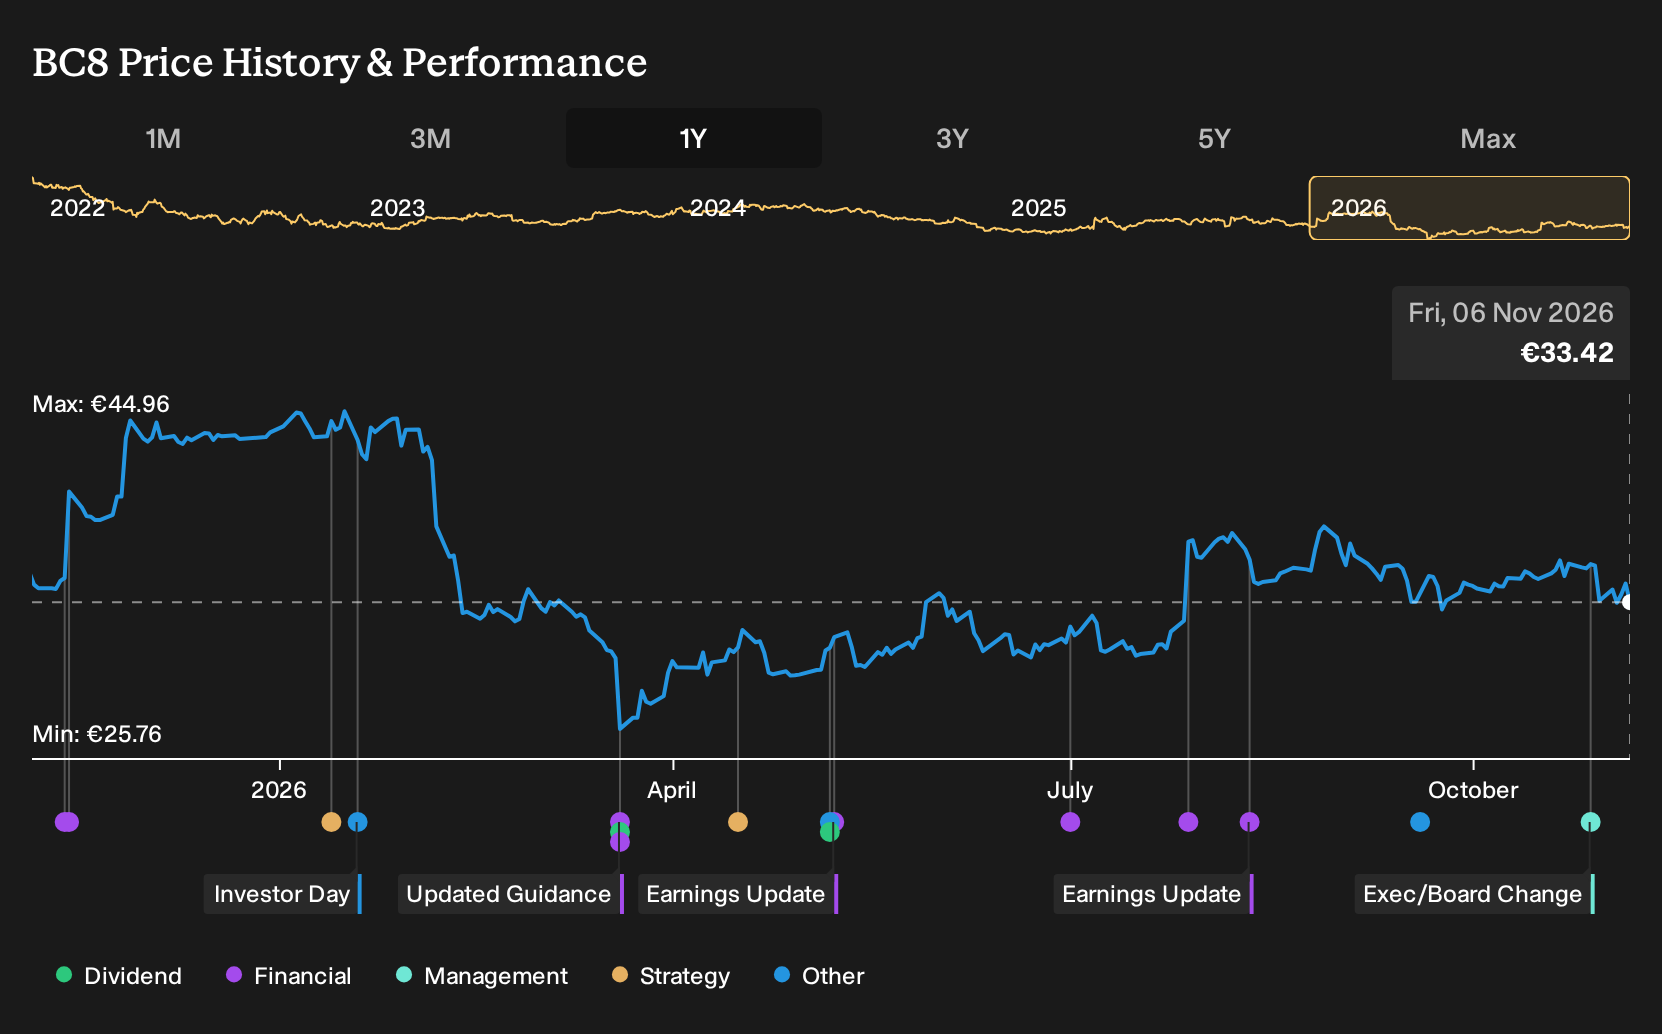
- Bechtle has overhauled its leadership structure, appointing Dr. Martin Kaloudis as Senior Executive Vice President International and reshaping regional responsibilities across Germany and Europe from January 1, 2027.
- The creation of a dedicated international leadership role and an Operational Excellence function points to a sharper execution focus on cross border integration and efficiency.
- We will now look at how Bechtle's refreshed international management set up could reshape the existing investment narrative for the business.
Scan how Bechtle's leadership revamp compares with other IT service providers repositioning for international growth by reviewing the hand picked list of solid balance sheet and fundamentals (193 results).
Bechtle Investment Narrative Recap
To own Bechtle, you need to believe in a gradual shift toward higher margin services, recurring contracts and AI driven tools, supported by solid execution on its S/4HANA and cloud projects. The analyst consensus Narrative on Simply Wall St sees these programs as key levers for earnings quality, even as German and French mid market IT demand remains a swing factor.
The management reshuffle looks incremental for the near term thesis. The biggest short term catalyst still sits in whether IT spending from small and mid sized customers normalizes. The main operational risk remains cost or timing overruns on Bechtle's internal transformation, which already weighs on EBT by a low single digit million euro amount each year.
The most relevant element of the recent announcement is the creation of a Director Operational Excellence role, now held by Jürgen Schäfer. That function lines up directly with the margin and productivity story investors are tracking, from process harmonization through to lifting EBIT as a share of gross profit over time.
For anyone watching catalysts, this adds an identifiable leader to the S/4HANA, cloud and integration agenda rather than changing the thesis itself. Execution discipline on these programs remains central to the 2030 volume and 5% EBT margin ambitions, while missteps could keep profitability uneven across regions and slow any improvement in earnings quality.
Bechtle's narrative projects €8.0b revenue and €306.0 million earnings by 2029. This aligns with analysts assuming 5.9% yearly revenue growth and implies an earnings increase of about €60 million from €245.5 million today.
Uncover why Bechtle's fair value indicates a 29% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
One alternate view you might explore is the risk that Bechtle’s bigger international footprint simply locks in weaker profitability abroad. The most cautious analysts were already pencilling in about €7.8b revenue and €300.7 million earnings by 2029. This reflects a more muted story that this new management line up could still challenge.
Explore 2 other Bechtle fair value estimates, including one that suggests it could be worth just €43.25!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Bechtle research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bechtle. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bechtle's overall financial health at a glance.
Looking For More Ideas Beyond Bechtle?
If you want to stress test your view on Bechtle against other opportunities, it can help to scan a broader set of companies that share traits you care about, whether that is balance sheet strength, income potential or under followed growth stories.
- For investors who care most about financial resilience and clean accounts, start with a list of solid balance sheet and fundamentals (193 results) that pass strict balance sheet and fundamentals filters.
- If steady income is your focus, compare Bechtle with cash generators in a 225 dividend fortresses that aim to combine higher yields with resilient business models.
- To widen the opportunity set beyond well covered stocks, scan a 572 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com