


Higher expectations for another US Federal Reserve rate hike have pushed the US dollar stronger, which can pressure bond prices and make steady income harder to find. For Canadian dividend investors, that shifts attention to homegrown businesses that steadily raise their payouts instead of chasing headline yields. This article highlights three Canadian stocks with dividend yields between 2% and 5% and a track record of growing those payouts over time.
The three stocks below are only a sample of this theme, and the full Type 2 Dividend screen surfaced 7 more Canadian companies with similar payout and earnings profiles that are not covered here.
If you want to identify and analyze those additional candidates in one place, head straight into the Growing Dividend Payers with 2-5% yield screener
Royal Bank of Canada (TSX:RY)
Royal Bank of Canada is one of the core picks in this Growing Dividend Payers theme, with its everyday banking and wealth arms throwing off recurring cash flows that can support steady payout increases over time, according to the analyst consensus Narrative on Simply Wall St.
"Expanded use of AI and advanced analytics at Royal Bank of Canada, including over 200 production models and a stated target of $700 million to $1 billion in net AI driven enterprise value by fiscal 2027, is expected to support lower operating costs, higher staff productivity and more targeted product penetration, which would feed through to net margins and earnings."
The real swing factor is how one quiet pressure point shapes the balance between those efficiency gains and the cost of keeping credit risk contained.
That quiet pressure point is unpacked in the full narrative for Royal Bank of Canada, where you see how credit risk, capital demands and payout ambitions are interacting in practice.

Canadian Imperial Bank of Commerce (TSX:CM)
Canadian Imperial Bank of Commerce anchors this Growing Dividend Payers idea through its everyday Canadian banking and lending engine. The analyst consensus Narrative on Simply Wall St focuses on how those recurring earnings increasingly pair with higher fee income from wealth and capital markets.
"Continued growth in Canadian Imperial Bank of Commerce mass affluent and wealth franchises, supported by 20% to 24% AUA and AUM growth and strong mutual fund net sales, can keep lifting fee based revenue and smooth earnings compared with more rate sensitive lines."
The real test for Canadian Imperial Bank of Commerce is how one subtle shift in client behavior ultimately filters through to margins and dividend headroom.
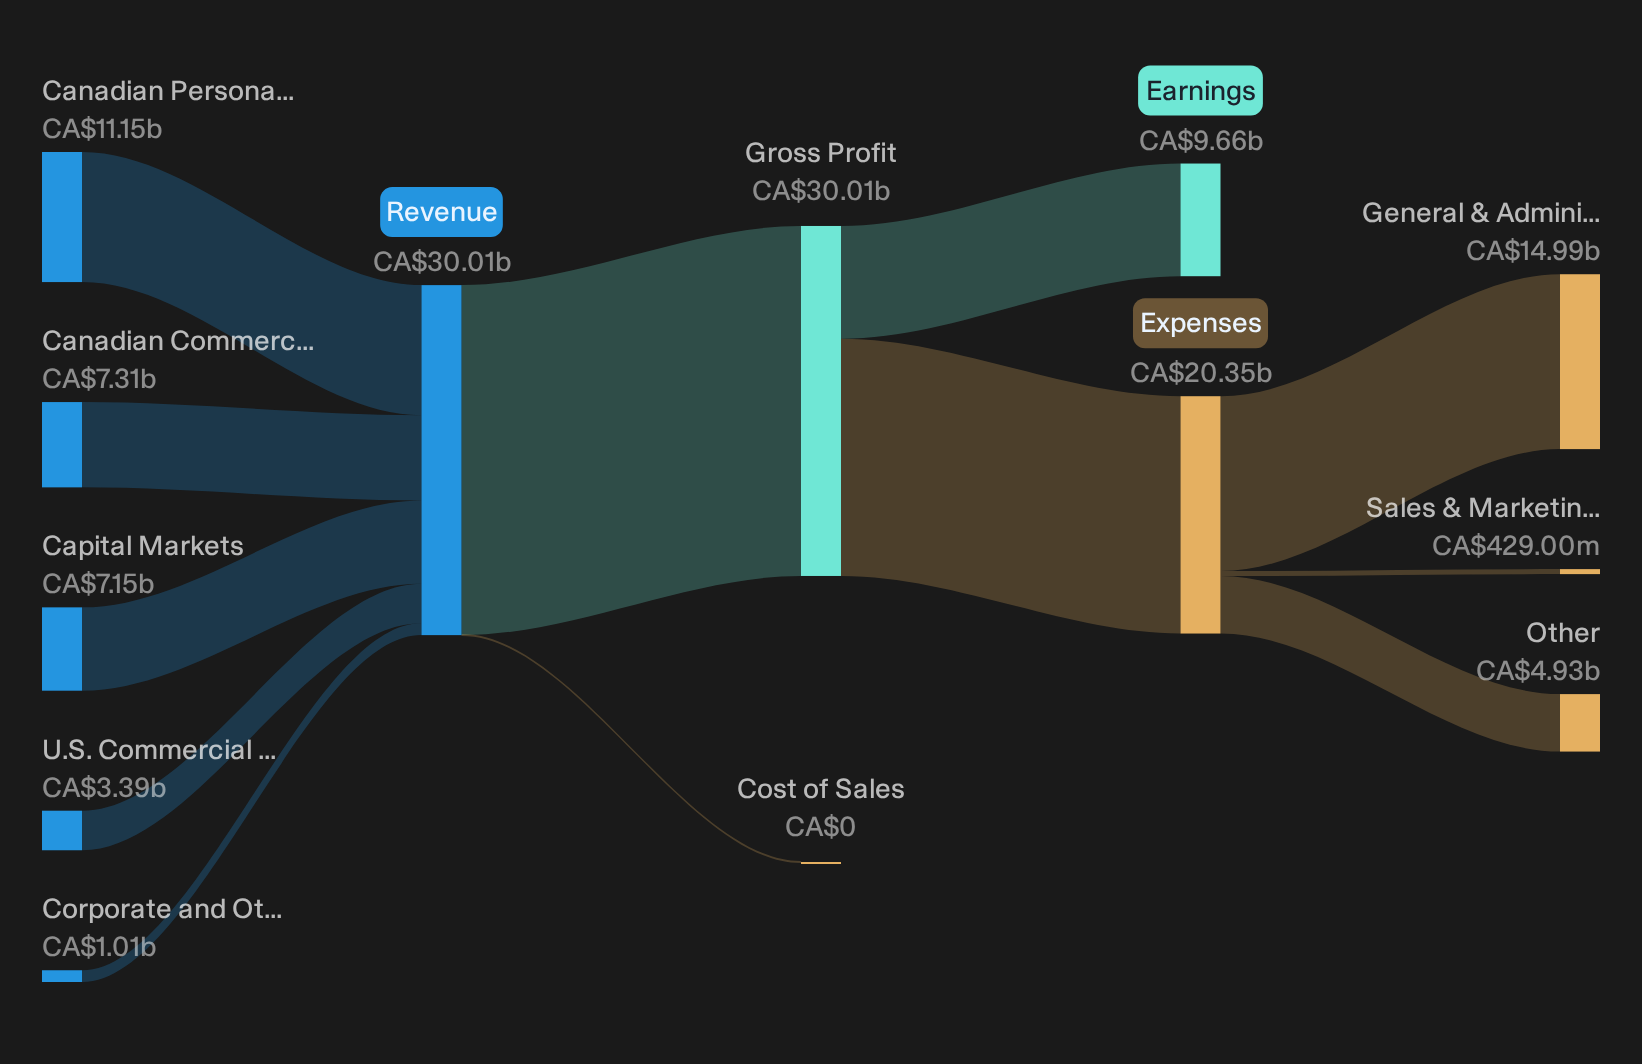
Canadian Imperial Bank of Commerce runs a broad mix of consumer, commercial and wealth services, with Canadian Personal and Business Banking generating about CA$11.2b of revenue and Canadian Commercial Banking and Wealth Management contributing roughly CA$7.3b. This sits inside a group that reports CA$7.1b from Capital Markets and a market cap near CA$148.0b.
That shift starts in day to day client choices, and the full picture sits inside the full narrative for Canadian Imperial Bank of Commerce, where margin pressure and dividend capacity are analyzed in detail.
Cascades (TSX:CAS)
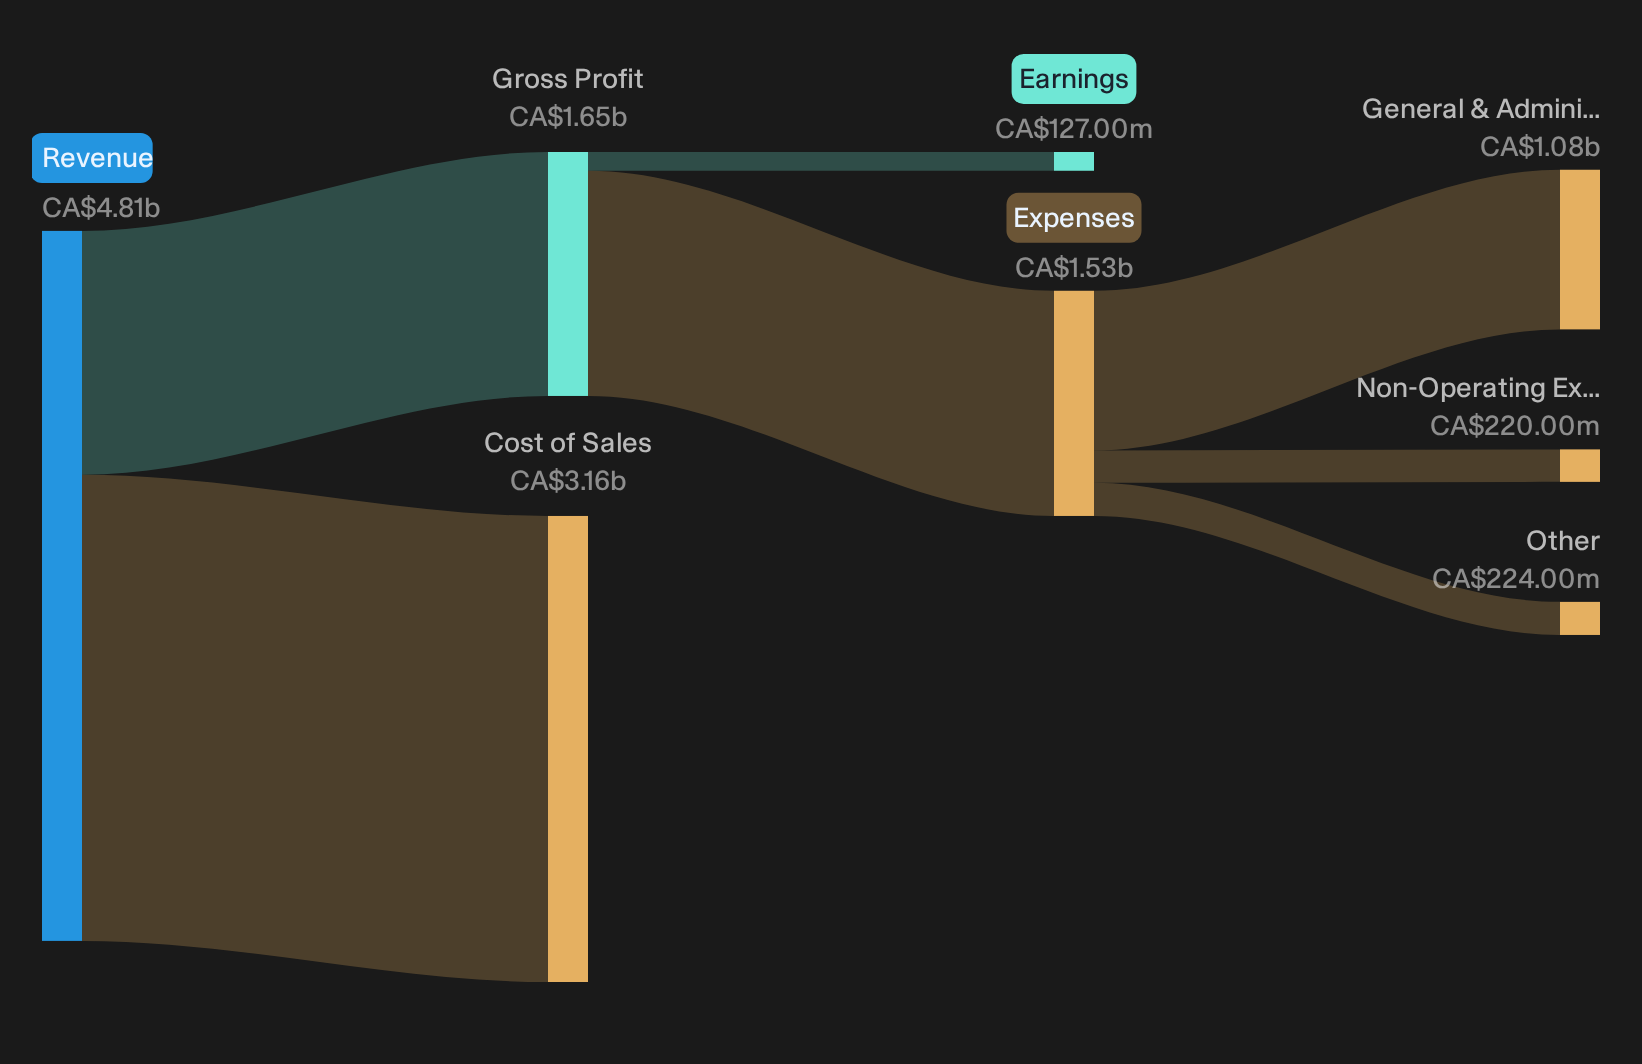
Cascades blends packaging, recycling and tissue products, and it is that Tissue Papers arm, with its recurring hygiene and tissue sales, that links neatly to the growing dividend payers theme flagged in the bearish analyst Narrative on Simply Wall St.
"Although Cascades is lifting production at key sites like Bear Island and Greenpac, continued cost pressure from logistics, fuel and chemicals could limit how much of that improved throughput converts into higher EBITDA margins and earnings."
What happens if one stubborn cost line refuses to ease just as Cascades leans harder on tissue driven cash flow for dividend support?
If that cost squeeze keeps grinding, the full narrative for Cascades shows how Cascades could still lean on tissue cash flow, shifting the balance between pressure and renewed momentum.
Seeking Fresh Alternatives Beyond Dividends?
Fresh opportunities rarely stay quiet for long. Breakout stories build momentum, laggards keep dropping, and the best ideas get caught quickly. Scan new ideas before the crowd and act now.
- Spot cash generative businesses with cleaner balance sheets by running the list of solid balance sheet and fundamentals (5 results) while that group remains under the radar for now.
- Target income ideas with staying power by using the 3 dividend fortresses before yields and prices reset and the easy window for entry closes.
- Hunt for future leaders by filtering through the 7 high quality undiscovered gems while these underfollowed companies are still quietly building momentum.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com