


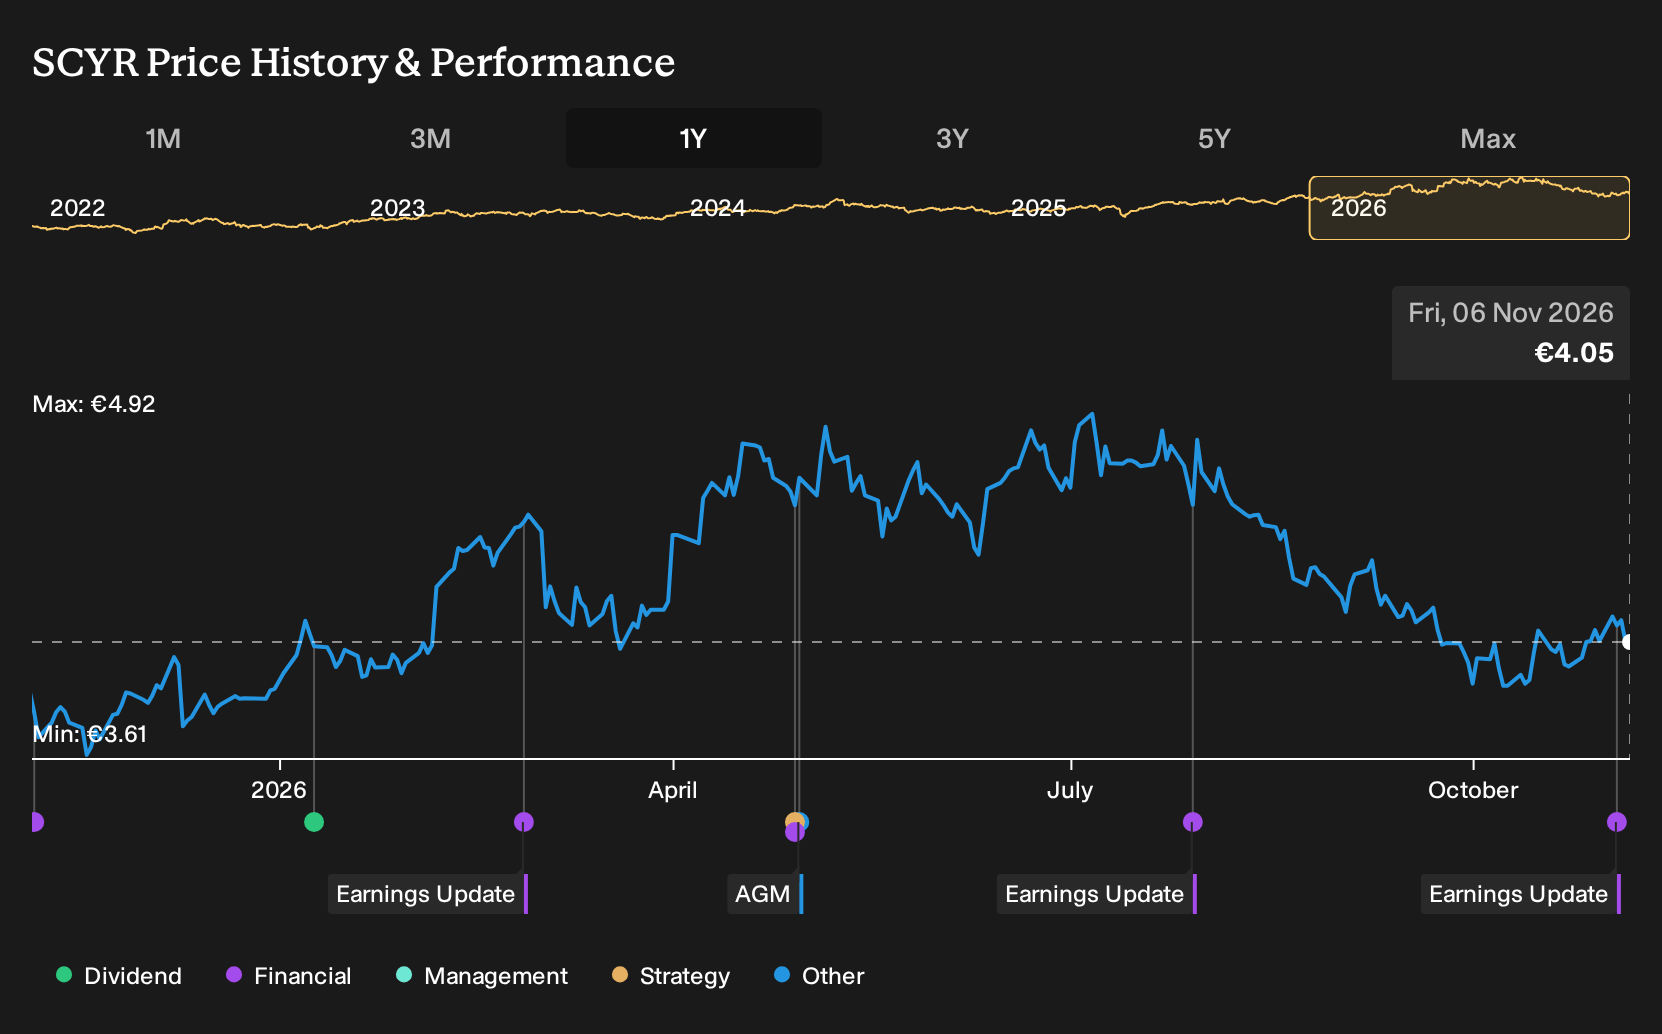
- Sacyr reported nine month 2026 sales of €3,776.92 million, revenue of €4,092.87 million and net income of €116.34 million, all higher than a year earlier.
- The sharp step up in net income, from €62.25 million to €116.34 million, highlights how the current project mix is feeding through to profitability.
- We will now look at how Sacyr's investment narrative is affected by this stronger nine month earnings performance and rising profitability.
Compare Sacyr's improving earnings profile with other infrastructure focused stocks that are moving on profitability shifts using our hand picked list of solid balance sheet and fundamentals (193 results).
Sacyr Investment Narrative Recap
To own Sacyr, you need to be comfortable with a concessions heavy model in which long contracts, a growing backlog and disciplined cash conversion carry more weight than headline construction cycles. The latest nine month figures, with higher sales, revenue and net income than a year earlier, point to projects that are currently landing on more profitable terms.
The near term swing factor is whether this stronger profitability can coexist with a still heavy project finance load and interest costs that are not yet well covered by earnings. The biggest risk remains leverage and exposure to currency and regulatory shifts in core Latin American and European markets.
The analyst consensus narrative on Simply Wall St anchors much of the current debate in earnings quality and concession growth. That view focuses on Sacyr’s cash conversion, emphasis on recurring concession income and past asset rotation out of Colombia into higher margin regions, all of which frame the recent earnings beat as part of a broader, concession led evolution.
There have been no fresh corporate announcements disclosed alongside these nine month figures, so the earnings release itself becomes the reference point for catalysts. For you, that means the operational story is doing the heavy lifting, while key open questions around debt reduction, interest coverage and geographic concentration remain unresolved and are likely to influence how sustainably Sacyr can build on this profit step up.
Sacyr's narrative projects €5.0b revenue and €175.8 million earnings by 2029. That path assumes 1.8% yearly revenue growth and requires earnings to rise by about €79 million from €96.5 million today.
Uncover how Sacyr's fair value indicates a 23% potential upside to its current price before the market closes that valuation gap.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly €4.98 to €28.31 per share, which shows how far apart private investors can be on Sacyr. Before these latest earnings, some focused on the concession backlog and cash conversion, while others highlighted currency and debt risks that could cap how efficiently profits are translated into equity value.
Explore another Sacyr fair value estimate, including one that suggests up to 600% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Sacyr research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sacyr. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sacyr's overall financial health at a glance.
Looking for more investment ideas beyond Sacyr?
Once you have formed a view on Sacyr, it can help to widen the net and compare it with other businesses that fit your risk, income or quality preferences using the Simply Wall St Screener.
- For investors chasing potential multi baggers at the smaller end of the market, scan through 120 elite penny stocks with strong financials that already show stronger financial underpinnings than the typical speculative micro cap.
- If value and quality matter most to you, filter for companies with healthier cash generation and pricing that suggests room for a re rating using the 223 high quality undervalued stocks.
- Those who care most about resilience can zero in on businesses with sturdier finances and lower risk profiles by running the 207 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com