


Becton Dickinson (BDX) just packed several investor focused announcements into one day, led by fourth quarter earnings showing higher sales and net income than a year earlier, alongside fresh guidance and capital return moves.
Recent trading suggests investors are leaning into that story. The share price has climbed 16.8% over the past 90 days and delivered a 52.2% total shareholder return over the past year, which indicates that momentum has been building ahead of these Becton Dickinson updates.
Scan how Becton Dickinson’s latest earnings, dividend increase and buyback compare with other health care names that are primed for quality and value in the 40 high quality undervalued stocks.
After a 52.2% total return in a year and fresh support from earnings, dividends and buybacks, is Becton Dickinson’s current valuation still skewed toward upside for new buyers, or is it now pricing in most of that progress?
Preferred P/E of 40.8x: Is it justified?
The current set up is clear. Becton Dickinson trades on a P/E of 40.8x, which prices the stock above several reference points even after the recent rally.
P/E compares what investors pay for each dollar of earnings, so a higher ratio often reflects strong confidence in future profit growth. For a large medical equipment business like Becton Dickinson, this measure highlights how much of that optimism is already embedded in the share price.
On this yardstick, the market is paying a higher earnings multiple than several benchmarks. The 40.8x P/E is described as expensive versus the estimated fair P/E of 37.4x, which is a level the valuation work suggests the multiple could move toward. It is also characterized as expensive against the US Medical Equipment industry average of 25.7x and above a 34.8x peer average, which means investors are assigning a premium well beyond sector and peer norms.
Explore the SWS fair ratio for Becton Dickinson.
Result: Price-to-earnings of 40.8x (OVERVALUED)
Still, any slip in earnings delivery or a reset in sector valuation appetite could challenge the current Becton Dickinson premium and cool recent momentum.
Find out about the key risks to this Becton Dickinson narrative.
Another view on Becton Dickinson’s value
The P/E story paints Becton Dickinson as expensive, yet the SWS DCF model points the other way. On that cash flow view, BDX at $211.88 is trading below an estimated future value of $239.38. This frames the recent rally as potentially still short of that reference point.
This kind of gap between earnings based pricing and a cash flow model can signal either a cushion for long term investors or a sign that assumptions in the DCF are too optimistic. The key question is which lens you trust more when profits, cash generation and sentiment do not all tell the same story.
Look into how the SWS DCF model arrives at its fair value.
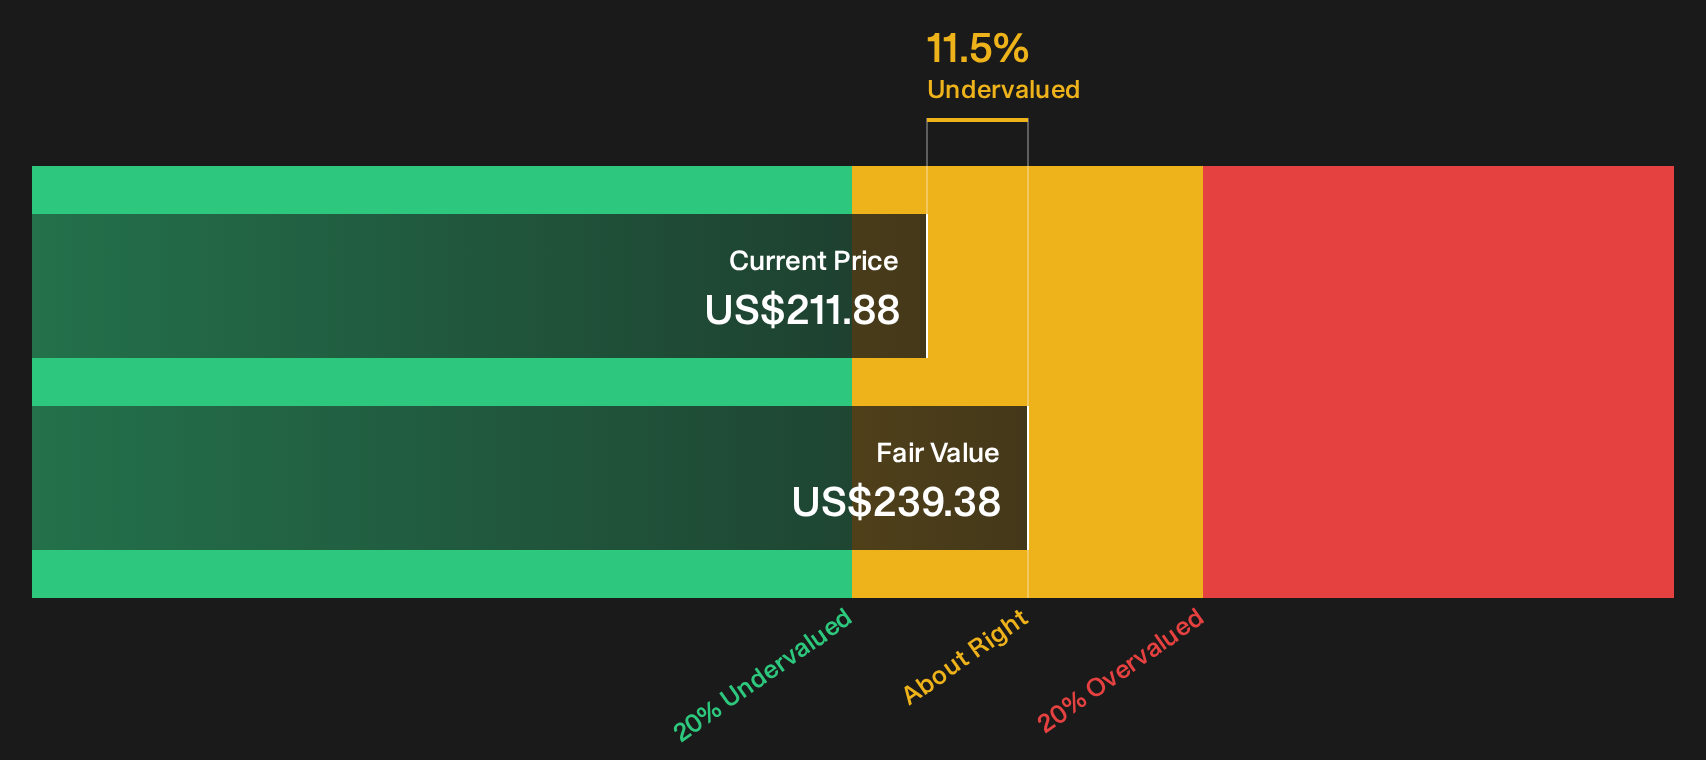
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Becton Dickinson for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 40 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If you are seeing mixed signals on Becton Dickinson and feel uncertain, consider acting while the details are fresh and weighing the trade off yourself using the 3 key rewards and 2 important warning signs
Looking for more Becton Dickinson sized ideas?
If Becton Dickinson has your attention, do not stop here. Broaden your watchlist now so you are not chasing the next move after it happens.
- Target resilient compounding potential by using the 31 resilient stocks with low risk scores to focus on businesses with lower risk scores that can help anchor your portfolio.
- Hunt for strong balance sheets by scanning the list of solid balance sheet and fundamentals (25 results) and concentrate on companies with fundamentals that may better withstand shocks.
- Spot tomorrow's potential leaders early with the 19 high quality undiscovered gems and give yourself a head start before the crowd pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com