


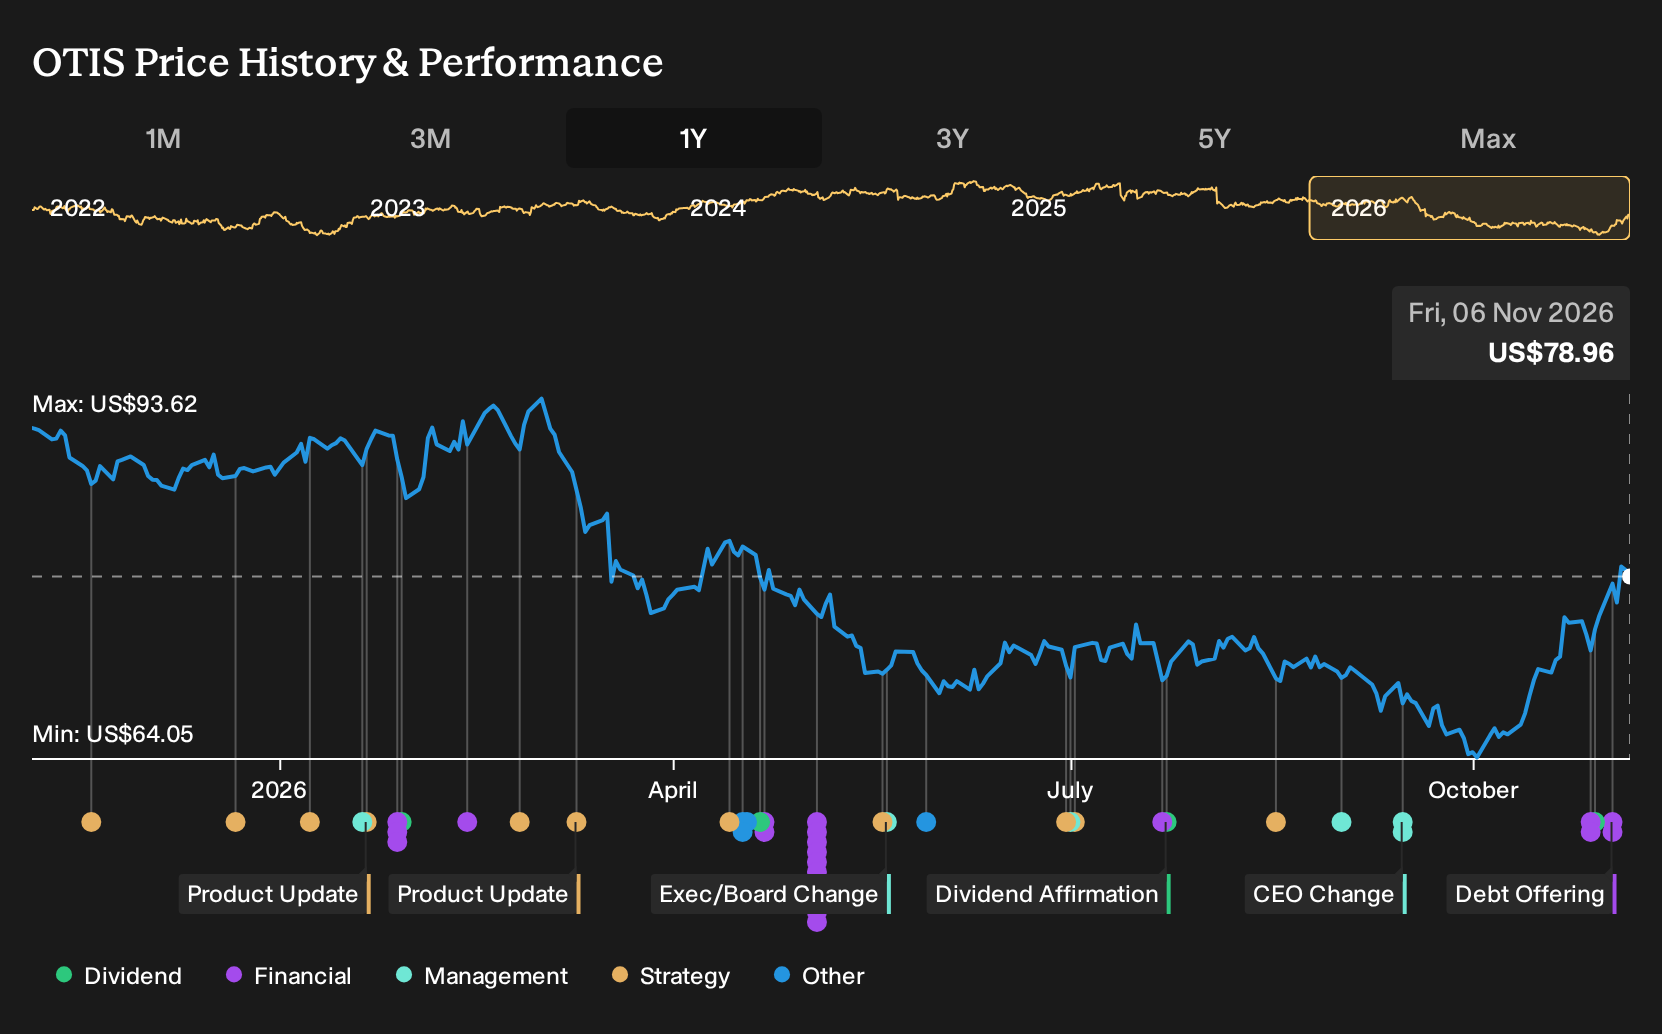
- Otis Worldwide reported third quarter 2026 results with sales of US$3,914 million and net income of US$414 million, alongside maintained full year 2026 net sales guidance of US$15.1 billion to US$15.3 billion and a US$500 million fixed rate bond issuance.
- The combination of higher earnings, reaffirmed outlook, a declared US$0.44 quarterly dividend and fresh unsecured senior funding indicates management confidence in Otis Worldwide's service heavy elevator and escalator model.
- This update reviews how Otis Worldwide's service driven investment narrative aligns with stronger earnings and reaffirmed guidance in the latest results.
Scan how Otis Worldwide's mix of service cash flows, dividends, and fresh bond funding compares with other resilient balance sheet plays inside the list of solid balance sheet and fundamentals (25 results) in today's market.
Otis Worldwide Investment Narrative Recap
To own Otis Worldwide, you need to believe in the long service runway on its installed elevator and escalator base, rather than in bursts of new construction. OLetourneau, a Simply Wall St Community investor who wrote the Narrative, argues that the "razor and blade" model only works if retention outside China holds up. The latest quarter keeps that modernization and maintenance story intact.
The more immediate swing factor looks like service portfolio retention and pricing, not the bond deal or even new equipment volume. Debt levels and negative equity remain key balance sheet watchpoints, so the new notes are more of a funding choice than a shift in the operating picture.
The most directly relevant update is the US$500 million fixed rate bond issue, with 5.825% notes due 2036 that are senior, unsecured and callable. For you as a shareholder, that sits alongside existing high debt and means future interest costs and refinancing terms deserve close attention when you think about earnings quality.
OLetourneau stresses that "the rail is the portfolio, and the portfolio is under pressure." This bond financing does not resolve that operational risk. It may give Otis Worldwide more flexibility to keep servicing and modernizing its 2.5 million unit book, but execution on retention, modernization volumes and pricing still drives the main catalysts.
In OLetourneau's narrative, the fair value of US$88.58 for Otis Worldwide comes from applying a 5.5% annual revenue growth assumption and a future profit margin of 11.0%. Together, these assumptions frame what earnings power the installed service portfolio could support over time.
Uncover how Otis Worldwide's fair value indicates a 12% potential upside to its current price before that discount narrows.
Exploring Other Perspectives
One alternate view puts modernization timing at the center of the risk. The most cautious analysts were assuming revenue of about US$17.0b and earnings of US$1.9b by 2029, with only 4.5% annual sales growth, before this bond deal and dividend affirmation. That is a much more restrained Otis Worldwide story, so it is worth exploring how their thesis might shift after these updates.
Explore 4 other Otis Worldwide fair value estimates, including one that suggests as much as 8% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Otis Worldwide research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Otis Worldwide. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Otis Worldwide's overall financial health at a glance.
Looking for more investment ideas beyond Otis Worldwide?
If Otis Worldwide fits your checklist on services, cash flows and funding, it can still help to compare it with other listed businesses that share similar strengths or offer a different balance of risk and income.
- For investors who want income plus resilience, consider stocks that appear capable of supporting stronger payouts inside the 7 dividend fortresses.
- If capital preservation is your first filter, compare Otis Worldwide with companies that screen well for stability and downside protection using the 31 resilient stocks with low risk scores.
- If you prefer to hunt for quality at a reasonable entry point, run the same logic across a wider field of candidates with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com