


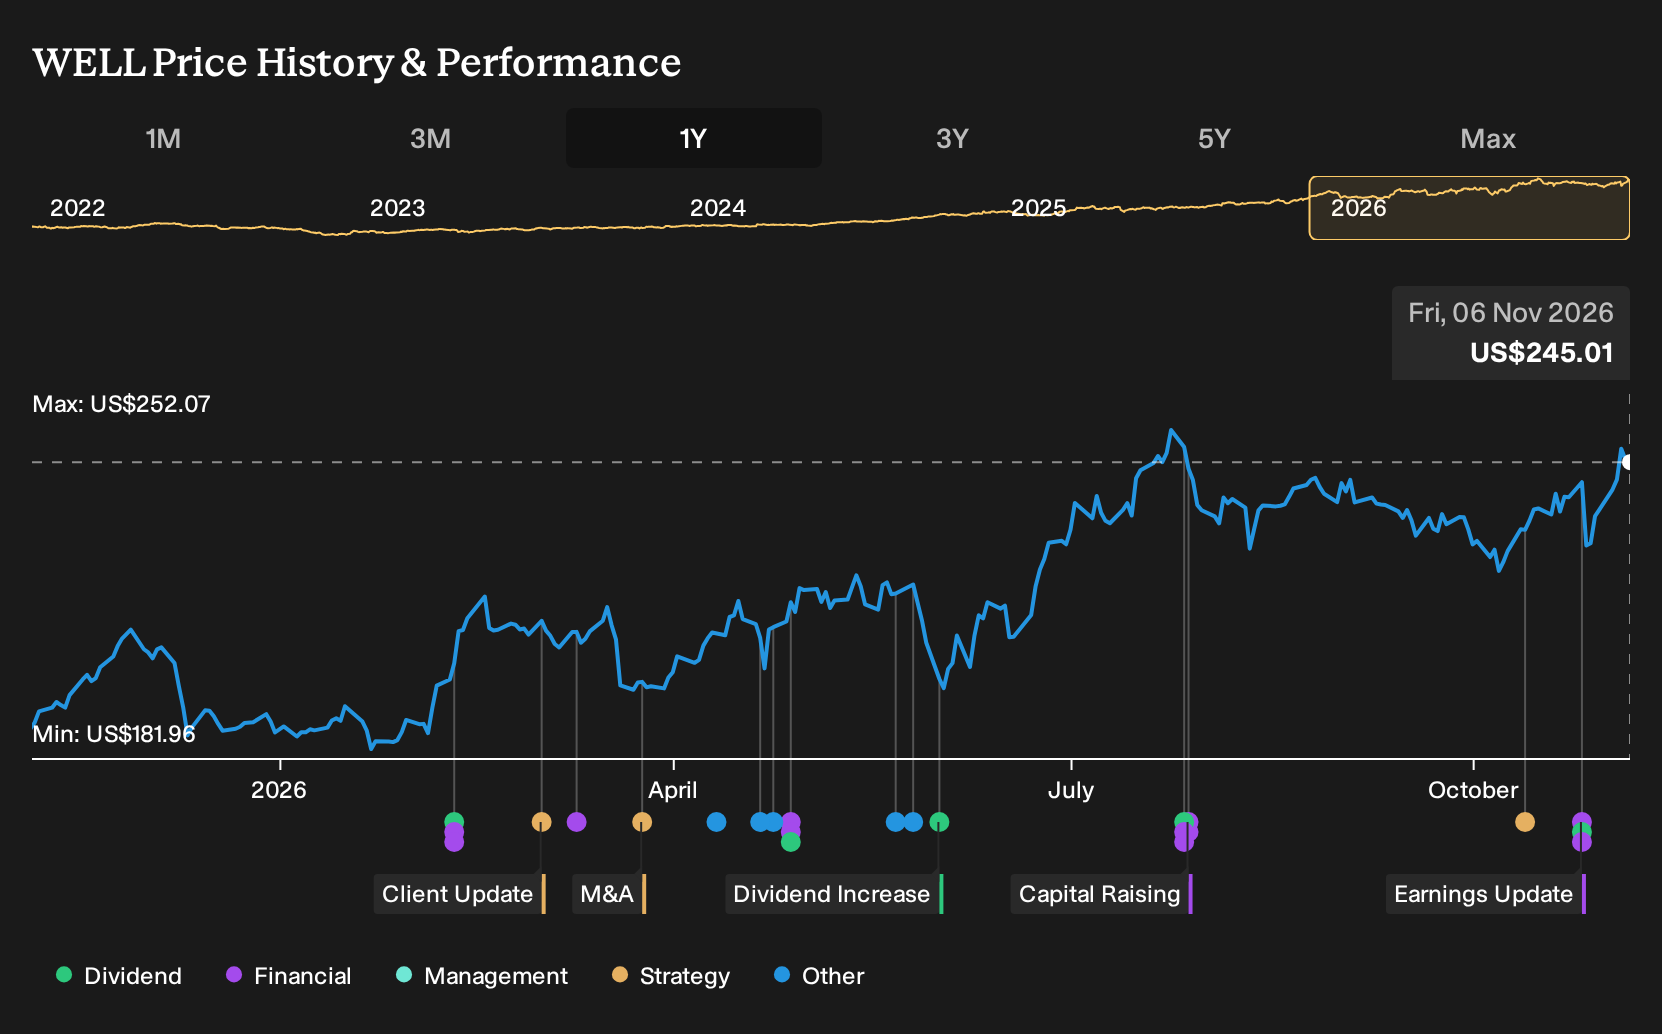
- Welltower reported third quarter 2026 results that included US$488.64 million in sales, US$3,715.78 million in revenue and US$396.59 million in net income, along with higher basic and diluted earnings per share from continuing operations compared with a year earlier.
- The board also declared the 222nd consecutive quarterly dividend at US$0.85 per share, and management raised full year 2026 net income guidance per diluted share, which indicates how the business currently views the durability of its earnings power.
- The next step is to assess how Welltower's investment narrative aligns with management's higher 2026 earnings guidance following this quarter.
Scan how Welltower's earnings guidance and dividend streak compare with peers by reviewing the hand picked 31 resilient stocks with low risk scores, which pairs resilient balance sheets with more controlled risk profiles.
Welltower Investment Narrative Recap
To own Welltower, you need to be comfortable with a seniors housing focused real estate model where occupancy, rent per room and operating efficiency drive most of the story. The analyst consensus Narrative on Simply Wall St leans heavily on that theme. The latest quarter shows higher revenue and net income alongside EPS from continuing operations, which supports that operational angle in the near term.
The more immediate catalyst remains execution on recently acquired and recycled senior housing assets, while keeping expenses in check through the Welltower Business System. The key risk is that macro conditions or weaker than expected resident demand slow occupancy and pricing progress, which would make the higher 2026 earnings guidance harder to sustain.
The most relevant update is management raising 2026 net income guidance per diluted share to US$3.31 to US$3.37 from US$3.11 to US$3.19. That move sits alongside nine month net income of US$1.57b and higher basic and diluted EPS from continuing operations compared with a year earlier.
For you as an investor, the guidance change sharpens the focus on execution risk. The business now has to deliver more from its senior housing portfolio, recent off market acquisitions and the private fund platform while managing interest costs and governance concerns. Progress on occupancy, margins and fee income will be watched closely against this higher earnings bar.
Welltower's current earnings are about US$1.6b, and analysts expect earnings to reach US$2.9b by 2029, which implies an increase of roughly US$1.3b. Their projections also point to revenue of US$19.3b by 2029, supported by an assumed 14.8% yearly rise in revenue over the next three years.
Uncover why Welltower's fair value indicates a 7% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
Not every analyst reads Welltower the same way. Some of the lowest forecasts before this earnings beat were building in revenue of about US$17.9b and earnings of roughly US$2.2b by 2029, paired with a high P/E near 108x. That more cautious view treats any slowdown in seniors housing rate growth as a real threat. You can use this spread in expectations as a prompt to compare several narratives and decide which set of assumptions feels closer to your own.
Explore 5 other Welltower fair value estimates, including one that suggests as much as 7% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Welltower research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Welltower. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Welltower's overall financial health at a glance.
Looking for more investment ideas beyond Welltower?
Once you have a view on Welltower, it can help to widen the lens and compare it with other companies that share some of the qualities you care about most.
- For investors focused on steady income and durability, review 7 dividend fortresses to see which high yield payers pair generous distributions with more resilient profiles.
- If you want to focus on quality at a reasonable price, scan the 40 high quality undervalued stocks that filters for businesses combining stronger fundamentals with more attractive valuations.
- When capital preservation sits higher on your list, check the list of solid balance sheet and fundamentals (25 results) to find companies built on sturdier financial foundations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com