

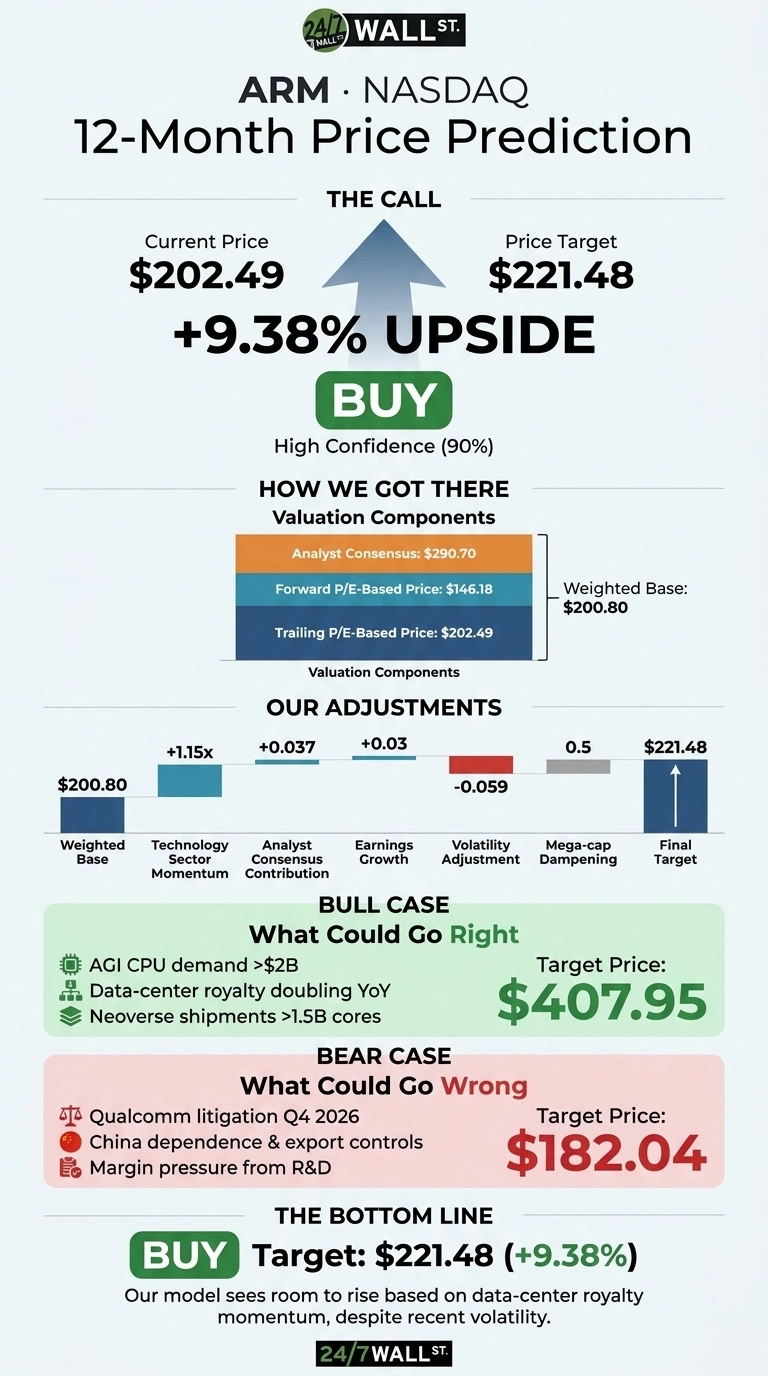
Arm Holdings (NASDAQ:ARM) closed at $202.49, and our 24/7 Wall St. price target of $221.48 implies 9.38% upside over 12 months. The model rates the stock a buy with high confidence.
24/7 Wall St. Price Target Summary Metric Value Current Price $202.49 24/7 Wall St. Price Target $221.48 Upside/Downside 9.38% Recommendation BUY Confidence Level 90%Most investors chase AI through accelerator makers. Arm takes a different approach. It licenses CPU architecture and collects a royalty on every chip its partners ship, which produces a 92.48% gross margin and a net cash balance sheet.
Now it is also selling its own data-center chip, the Arm AGI CPU. A steep drop has brought the price down to a level where our model sees room to rise.
A 34% Monthly Slide Reshapes Arm’s Valuation PictureShares fell 10.79% over the past week, 34.26% over the past month and 27.83% over the past quarter. Even so, they remain up 84.93% year to date. Arm trades 55.27% below its $452.70 52-week high and 102.45% above its $100.02 low.
In fiscal Q1 2027, revenue came in at $1.289B (+22.4% YoY), ahead of the $1.267B consensus. GAAP EPS of $0.25 missed expectations, while non-GAAP EPS reached 45 cents. Data-center royalties more than doubled year over year.
 24/7 Wall St. Why Bulls See $400+ Ahead
Arm Neoverse shipments have passed 1.5 billion cores, and the latest 500 million shipped in just nine months. Vera from NVIDIA (NASDAQ:NVDA), Google’s Axion, AWS Graviton 5 and Microsoft’s Cobalt 200 all run on Arm (we studied what the earliest signals of the next monster chip winner looked like in a free report here: The Next Nvidia Playbook).
The CEO also said demand for the AGI CPU has outgrown the opportunity first outlined. Among analysts, 8 rate the stock Strong Buy and 21 rate it Buy. If data-center royalties keep compounding, our bull scenario reaches $407.95.
Risks That Could Drag Arm to $182Arm trades at 239x trailing earnings. Its GAAP operating margin fell to 7% from 11% as R&D rise to $838M. Bulls would answer that this spending funds the AGI CPU, and that the non-GAAP operating margin held near 41%.
Still, a Qualcomm (NASDAQ:QCOM) trial expected in Q4 2026, dependence on Arm China, export controls and weak smartphone sales all add risk. In our bear scenario, the stock falls to $182.04.
Is Arm Pricier Than NVIDIA and Broadcom?NVIDIA is the leading accelerator business and the clearest contrast to Arm’s licensing model. It trades at 13x forward earnings, while quarterly revenue grew 105.85%.
Broadcom (NASDAQ:AVGO) designs custom silicon, which makes it a useful hybrid comparison. Its AI semiconductor revenue rose 221%, and the stock sits at 17x forward earnings.
Company Forward P/E Latest Quarterly Revenue Growth Arm 83x 22.4% NVIDIA 13x 105.85% Broadcom 17x 85.5%Arm’s premium reflects durable royalty streams. Our model puts heavy weight on the forward multiple, which already discounts that premium. Against these peers, the modest upside in our target looks reasonable.
Our Model Says BUY, With Volatility AttachedOur 24/7 Wall St. price target of $221.48 carries a buy rating at 90% confidence. Data-center royalty momentum tips the scale.
I would view the stock positively if AGI CPU shipments increase on schedule and data-center royalties keep doubling. I would grow cautious if the Qualcomm ruling goes against Arm or if margins keep fell. After the recent drop, our model sees room for the price to rise.
Looking further ahead, here is where our model projects Arm could trade, assuming current growth trends and market conditions hold.
Year 24/7 Wall St. Price Target 2026 $207.49 2027 $221.48 2028 $232.95 2029 $267.96 2030 $253.30These projections assume Arm keeps executing on its current strategy. Large moves in either direction could come from AGI CPU adoption or the outcome of the Qualcomm litigation.