


- Napco Security Technologies reported first quarter 2027 results for the period ended September 30, 2026, with revenue of US$49.98 million, net income of US$13.01 million, earnings per share of US$0.36, and a quarterly dividend of US$0.17 per share declared for payment on January 4, 2027.
- Management highlighted a cash and marketable securities balance of US$134.6 million with no debt and outlined plans to pursue acquisitions, organic investments, and market share gains while continuing to return capital to shareholders.
- Next, the focus will be on how Napco Security Technologies' cash-rich, debt-free position and acquisition plans may shape its broader investment narrative.
Compare Napco Security Technologies' cash rich, acquisition focused story with other resilient balance sheet plays by scanning our curated 31 resilient stocks with low risk scores for your next idea.
Napco Security Technologies Investment Narrative Recap
To own Napco Security Technologies, you need to believe the high margin recurring services, StarLink conversions, and newer cloud platforms can keep gaining share within total sales while the equipment side stays healthy. The latest quarter showed solid profitability, a cash rich, debt free balance sheet and no material change to that recurring revenue focused story.
The near term catalyst still leans on recurring service traction from StarLink activations and early MVP cloud adoption, as described in the analyst consensus Narrative on Simply Wall St. The main risk remains pressure from electronic component costs or supply constraints, which could limit margin progress. The recent results and acquisition commentary do not materially change this balance.
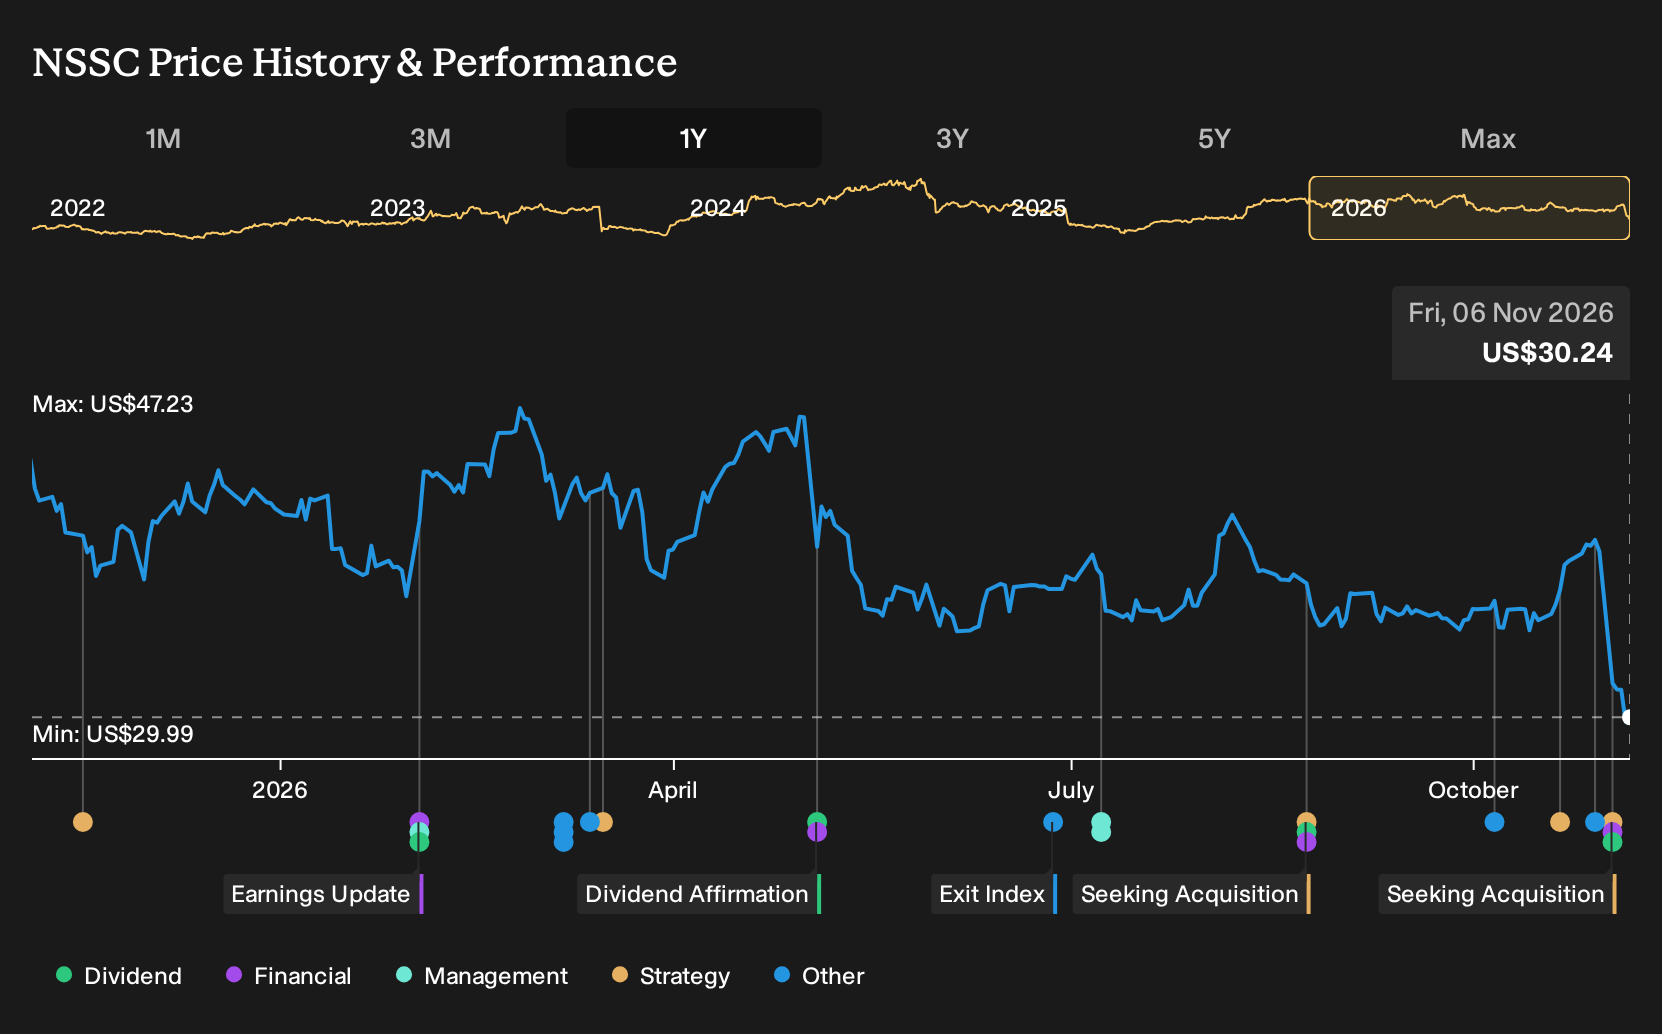
The conference call comments about seeking acquisitions look most relevant here. Management highlighted US$134.6 million of cash and marketable securities with no debt and a plan to evaluate organic investments and potential deals that fit existing products and services. That gives the business options if internal product ramps slow or customer demand shifts.
For catalysts, any acquisition that adds new subscription style offerings or expands the communication products footprint could support the recurring revenue mix analysts focus on. Execution risk is real, however. Integrating a target while managing component costs, StarLink conversion pacing, and one off items that have recently affected earnings quality will be important for the Napco Security Technologies story investors are watching.
Napco Security Technologies' current narrative builds around analysts assuming revenue will rise by 8.0% a year, with earnings today of US$43.9 million projected to reach US$81.2 million by 2029. This implies roughly an 85% increase in profit as revenues climb toward an estimated US$255.6 million in that same year.
Uncover how Napco Security Technologies' fair value indicates a 47% potential upside to its current price that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Bullish analysts are focused on acquisitions as the big swing factor. Before this update, the most optimistic forecasts already had Napco Security Technologies reaching about US$265.1 million of revenue and US$83.9 million of earnings by 2029. It is clear how those upbeat views might shift once this cash rich, deal hunting message fully sinks in.
Explore 3 other Napco Security Technologies fair value estimates, including one that suggests potential upside of up to 47% from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Napco Security Technologies research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Napco Security Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Napco Security Technologies' overall financial health at a glance.
Looking For More Ideas Beyond Napco Security Technologies?
If Napco Security Technologies has sharpened your thinking but you want a broader watchlist, use the Simply Wall St screener to line up other stocks that fit different angles of your strategy and compare how their fundamentals stack up.
- For investors who care most about financial resilience and steady balance sheets, scan a curated list of solid balance sheet and fundamentals (25 results) that can help you stress test your portfolio.
- If you are hunting for quality companies that the market may be overlooking, broaden your opportunity set with a focused sweep of 19 high quality undiscovered gems that already show strong fundamentals.
- When your priority is capital preservation and controlled risk, filter for sturdier profiles using a hand picked 31 resilient stocks with low risk scores that can complement a position in Napco Security Technologies.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com