


Fresh commentary on Frontline (NYSE:FRO) has zeroed in on a widening split in valuation views, with some analysts flagging a premium to intrinsic value while others highlight the company’s modern tanker fleet as a potential support.
Recent trading has cooled some of Frontline’s earlier momentum, with a 30-day share price return that is down 19.04% and a 7-day move that is down 12.79%. Even so, the share price sits at US$45.42, and the 1-year total shareholder return of 118.39% and 5-year total shareholder return of about 8x keep the longer run picture firmly in focus.
Scan beyond Frontline and line up other shipping plays with sharp valuation debates using our curated list of 40 high quality undervalued stocks.
Frontline now carries a modern fleet and a share price that has surged over 1 year, even after the recent pullback. Does that combination still leave enough value on the table today, or not quite?
Most Popular Narrative: 33% Overvalued
Frontline last closed at $45.42, while the leading narrative on Simply Wall St pegs fair value at $34.07, which implies the stock is trading at a premium according to that view. That framing, built by LunaRodas, a Simply Wall St Community investor, rests on how management’s own words on “an ocean of profits” line up with capital allocation choices and risk signals coming through the latest calls.
The record financial performance that Barstad previewed in May, “potentially even more rewarding” than Q1’s best-since-2004 results, arrived in full. Adjusted profit of $580.2 million in Q2 versus $344.9 million in Q1, and a record quarterly result by any measure the company tracks.
See why 8 investors see Frontline as 33% overvalued.
The narrative argues that this surge in results sits next to a softer tone on some earlier pillars, such as Iran sanctions relief and detailed fleet mechanics, which now receive far less airtime. It also highlights Frontline’s comfort with a higher debt load and its choice to sell VLCCs and send cash out as special dividends, rather than focusing on balance sheet repair as a primary use of what the narrative calls a “generational market.”
For readers weighing the recent 1-year total shareholder return of 118.39% and a fair value estimate of $34.07, the key question is whether that past period reflects conditions that are unusually strong compared with what the earnings forecasts now imply, or whether the premium over the narrative’s fair value is a trade off they are prepared to accept.
Result: Fair Value of $34.07 (OVERVALUED)
Still, Frontline’s reliance on an “ocean of profits” framing and its comfort with higher leverage could crack quickly if tanker rates or asset values reset.
Find out about the key risks to this Frontline narrative.
Another View on Frontline’s Valuation
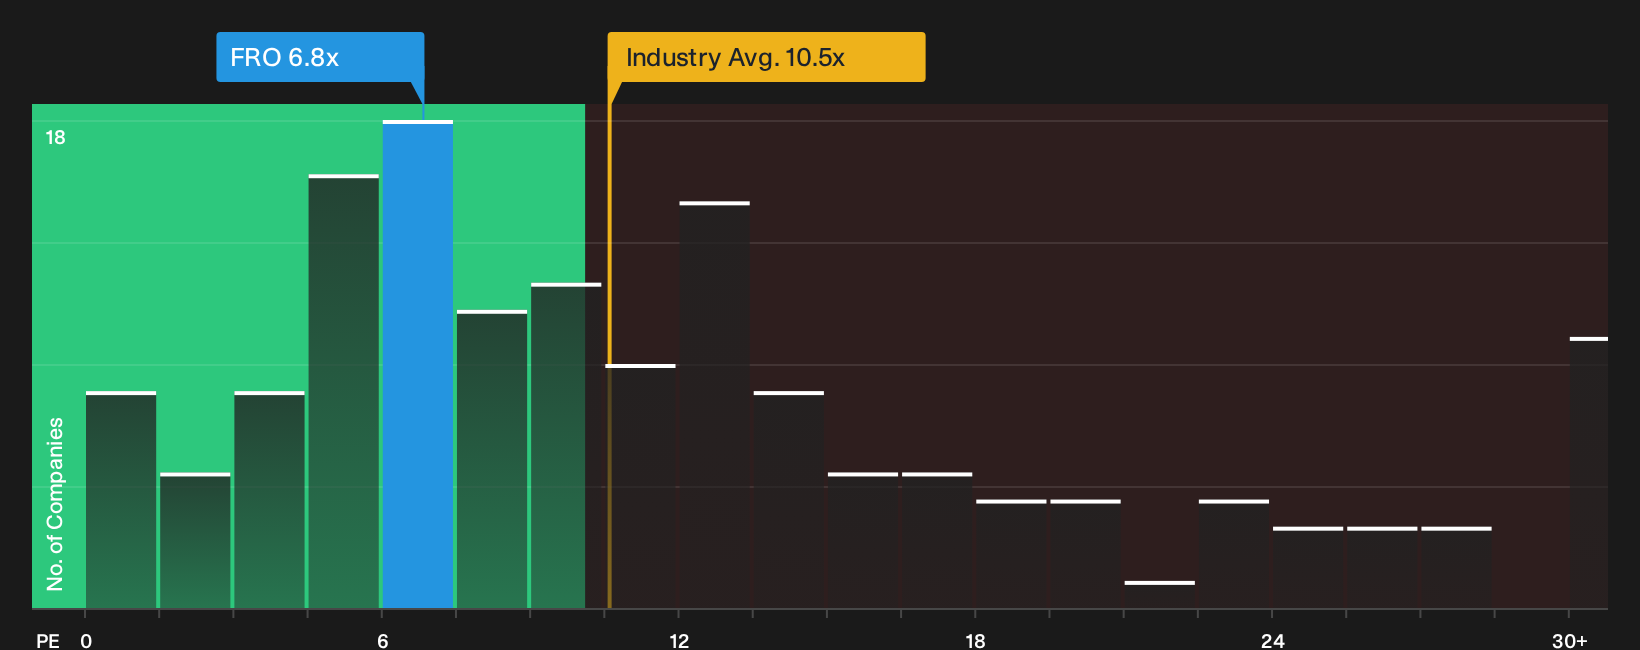
That 33% premium to a US$34.07 fair value is not the only lens on Frontline. The stock trades on a P/E of 6.8x compared with 10.5x for the US Oil and Gas industry and 16.9x for peers, while the fair ratio sits at 7.4x. Does that gap hint at mispricing, or does it reflect earnings risk already flagged in forecasts?
See what the numbers say about this price in our valuation breakdown.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like this can create a lot of noise, so check the underlying data now and decide where you land on Frontline’s risk reward balance by weighing its 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Frontline?
If you want a broader watchlist that matches your style, use these curated screens to surface opportunities before they land on everyone else’s radar.
- Target resilient balance sheets and dependable fundamentals with a focused list of solid balance sheet and fundamentals (25 results) that keeps weaker financial structures off your shortlist.
- Hunt for quality at a discount by scanning a 40 high quality undervalued stocks that filters for both strong cash generation and disciplined financial profiles.
- Spot potential up-and-comers early through a 19 high quality undiscovered gems designed to surface lesser-known businesses with underlying strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com